
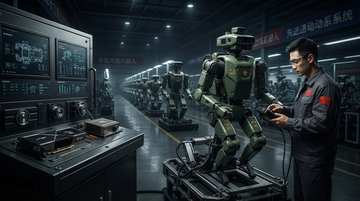
Reuters' September 7 piece by Eduardo Baptista — \"From dance floor to war: China readies humanoid robots for combat\" — is the first open-source documentation of three PLA procurement actions that, taken together, move humanoid robotics out of the \"lab demo\" bucket and into a defence procurement cycle. The PLA issued a humanoid tender in May 2025; four months later, a National University of Defense Technology (\"NUDT\")-contacted notice sought an \"embodied humanoid robot intelligent perception and dexterous operation system\"; and in June 2026, the PLA budgeted about $300,000 for a camera, radar and motion-data labelling system built around humanoids. Reuters could not confirm which vendors filled the May and September 2025 tenders — but the procurement clock has clearly started.
Norinco's Fuxi humanoid, paired with its own teleoperation system, is already described in company materials as capable of sentry duty, all-weather reconnaissance and dangerous-role substitution — i.e., the doctrine is being written before the procurement award.
PLA humanoid procurement actions confirmed by Reuters
3
May 2025 tender; ~Sept 2025 NUDT embodied-systems tender; June 2026 ~$300K data-labelling system
China share of global humanoid shipments, 2025
~95%
BofA Global Research; cited by Reuters Sept 7, 2026
China humanoid production target, 2026
100,000+ units
MIIT official Gan Xiaobin, July 2026
Unitree Robotics 2025 revenue
RMB 1.70B
+335% YoY, per 2026 IPO prospectus
Unitree Aug 19, 2026 STAR Market debut close
RMB 845
Up 460% from RMB 150.80 IPO price; mkt cap ~$50B at close
Norinco Fuxi humanoid, fully loaded weight
~90 kg
Global Times, Aug 18, 2026
Pentagon Section 1260H list expansion
188 entities
June 8, 2026 update; Unitree, Alibaba, BYD, Baidu, Tencent, DJI added
The 95% Supply Story Has a Pentagon Footnote
BofA Global Research's 95% share figure — about 19,000 of roughly 20,000 humanoids shipped globally in 2025 — is the structural backdrop. China was already the only place with scale humanoid manufacturing when the Reuters piece landed. The June 8, 2026 update to the Pentagon's Section 1260H list — 188 Chinese entities newly named as contributors to the Chinese military-industrial base, including Unitree Robotics, Alibaba, BYD, Baidu, Tencent and DJI — converted that commercial lead into a defence-policy fact.
Reuters' August 19 follow-up on Unitree's STAR Market debut closed the loop: a Chinese humanoid pure-play now trades on a US-sanctioned-entity-adjacent thesis with a ~$50B day-one valuation. The Pentagon list came ten weeks before the IPO — institutional investors had the policy signal before they had the ticker.
Defence Demand Is Splitting One Market Into Three
Until this week, \"humanoid robotics\" meant consumer/IPO entertainment plus factory-floor pilots. The Reuters story creates a third vertical — government/defence — with very different unit economics: lower volume, longer design cycles, higher per-unit margin, and a buyer that publishes procurement notices.
Three Chinese listed names already straddle the split.
| Company | Ticker | FY25 Revenue | FY25 Net Profit | Market Cap | Humanoid Posture |
|---|---|---|---|---|---|
| Unitree Robotics | 688836.SS | RMB 1.70B (+335%) | RMB 278M | ~RMB 270B | Pure-play humanoid; 5,500+ shipped in 2025; Pentagon 1260H list (June 2026); STAR Market debut Aug 19, 2026 at +460% |
| UBTech Robotics | 9880.HK | RMB 2.00B | RMB (703M) loss | HKD 37B | First humanoid HK listing (Dec 2023); Pentagon 1260H list; FY25 R&D 25% of revenue; gross margin 38% |
| Inner Mongolia First Machinery / Norinco | 600967.SS | RMB 10.0B | RMB 335M | RMB 17.7B | Norinco Group's listed defence arm; Fuxi teleoperated humanoid (90 kg) developed by group innovation institute; gross margin only 10.8% — margin upside if Fuxi scales |
Norinco itself — China North Industries Group Corporation — is the state-owned defence conglomerate that built the Fuxi. Reuters also identifies Unitree's humanoids as a competing platform, with Beijing Academy of Artificial Intelligence-trained systems (the THOR whole-body model) running on Unitree's G1. The \"defence vertical\" is therefore not a single-supplier story: state-owned Norinco develops one platform, the listed private-sector leader develops another, and the Pentagon's 1260H designation now links both to the same US procurement firewall.
The Supply Chain Re-Rate Has Two Halves
Reuters' own story is about finished humanoids. The investment re-rate, however, starts upstream — in the components that have to scale from 20,000 units a year to the 100,000-unit target China's Ministry of Industry and Information Technology set in July 2026.
Two listed names control the highest-value pieces.
| Company | Ticker | TTM Revenue | Gross Margin | Forward P/E | Exposure |
|---|---|---|---|---|---|
| Harmonic Drive Systems | 6324.T | JPY 62.7B (TTM) | 32.3% | 185x TTM | Japan-listed leader in harmonic speed reducers — the single highest-value joint in a humanoid; 52-week range JPY 2,334–9,150 reflects the humanoid rerate |
| Shenzhen Inovance | 300124.SZ | RMB 49.3B (TTM) | 28.5% | 32x | China's largest industrial-automation supplier; servos, motion controllers, robot components; R&D 9.1% of revenue |
| Estun Automation | 002747.SZ | RMB 4.9B (TTM) | 31.0% | 147x | Nanjing-based; six-axis and SCARA robots, AC servos, motion control — supplies both humanoid and industrial robot lines |
Semiconductor-side, the Reuters story does not name a chip supplier, but Renesas Electronics — Japan's largest auto-and-industrial MCU maker — has been the most aggressive listed humanoid beneficiary outside China. Goldman Sachs named it a top Japan electronic-components pick on humanoid exposure; Renesas trades at a humanoid-cycle premium even as its legacy auto franchise is mature. On the compute side, NVIDIA supplies the simulation/training backbone across the entire humanoid industry, Chinese and Western alike — and is unaffected by the bilateral firewall because its chips are not the sanctioned item.
US and Allied Peers Are Behind on Procurement, Not on Tech
The US side is the laggard. Reuters notes the US Army's humanoid competition offers up to $1.25 million in follow-on contracts — a pilot-scale budget line. China's PLA tenders are similarly sized (the June 2026 system was ~$300,000), but the cadence and the institutional buyer list are longer.
Three listed US/Korea names span the comparison.
- Tesla Optimus — Gen 3 production was not running on the new Fremont line as of mid-July 2026; analyst production-target range for end-2026 starts at ~1,000 units/week. Q2 FY2026 revenue was $103.6B (TTM), Optimus remains pre-commercial and is not in guidance.
- XPeng IRON — public roadmap targets \"over 1,000\" IRON units produced in 2026; SDK opening signals a developer ecosystem rather than direct defence play; XPEV's market cap of ~$20B reflects the optionality, not a humanoid line.
- Hyundai Motor — owner of Boston Dynamics after the July 2026 buyout of SoftBank's 9.65% stake (~$325M); CES 2026 product reveal of Atlas; all 2026 production committed to Hyundai's Robotics Metaplant Application Center and Google DeepMind; Reuters confirms Hyundai plans US factory deployment by 2028.
The structural gap: the PLA is buying now. Hyundai/Boston Dynamics, Tesla and XPeng are still on the demo-and-pilot curve. The Pentagon's 1260H designation of Unitree signals that the procurement firewall is being built ahead of the US defence-tech base reaching the same stage — which is why Anduril ($61B Series H in May 2026, $22B Army IVAS ceiling) and Hadrian ($7.87B Series D on August 6, 2026) are now raising against a US defence-supply-chain gap, not a finished humanoid product.
Short-Term: What Moves in Days and Quarters
- Unitree — Sept-2026 PLA tender outcome (Reuters could not confirm which companies won the May/September 2025 tenders): a yes/no on Unitree participation is the next binary catalyst.
- Inner Mongolia First Machinery / Norinco — first formal Fuxi delivery schedule or PLA order disclosure; the listed arm has not yet booked humanoid revenue, so any disclosure is positive optionality.
- Harmonic Drive Systems — Q2 FY2027 (Sept 30, 2026 quarter-end) results; the 52-week range has already absorbed the humanoid narrative, so guidance matters more than the headline.
- UBTech — interim H1 2026 results and any Pentagon-1260H-driven institutional reshuffle; current HK$37B cap prices in some humanoid defence premium already.
- Hyundai Motor — Boston Dynamics FY2026 production update after CES-2026 product reveal; all 2026 Atlas production is committed, so 2027 capacity is the next event.
Long-Term: The Defence-Anchored Valuation Benchmark
Reuters' story matters less for what it changes today than for what it changes about how investors should price the humanoid complex from here.
Until September, the dominant valuation benchmark was factory-floor: how many units per year, what cost, what gross margin. The PLA-procurement confirmation adds a third benchmark — defence procurement — with three durable features:
- Lower volume, higher margin. A defence contract for 1,000 teleoperated humanoids at a 35–40% gross margin is worth more per unit than a 100,000-unit consumer batch at 20%. Reuters confirms Norinco's Fuxi is teleoperated, not autonomous — that is a premium-content product, not a commodity.
- Sticky customers. Reuters notes NUDT and Academy of Military Sciences research, PLA Eastern Theater Command scenarios, and explicit procurement notices. Once a defence buyer qualifies a platform, switching cost is high.
- Bifurcated supply chains. China's MIIT wants 100,000+ units in 2026; the Pentagon has just named Unitree and DJI on 1260H. Component makers — Harmonic Drive Systems, Renesas, Inovance, Estun Automation — sell into both, but finished platforms cannot.
The honest limits: Reuters itself could not confirm which vendors won the May 2025 and September 2025 PLA tenders; the June 2026 $300,000 line item is a data-labelling budget, not a robot order; and Unitree's 5,500+ 2025 humanoid shipments are still overwhelmingly entertainment/industrial. The defence angle is real, but it is still small in revenue terms — what the Reuters piece actually confirmed is that the procurement clock has started.
Related stocks
- Pentagon 1260H designation (June 8, 2026) reframes the company from entertainment-led to defence-optionality; STAR Market close RMB 845 on Aug 19, 2026 implied ~$50B valuation versus RMB 1.70B FY25 revenue.
- 5,500+ humanoid units shipped in 2025 with 59.5% gross margin on the core business (IPO prospectus) — first mover advantage in any PLA follow-on tender after the May 2025 / Sept 2025 actions Reuters documented.
- Watch the next 12 months for the first PLA tender award disclosure (Reuters could not confirm winners); a Unitree win extends the Pentagon-1260H premium into actual defence revenue, a loss leaves the premium as overhang.
- Norinco Group's Fuxi teleoperated military humanoid (~90 kg) is a Norinco-innovation-institute product; listed arm at RMB 17.7B market cap does not yet book humanoid revenue — embedded option.
- FY2025 net profit of RMB 335M on RMB 10.0B revenue at only 10.8% gross margin means even a small Fuxi order flow is a multiple-event for the listed entity.
- Long-term (1–3 years): if Norinco formalises Fuxi as a product line, Inner Mongolia First Machinery is the closest listed proxy; the Pentagon's 1260H inclusion of Norinco Group limits the western buyer base but reinforces the China-defence thesis.
- Pentagon 1260H list (June 8, 2026) names UBTech alongside Unitree; current HK$37B market cap prices in some humanoid-defence premium despite FY2025 RMB (703M) net loss and 22.5% R&D-to-revenue ratio.
- 38.2% TTM gross margin is the highest of the three Chinese pure-plays — closer to a software/services blend than a hardware commodity, which is what a defence buyer would pay for.
- Watch H1 2026 results for any PLA or Chinese-government humanoid order disclosure; binary catalyst in days-quarters, structural question is whether UBTech closes the FY2025 loss against the 1260H premium.
- Public roadmap targets \"over 1,000\" IRON units in 2026 (Reuters-cited); SDK opened November 2025, signalling a developer ecosystem rather than a defence play.
- Reuters' PLA-procurement read-through is negative for non-defence pure-plays — the China humanoid narrative is shifting toward military buyers, and XPeng's auto-OEM background sits on the consumer side of the split.
- Long-term (1–3 years): XPeng's IRON is competing for the same Chinese component supply (Inovance, Estun, Harmonic Drive) as PLA-tendered platforms; component pricing power goes to the defence buyer, squeezing consumer-side margins.
- Optimus Gen 3 production was not running on the new Fremont line as of mid-July 2026 — Tesla sits well behind Unitree on shipment volume and well behind PLA procurement on buyer readiness.
- Q2 FY2026 revenue of $103.6B (TTM) at 18.9% gross margin shows Optimus is not yet in the financials; the Pentagon 1260H firewall on Chinese suppliers raises the value of a non-sanctioned US alternative — but only if Optimus ships.
- Watch Tesla's Q3 FY2026 update for first Optimus production confirmation; a no-ship in 2026 hands the defence-buyer narrative entirely to Chinese suppliers.
- Boston Dynamics Atlas product reveal at CES 2026 — all 2026 production committed to Hyundai's Robotics Metaplant Application Center and Google DeepMind; Reuters confirms Hyundai plans US factory deployment by 2028.
- July 2026 buyout of SoftBank's 9.65% Boston Dynamics stake (~$325M) completes Hyundai's 100% control; Hyundai Motor is the cleanest listed proxy for non-Chinese humanoid capacity.
- Long-term (1–3 years): if the US Department of War moves to a non-Chinese humanoid procurement standard, Atlas becomes the default US-allied bidder; near-term, 2026 production is fully absorbed internally.
- Reuters' PLA-procurement confirmation extends the humanoid demand curve from factory to defence; Harmonic Drive Systems sells into both Chinese and Western assemblers and is unaffected by bilateral firewalls.
- 6324.T 52-week range of JPY 2,334–9,150 reflects the humanoid re-rate already; FY2026 (March-end) revenue of JPY 59.6B at 32.3% gross margin — guidance for FY2027 (ending March 2027) is the next catalyst.
- 185x TTM P/E prices a humanoid cycle, not a near-term profit reset; the Reuters read-through is positive for the next 1–3 years as Chinese demand moves from 100,000 MIIT units toward PLA tenders.
- China's largest industrial-automation supplier; servos, motion controllers and robot components feed both PLA-tendered humanoids and consumer/entertainment humanoids; TTM revenue RMB 49.3B at 28.5% gross margin and 9.1% R&D ratio.
- Reuters' confirmation that the PLA is collecting camera, radar and motion data on humanoids (June 2026, ~$300K) feeds directly into the data-labelling and motion-control stack Inovance already supplies.
- Long-term (1–3 years): as China humanoid production moves from MIIT's 100,000-unit 2026 target toward PLA follow-on tenders, Inovance is the highest-volume domestic component beneficiary — 32x TTM P/E versus Harmonic Drive's 185x leaves valuation room.