
Senate cloture threshold
60 votes
Republicans hold 53; at least 7 Democrats needed to proceed to CLARITY Act debate on Sept. 15, 2026
Polymarket 2026 enactment
15%
As of Sept. 2, 2026; down from 82% peak on Feb. 19, 2026
Crypto 2026 election spending
$190M+
Crypto industry cumulative political spending through2026 cycle per Reuters
Community bank deposits at risk
$1.3T
ICBA estimate if stablecoin-yield is permitted; would translate into $850B lost lending capacity
Circle USDC held on Coinbase
$20B avg
Q2 2026; >30% of all USDC in circulation, per Coinbase Q2 2026 earnings release
Visa stablecoin settlement run rate
$3.5B annualized
As of Nov. 30, 2025, per Visa press release (Dec. 16, 2025)
The Home-State Blitz Has Become the Decisive Front
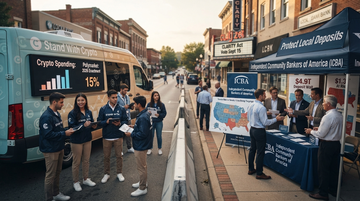
Coinbase-backed Stand With Crypto has mobilized roughly 3 million advocates, placed op-eds in the home-state papers of Sen. Rand Paul (Kentucky), Sen. James Lankford (Oklahoma) and Sen. Jerry Moran (Kansas), and staged in-person events in Iowa and Michigan during the recess that began August 8. Crypto supporters contacted members of Congress nearly 50,000 times in August, per the September 9 Reuters report. The Blockchain Association launched clarityforamerica.com in late July to turn that activity into a direct mail pipeline.
Banks are answering in kind. The Independent Community Bankers of America has been running a TV commercial during the U.S. Open tennis tournament, airing in Washington, D.C. and in targeted states, while its50,000-member base shows up at senators' home offices. American Bankers Association chair Kenneth Kelly told Politico that ABA members will reach out to senators back home over the August recess to push 'modest changes' — code for closing the stablecoin-yield loophole. The fight has gone inside the home state of Sen. Mike Rounds (R-S.D.), who told Politico he plans to advance the bill but supports bank-favored floor amendments.
Three Live Senate Fights Decide the Economics
- Stablecoin rewards language — Banks want a hard ban on interest/yield paid by intermediaries on USDC holdings; crypto wants the Tillis-Alsobrooks compromise that permits transaction- and activity-based rewards. ICBA Chair Alice Frazier has called this the 'most important thing' on the group's Washington agenda.
- Ethics and conflicts of interest — Democrats led by Sen. Chris Murphy and Sen. Mark Warner want stronger presidential-and-family disclosure rules after the Trump family's World Liberty Financial stablecoin ties; the merged draft added an ethics provision in late July.
- DeFi scope and SEC/CFTC jurisdiction — The bill assigns most crypto oversight to the CFTC and leaves the SEC with a narrower anti-fraud lane; SEC Chair Atkins has publicly hoped for a Sept. 15 win, but the actual language is still in flux.
Stablecoins Already Move More Money Than the Card Networks
The fight isn't theoretical. Morph Research projects annual stablecoin settlement could exceed $50 trillion in the U.S. by year-end 2026, and Treasury has cited a path from the current $300 billion stablecoin market to $3 trillion by the end of the decade — tenfold growth that Circle and Coinbase are already harvesting.
Stablecoin and card-network transaction volumes compared
Annualized USD transaction volume at the most recent disclosed period; stablecoins already exceed both card networks combined.
Unit: USD trillion, annualized
Visa payment volume (FY2025)
Trailing-12-month payments volume
14.2
Mastercard payments volume (LTM)
Q2 2026 LTM GDV
9.8
Visa stablecoin settlement
Annualized run rate, Nov 30, 2025
3.5
Total stablecoin settlement (2025)
Crossmint, citing 2024 transaction volume
27.6
Coinbase and Circle Win Either Way, But Differently
Coinbase is the most direct pure-play. USDC revenue — a revenue-share with Circle tied to reserve yield on balances held in Coinbase products — hit $305 million in Q1 2026, or 44% of total revenue, per Coinbase's Q1 2026 earnings release. Q2 2026 set another record: average USDC on Coinbase products reached $20 billion, more than 30% of all USDC in circulation. If CLARITY passes with permissive yield language, that revenue line scales with the Treasury projection to $3T; if it passes with bank-style guardrails, Coinbase loses the yield but keeps distribution and the 100 million payments already processed through its x402 protocol.
| Company | Ticker | Mkt cap | Q2 2026 revenue | Stablecoin leverage |
|---|---|---|---|---|
| Coinbase Global | coin | $47.1B | $1.22B | USDC reserve yield + distribution; 44% of FY2026 revenue mix |
| Circle Internet | crcl | $25.7B | $0.70B | USDC issuer; gets100% of reserve interest, pays distribution to Coinbase |
The Banks Are Defending a $4.9T Deposit Franchise
Community banks hold $4.9 trillion in deposits that fund $4.1 trillion in local lending, per ICBA data. If even a portion of stablecoin volume migrates from checking accounts into USDC, the ICBA projects a $1.3 trillion deposit drain and an $850 billion decline in lending — money that, in the bank's telling, would not flow back into Main Street loans. Community banks make nearly 90% of commercial-bank farmland loans under $500,000 and 81% of farm real-estate debt held by commercial banks.
Wells Fargo Q2 2026 revenue
(n/a)
TTM revenue $83.0B; deposit-funded model directly exposed to stablecoin yield competition
Citigroup Q2 2026 revenue
(n/a)
TTM revenue $81.7B; deposit base under Services and USPB segments most at risk
The Payment Networks Sit on Both Sides of the Trade
Visa and Mastercard are doing the thing banks fear: on December 16, 2025 Visa launched U.S. stablecoin settlement, enabling U.S. issuer and acquirer partners to settle in Circle's USDC over the Solana blockchain, with Cross River Bank and Lead Bank as the first banking participants. Monthly stablecoin settlement volume hit a $3.5 billion annualized run rate by November 30, 2025. Six months later, on June 3, 2026, Mastercard matched: settlement capabilities now include regulated stablecoins — Circle's USDC, Paxos's PYUSD, Ripple's RLUSD and SoFi's SoFiUSD — across Arbitrum, Base, Canton, Ethereum, Polygon, Solana, Tempo and XRPL.
Visa trades at 31.4x trailing earnings and 16.1x EV/revenue; Mastercard at 31.8x and 15.0x. Both networks have publicly framed stablecoins as additive volume, not cannibalization — but the long-term economics turn on CLARITY: a permissive yield regime lets Circle and Coinbase capture more of the float, while a strict regime keeps the float inside the banking system that pays Visa and Mastercard to move it.
What the Home-State Math Says About Sept. 15
Republicans need seven Democrats or independents to reach 60. The bankers' coalition is concentrating on Democrats in states with concentrated community-bank footprints — North Dakota, Montana, West Virginia — while Stand With Crypto is targeting crypto-curious Democrats such as Sen. Ruben Gallego (Arizona) and the field offices of holdouts like Sen. Raphael Warnock (Georgia), who voted against advancing CLARITY in committee. Polymarket's 15% 2026-enactment contract — down from a 82% peak on February 19 — implies traders expect cloture to fail or amendments to neuter the bill.
Three Short-Term Catalysts, Three Long-Term Scenarios
- Days to weeks — Sept. 15 cloture vote is binary; expect Circle and Coinbase to move 8–15% on the headline, bank stocks to move 1–3% on deposit-flight repricing.
- Weeks to quarters — SEC-CFTC joint rulemaking deadline (Sept. 16 per industry chatter) sets the regulatory floor under whichever CLARITY outcome lands.
- 1–3 years — If yield-bearing USDC survives, Treasury's $300B → $3T projection implies10x reserve float; if it doesn't, Circle's $1B+ annual distribution payments to Coinbase becomes a cost line, not a revenue line.
Where the Lobby War Priced In First
- USDC reserve-yield revenue already drives 44% of Q1 2026 revenue ($305M); a permissive CLARITY outcome extends that mix into 2027–2028 as stablecoin float scales toward Treasury's $3T projection
- Coinbase holds >30% of all USDC in circulation ($20B avg in Q2 2026) — making it the single biggest distribution counterparty to Circle and the largest exposure to a stablecoin-yield win
- Bear case: if CLARITY dies or hard-bans yield, Coinbase loses the interest flywheel but keeps trading and the x402 payments protocol (100M payments in Q1 2026)
- Q2 2026 net income just $48M (vs. $214M in Q3 2025) shows the rate-sensitive business; a $3T stablecoin market expands the float Circle earns reserve interest on, but yield-competition from bank-issued tokens could compress USDC's franchise over1–3 years per Mizuho
- OCC national trust bank approval (July 10, 2026) puts USDC reserves under direct federal oversight — a structural moat that survives either CLARITY outcome
- Polymarket's 15% 2026 enactment contract implies traders price in delayed or neutered legislation; weak cloture outcome likely hurts short-term sentiment more than fundamentals
- Q2 2026 revenue $35.1B with revenue growth of +14.1% YoY shows the network continues to absorb volume regardless of rail; June 3, 2026 stablecoin settlement launch positions Mastercard as a multi-stablecoin toll-taker
- If CLARITY bans yield, Mastercard keeps the float on its existing 9.8T annualized GDV intact; if yield is permitted, USDC's share of consumer payments expands and Mastercard competes with Visa for stablecoin-settlement economics
- Trades at 31.8x trailing earnings — any stablecoin-share loss is already priced into a multiple that's wider than Visa's 31.4x
- $3.5B annualized stablecoin-settlement run rate (Nov 30, 2025) is a rounding error on Visa's $14.2T payments base — but the December 16, 2025 U.S. launch unlocks 24/7 settlement, a structural efficiency the network monetizes regardless of CLARITY
- Q2 2026 revenue growth +14.4% YoY on $44.5B LTM revenue shows the core is durable; stablecoin is upside optionality, not a threat
- Permissive CLARITY could pull float toward Circle's USDC over1–3 years, but Visa's bank-issuer-and-acquirer settlement model means banks still pay Visa to clear the volume
- Q2 2026 revenue $82.5B with quarterly earnings growth +46.9% YoY shows the deposit franchise has not yet repriced for stablecoin yield competition
- If CLARITY passes with bank-favored guardrails, JPMorgan's $2T+ deposit base is insulated; if it fails and the Senate revisits in 2027, JPMorgan buys time to issue JPMD-style stablecoin
- Trades at 15.4x trailing earnings — a steep discount to Visa/Mastercard that widens further if the home-state bank lobby wins the stablecoin-yield fight
- TTM revenue $113.9B and quarterly revenue growth +16.8% YoY in Q2 2026 reflect a deposit-heavy model most exposed to stablecoin-yield competition — making the American Bankers Association lobbying fight most consequential for Bank of America
- Retail-banking concentration (~67M consumer and small-business clients) puts more of Bank of America's deposit base in the ICBA-style 'Main Street' bucket that stablecoins target
- Trades at 14.5x trailing earnings — if CLARITY hard-bans yield, the multiple should re-rate toward the 16–18x range that banks earned before stablecoin competition became a 2026 election issue
- Q2 2026 LTM revenue $83.0B with revenue growth +9.5% YoY; deposit-base sensitivity is high because retail and commercial deposits dominate the funding mix
- Wells Fargo is the lowest-multiple bank in the lobbying coalition (12.8x trailing earnings vs. 14.5x sector median), giving it the most upside if the bank-favored CLARITY outcome lands
- Community-bank-style deposit franchise (the Wells Fargo branch network is heavily Main Street) makes it a direct beneficiary of the ICBA deposit-flight argument winning in senators' home states
- TTM revenue $81.7B with quarterly revenue growth +15.5% YoY in Q2 2026; deposit base concentrated in Services (TTS) and USPB segments
- Citigroup trades at 14.7x trailing earnings with the lowest price-to-book (1.2x) of the bank cohort — binary upside if CLARITY hard-bans yield, but exposed if the global Citigroup correspondent network becomes a stablecoin on-ramp
- Watch Oct. 2026 earnings (post-vote) for management commentary on deposit beta vs. stablecoin competition — that call will set the tone for 2027 NIM guidance