
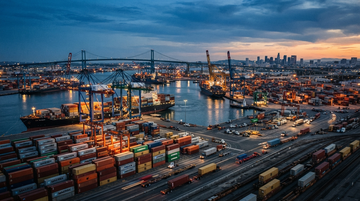
Port of LA 3-month TEUs (Jun–Aug 2026)
2.9M+
Busiest three consecutive months in Port history, per Port of LA release Sept 9, 2026
Port of LA August 2026
955,907 TEUs
Loaded imports 500,302 TEUs; exports 115,561 (-9% YoY)
Port of LA June 2026
1,002,734 TEUs
Busiest June ever; only third month in port history over 1M
U.S. container imports forecast July 2026
2.47M TEU
All-time monthly record, NRF/Hackett Global Port Tracker, Jul 8, 2026
U.S. diesel retail price Sept 4, 2026
$5.85/gal
Record high; $2+ above pre-Iran-war level
FedEx Ground fuel surcharge Aug 21, 2026
41.50%
Up from 26.5% in April; per FedEx weekly surcharge table
U.S. goods trade deficit July 2026
$119.6B
Goods-only; up $17.6B from June, BEA/Census release Sept 3, 2026
On September 9, 2026, the Port of Los Angeles reported 955,907 twenty-foot equivalent units (TEUs) moved in August, taking the June–July–August total above 2.9 million TEUs — the busiest three consecutive months in the port's 117-year history. Reuters framed it as 'early holiday import rush to avoid new tariffs, higher fuel costs,' and the framing is the entire story: this isn't an organic demand spike, it's a one-time arbitrage window between two clocks — a tariff calendar and a fuel-cost curve — and both are about to turn against the same companies that benefited.
The Tariff Clock
Why the surge happened: the 10% Section 122 expired on July 24, and a heavier round replaced it
Importers raced the calendar. A temporary 10% global tariff under Section 122 took effect in February 2026 and was scheduled to expire on July 24; it was replaced by reciprocal duties of 10% to 12.5% on goods from 60 trading partners covering roughly 99.4% of U.S. import categories, plus sectoral tariffs (50% on steel, aluminum, autos) and forced-labor-related duties that began landing in August. NRF's Jonathan Gold, the trade's most quoted policy voice, said retailers 'stocked up as much as they can ahead of tariff increases,' with the July 2026 forecast at 2.47 million TEU — a new all-time monthly record. That record happened because the front-loading pulled future volumes into the present, not because U.S. consumers bought more.
| Month | Forecast (M TEU) | YoY change |
|---|---|---|
| May 2026 (actual) | 2.24 | +14.9% |
| June 2026 (actual) | 2.33 | +18.7% |
| July 2026 (forecast) | 2.47 | +3.3% |
| August 2026 (forecast) | 2.22 | -4.5% |
| September 2026 (forecast) | 1.99 | -5.7% |
| October 2026 (forecast) | 1.99 | -3.8% |
| November 2026 (forecast) | 1.92 | -5.2% |
The Fuel Clock
The Iran war pushed diesel to a record $5.85/gallon — and made the arbitrage more expensive to ship
The fuel clock layered onto the tariff clock. The U.S.–Iran war drove diesel to an all-time national average of $5.85/gallon by September 4, 2026, with jet fuel in North America up roughly 95% since the war began, per Al Jazeera and NYT reporting. Two states now average over $7/gallon diesel. For importers, this meant the cost of pulling Q4 inventory forward into Q2/Q3 was rising as fast as the tariff savings: peak-season surcharges of $200–$800 per FEU on east-west lanes compounded with ground fuel surcharges that FedEx raised from 26.5% in April to 41.50% on August 21 — a 56% jump in surcharge rate that flows directly to carrier revenue.
FedEx Ground fuel surcharge escalation, 2026
Weekly fuel surcharge per billable pound, per FedEx public surcharge table
Unit: %
Apr 6, 2026
26.5
Aug 21, 2026
41.5
Who Catches the Arbitrage
Retailers booked the gains; freight carriers booked the volume
The arbitrage had two layers of winners. Layer one is the retailers who already had inventory in transit: they locked in pre-tariff prices and now sit on a Q4 cost-of-goods advantage. Layer two is the freight carriers who physically moved the surge. The two layers don't share the same calendar — retail gains show up in Q3/Q4 margins, freight gains in Q2/Q3 — and that's the asymmetry that drives the trade.
J.B. Hunt is the cleanest read on the front-loading: intermodal — rail-based long-haul that depends on West Coast import volumes — grew revenue 22% YoY with revenue per load up 11% and Eastern network loads up 16%, exactly the pattern when containers bound for inland distribution centers pour through the LA/Long Beach complex. FedEx called out that fuel surcharges alone contributed 5 percentage points of Q4 revenue growth — meaning roughly $1.25B of its $25.01B quarterly top line is pass-through fuel cost, not volume. United Parcel Service saw US SMB average daily volume grow 4.3% (now 34.5% of mix) even as International volume dropped 5.8% — the export side already feels the tariff drag.
- J.B. Hunt: Intermodal volumes +10%, revenue +22%, rev/load +11% — the clearest beneficiary of West Coast import surge
- United Parcel Service: US SMB ADV +4.3%, raised full-year revenue guide to ~$91.2B on the strength
- FedEx: 5pp of Q4 revenue growth came directly from fuel surcharge — a paper, not a volume, story
- Maersk Ocean: H1 revenue +6.9% YoY to $18.7B on Q2 rate spikes, but profit -12% as Gemini transition costs hit
- Hapag-Lloyd H1: Liner Shipping revenue $10.46B, swung from $256M loss to $83M profit quarter-on-quarter
Retail Winners
Walmart and Target captured pre-tariff inventory plus $3.9B in IEEPA refunds combined
The retailer layer is where the arbitrage converted into reported earnings. Walmart (Q2 FY27, reported August 20, 2026) collected nearly $2.9B in IEEPA tariff refunds — money it had already paid on imported goods that the Supreme Court's February 2026 ruling invalidated — and used a chunk of it to roll back prices on more than 11,000 items. Net sales grew 5.9%, adjusted operating income grew 17.4% in constant currency, and the company raised full-year FY27 guidance to 4.0–5.0% sales growth and 7.0–8.5% adjusted operating income growth.
Target (Q2 2026, reported August 19) was even more concentrated: $994 million of pre-tax tariff refund benefits in a single quarter, which added $1.65 to GAAP and adjusted EPS of $4.11 — the EPS doubled year-over-year, but ex-refunds it was a more modest +20%. Net sales rose 5.3%, comparable sales +3.8%, digital comp +8.7% led by >25% same-day delivery growth. The pattern: inventory imported before the August tariffs at lower cost lands now, while refund cash flows hit gross margin.
Trade-Balance and Dollar Implications
The 3-month surge front-loaded the deficit; the unwind is already in the July BEA data
The U.S. goods-and-services trade deficit widened to $88.6 billion in July 2026 — the largest gap since March 2025, per the BEA/Census September 3 release. Imports hit $399.3B (+2.8% MoM, +1.9% in the BEA measure), with capital goods imports jumping $14.4B to a record high and goods imports alone reaching $320.6B (+3.7%). The three-month moving average deficit climbed to $78.5B, up $11.9B. Year-to-date, the deficit is actually $188.4B smaller than 2025 — but that gap narrows every month the front-loading continues, and reverses the moment September imports fall 5.7% YoY as NRF forecasts.
- U.S. trade deficit July 2026: $88.6B total / $119.6B goods-only (largest goods gap since March 2025)
- Imports July 2026: $399.3B total / $320.6B goods; capital goods imports set a record at $14.4B above June
- 3-month moving-average deficit: $78.5B (up $11.9B from prior 3-month window)
- DXY (dollar index) is down as much as 7.31% since 'Liberation Day' tariffs, per NTU — a weaker dollar inflates the dollar-value of imports and partially explains why BEA import dollars grew faster than TEU volumes
The mechanical implication: the same trade-deficit print that signals 'import surge' today will invert into 'import collapse' prints starting with the September BEA release (early November). Analysts who anchor on the July surge to extrapolate freight demand, retail restocking, or dollar strength are reading a lagging indicator. The leading indicator — NRF's monthly tracker — already shows the cliff.
Horizons
Short-term: Q4 is the unwind. Long-term: the inventory math is broken for a year.
Days-to-quarters (Q4 2026 / Q1 2027): The NRF forecast takes U.S. container imports to 1.99M TEU in September (-5.7%), 1.99M in October (-13.2%), and 1.92M in November (-5.2%). For J.B. Hunt, that means intermodal volumes and revenue-per-load — both up double-digits now — face the toughest YoY comparison in the company's history through Q4. For United Parcel Service and FedEx, the fuel-surcharge revenue tailwind inverts: as diesel eases from its $5.85 peak (assuming the Iran ceasefire holds), surcharge revenue drops mechanically even if volumes hold. For ocean carriers Maersk and Hapag-Lloyd, Drewry's World Container Index at $4,465/40ft on September 3 has further to fall as transpacific volumes roll over — Hapag-Lloyd already reported a EUR 18M EBIT loss in its container shipping segment for H1.
One-to-three years (2027–2028): The structural damage is in retail inventory math. Goods imported before August's new 10–12.5% duty carry an indefinite cost advantage versus goods imported after. Retailers who loaded warehouses in June–August will price into Q4 2026 holiday and into 2027 to clear that inventory — which limits how fast they can pass tariff costs through to consumers, but also means replenishment in 2027 will hit higher-cost goods and compress gross margins. The IEEPA refund windfall is a one-time event; the replacement inventory cycle is a multi-quarter headwind. For carriers and ports, that argues for capacity rationalization rather than a return to 2022-vintage pricing. The base case is that 2027 U.S. container imports grow 0–2% — well below the 2.4–3.0M TEU monthly peak reached this summer.
Stocks to watch across the arbitrage chain
- Intermodal revenue +22% YoY in Q2 2026 captures the West Coast surge, but NRF's -13.2% October import forecast turns the comparison brutally tough in Q4
- Fuel-surcharge pass-through and rev/load at $3,034 (+11% YoY) protect margin even if volume rolls over 5–10%
- Long-term: rail-intermodal capacity additions by BNSF/UP through 2027 keep pricing competitive; structural growth intact but cyclical air-pocket coming
- Q2 2026 revenue +7.6% YoY with raised FY26 guide to ~$91.2B shows the parcel side still benefits from inventory build-and-ship
- International ADV -5.8% in Q2 is the early read on the export drag; US SMB ADV +4.3% is the offset
- Fuel-surcharge normalization in Q4 will mechanically reduce revenue per piece — a paper headwind even if package count holds
- 5pp of Q4 FY26 revenue growth came directly from fuel surcharges — that reverses when diesel eases from $5.85/gal
- Network 2.0 cost cuts and the FedEx Freight spin-off (FDXF) still anchor a multi-quarter margin story independent of fuel
- Ground volume likely follows the same Sep–Oct import cliff as JBHT intermodal, with a one-quarter lag
- $2.9B IEEPA tariff refund plus 11,000+ rollbacks in Q2 FY27 funds a sustained price-investment moat into holiday 2026
- Q2 FY27 net sales +5.9% and operating income +17.4% cc shows the inventory advantage is converting to comp growth
- Long-term: pre-tariff inventory carries into 2027 replenishment cycle, deferring gross-margin compression by 2–3 quarters vs. peers who waited
- $994M pretax tariff refund benefit in Q2 2026 ($1.65 EPS contribution) is the cleanest one-quarter windfall in retail
- Digital comp +8.7% and >25% same-day delivery growth show the channel is converting front-loaded inventory to traffic
- Q3 EPS guide to $8.25–$9.25 (raised from $4.11 base) bakes in continued refund tail; replenishment cost is the Q1 2027 risk
- H1 2026 Ocean revenue +6.9% YoY on Q2 rate spikes, but profit -12% as Gemini transition costs hit — a margin warning
- Drewry WCI at $4,465/40ft on Sept 3, 2026 has further to fall as transpacific volumes roll over in Q4
- Long-term: 2027 contract negotiations will reset rates 15–25% lower if Iran-driven fuel spike normalizes
- H1 2026 Liner Shipping revenue $10.46B (Liner), but EBIT loss of EUR 18M in container shipping segment shows pricing barely covers cost
- Hapag-Lloyd's Gemini alliance with Maersk is a cost-side offset, not a revenue story — the unwind cuts both ways
- Front-loading has pulled Q1 2027 demand forward into Q3 2026; the H1/H2 split is going to print an ugly H2
- Iran-war diesel at $5.85/gal national average lifts U.S. refining margins — XOM's 500+ U.S. retail and refining sites capture pass-through
- Jet fuel in North America up ~95% since Iran war began benefits XOM's aviation fuel mix at the wholesale level
- Long-term: any ceasefire drops diesel back toward $3.50/gal; trade is the volatility, not the trend