
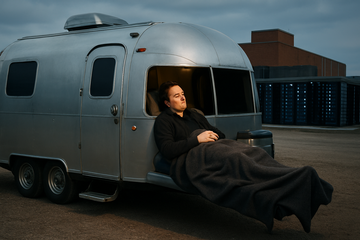
The image is the story: at the All-In Summit on September 15, 2026, Musk joined remotely from \"the palace that I live in in Memphis, which is an Airstream trailer,\" per a clip posted by Sawyer Merritt. The substantive line came right after — that he is personally embedded at the site to push what he called xAI's \"biggest expansion yet.\" It echoes the 2017–2018 Model 3 factory-floor routine that investors learned to read as a signal that the company was past the point of optionality. The trailer move says the same thing about Nvidia Blackwell allocations, Tesla Megapacks, and the gas turbines powering Memphis: this is critical-path work, not optional capex.
Signal
The Trailer Is the Tell — Musk Only Sleeps on Site When the Schedule Is
Musk has used the same physical cue twice in his career: during Model 3 production hell at the Fremont factory in 2017–2018, and now at xAI's Memphis campus. The pattern matters because the buildout under his trailer is not a single building but a four-site cluster that spans Tennessee and Mississippi.
- SpaceX-owned xAI is operating Colossus 1 (former Electrolux plant, South Memphis), Colossus 2 / \"Macrohard\" at 5420 Tulane Road in Whitehaven, Memphis, a new \"Macrohardrr / Colossus 3\" in Southaven, Mississippi, and \"Minihard\" — a fourth site Musk confirmed in late July 2026.
- Colossus 1 came up with ~100,000 H100 GPUs in 122 days and was doubled to ~200,000 GPUs in another 92 days, per the company's own timeline.
- Colossus 2 came online in January 2026 with 110,000 GB200-class GPUs at 210 MW, then added GB300-class clusters through mid-2026.
- The Southaven \"Macrohardrr\" site is being built to roughly 2 gigawatts of total cluster capacity on a corporate investment of \"exceeding $20 billion,\" per Mississippi state filings.
Scale
What 'Biggest Expansion Yet' Actually Means in Megawatts and GPUs
Cluster GPU count (target)
~555,000
Across Colossus 1, 2, Macrohardrr and Minihard, vs. ~200k at Colossus 1 alone in early 2025
Cluster IT power (target)
~2 GW
Roughly double the ~1 GW reached in mid-2026, per state filings
Southaven (Macrohardrr) capex
$20B+
Corporate investment, per Mississippi governor's office, Jan 2026
On-site generation
69 gas turbines
Counted by Mississippi regulators in July 2026; up from 27 at lawsuit filing
Musk personal net worth
$917B
Bloomberg estimate cited alongside the Airstream story, Sep 15, 2026
Two things make this expansion categorically different from the original Colossus build. First, power: at ~2 GW of IT load, the cluster consumes the equivalent of two large nuclear reactors — and because the Tennessee Valley Authority grid could not deliver that fast enough, xAI bought35 used GE LM6000-class turbines off eBay, ran them without air permits, and now faces NAACP and SELC lawsuits plus an EPA enforcement posture. Second, customer mix: the original Colossus was built to train Grok; Colossus 1 is now fully leased to Amazon-backed Anthropic for Claude inference, and SpaceX has signed Alphabet to a 32-month,110,000-GPU agreement starting October 2026.
Revenue
Who's Actually Paying for the New Buildout
| Tenant | Facility | Headline terms | Annualized run-rate | Source |
|---|---|---|---|---|
| Anthropic | Colossus 1 (South Memphis) | ~220k GPUs, lease through 2029 | $15.0B / year | CNBC, May 6, 2026; Anthropic press release, May 6, 2026 |
| Alphabet / Google | Unspecified SpaceX site | 110,000 GPUs, Oct 2026 – Jun 2029 (32 months) | $11.0B / year | CNBC, Jun 5, 2026 |
| SpaceX internal / Grok | Colossus 2 / Macrohard | GB200 + GB300 training clusters | n/a (internal) | Wikipedia / x.ai, mid-2026 |
Stacked together, the Anthropic and Google contracts alone generate roughly $26B of annualized revenue for the SpaceX compute business — before a single Grok training run is booked. That revenue line is the single biggest reason Musk can absorb capex of this scale without diluting outside shareholders, and it is also why a project that lost an estimated $5B in 2025 now shows up as a $26B-a-year gross-revenue line item in 2027 and 2028.
Supply chain
The Supply Chain Winners, From Silicon to Substations
Every layer of the Memphis build maps cleanly onto a U.S.-listed supplier. At the chip layer, NVIDIA reported $89.0B of data-center revenue in Q2 FY2027 (ended July 26, 2026), up 117% year-over-year, and guided Q3 to $108B with the next-generation Vera Rubin platform already contributing ~20% of data-center revenue. At the rack level, Super Micro Computer has confirmed it is building the Texas gigawatt-scale site that mirrors the Memphis playbook; Super Micro's server systems are the literal enclosure for those555,000 GPUs.
- TSMC fabricates every Blackwell GPU in the cluster on its 4NP process — a single supplier bottleneck on the most-allocated product in semis.
- Tesla' energy-storage arm has quietly become xAI's battery vendor of choice: 168 Megapacks at Colossus, with SpaceX spending $295M on Megapacks in Q2 2026 alone and $329M year-to-date through August.
- Intel joined Musk's \"Terafab\" project on April 7, 2026, committing its 14A node — the first big external foundry customer for Intel's leading-edge process and a direct route for Tesla / xAI / SpaceX to internalize custom AI silicon.
- GE Vernova is the most likely OEM for the next wave of turbine capacity, after xAI exhausted the used GE LM6000-class fleet that it assembled from eBay in 2024–2025.
- Constellation Energy and Vistra remain the marginal-priced power suppliers in PJM and ERCOT, and the cluster's eventual 2-GW firm-power contract is the trophy deal both have been positioning for.
- Schneider Electric and Equinix are exposed only indirectly, but both sell into the same hyperscaler capex wave that SpaceX is now the most aggressive single buyer in.
Nvidia quarterly data-center revenue, $B
Trailing twelve months through Q2 FY2027; the Memphis buildout alone consumes a measurable slice of this run-rate.
Unit: $B
Q3 FY26
41.1
Q4 FY26
75.4
Q1 FY27
75.2
Q2 FY27
89
Friction
The Backlash Musk Is Sleeping Next To
Memphis is not just a build site — it is the most contested AI-infrastructure site in the United States. As of July 2026, Mississippi regulators counted 69 temporary gas turbines at the Southaven site alone, more than double the 27 turbines xAI had acknowledged when the NAACP and SELC filed their Clean Air Act notice of intent to sue in February 2026. Reuters reported in July that the turbines' pollution falls disproportionately on historically Black neighborhoods, and an SELC study in February 2026 estimated the proposed gas plant could cause millions of dollars in annual health damages across the region.
- EPA confirmed in January 2026 that temporary methane turbines of xAI's scale require Title V air permits — a ruling that retroactively made every turbine operating without one a Clean Air Act violation.
- Earthjustice filed suit on behalf of the NAACP in May 2026 asking for emergency relief; the case is unresolved.
- Per local reporting, xAI has begun removing some turbines while adding others — net additions are still positive into September 2026.
- Two Shelby County lawsuits and a state-level environmental review remain open as of the September 15 trailer announcement.
Horizons
What Moves First, and What Compounds for Three Years
Short-term (days to quarters): the catalysts investors should track are not earnings dates but operational ones. (i) The October 2026 start date of the Google compute contract — SpaceX has a one-month grace period to deliver the 110,000 GPUs before Alphabet can terminate for non-performance. (ii) Any movement in the SELC / NAACP litigation, which could idle part of the turbine fleet and cap Memphis capacity. (iii) Nvidia's Q3 FY2027 print in late November, which is the cleanest read on whether Blackwell and Vera Rubin allocations are still going to a handful of anchor customers like SpaceX.
Long-term (one to three years): the structural question is whether the SpaceX compute business becomes a permanent, separately financeable utility — akin to a merchant power plant — or whether it stays an internal Musk asset that subsidizes Grok training. The Intel 14A Terafab deal and the planned Texas gigawatt-scale site with Super Micro both point to internal silicon and internal supply, which compresses supplier margins over time. The bull case for Nvidia is that even with internal silicon at Terafab, Musk still buys every leading-edge Blackwell generation externally for the next two cycles; the bear case is that the relationship becomes more arm's-length as SpaceX builds its own.
How the Airstream Memo Hits Listed Stocks
- Q3 FY2027 guide of $108B (+/-2%) effectively bakes in continued SpaceX-scale anchor orders; Vera Rubin already ~20% of data-center revenue.
- Single-supplier exposure to every GPU in the ~555,000-Memphis cluster and the planned Texas build means pricing power holds even as internal silicon grows at Terafab.
- Risk: any forced turbine shutdown in Memphis compresses the very demand SpaceX is funding through Anthropic and Alphabet.
- $920M/month contract locks in ~$29.4B of capacity cost through Jun 2029, raising Google's all-in AI capex versus in-house TPU build-out.
- Termination clause kicks in Sep 30, 2026 if SpaceX misses the 110,000-GPU delivery — a near-term binary on whether the Memphis fleet is operational.
- Strategic read: Google is now both buyer and competitor to the same merchant-compute stack; the $11B/yr is the price of keeping its model API in the race.
- Megapack revenue accelerates as SpaceX bought $329M of Megapacks year-to-date and $295M in Q2 alone; Megapack is now the fastest-growing, most-profitable Tesla segment.
- Tesla invested $2B into xAI in January 2026 — that capital is being deployed at the same site the trailer is parked at, compounding captive demand for Tesla storage.
- Long-term: if Terafab moves into volume on Intel 14A, Tesla's own Dojo/AI silicon line and Megapack business merge into a single internal Musk stack.
- 14A Terafab deal (Apr 7, 2026) is the first marquee external customer for Intel's leading-edge node since the foundry strategy launched.
- Tesla Q1 2026 earnings call confirmed 14A is the chosen process, locking in 2027–2028 wafer demand at scale.
- Margin upside depends on yield ramp; risk is execution, not demand.
- Every Blackwell and Vera Rubin GPU in the Memphis cluster — and at the planned Texas gigawatt site — is fabricated on TSMC's 4NP node.
- Vera Rubin ramp into Q3 FY2027 confirms TSMC is still the sole-source supplier even as Intel14A comes online for Musk's internal silicon.
- Capacity-tightness risk if Vera Rubin allocation expands faster than TSMC's CoWoS-L advanced-packaging output.
- Confirmed rack-scale integrator on the new Texas gigawatt SpaceXAI site that mirrors the Memphis playbook.
- Every Nvidia GB300 / Vera Rubin shipment at scale requires Super Micro liquid-cooled rack systems; backlog visibility extends through 2027.
- Risk: financial-reporting overhang and prior audit issues remain a discount factor even when volumes are real.
- xAI already exhausted the used GE LM6000-class fleet sourced from eBay; next-wave capacity must come from GE Vernova new-build units.
- A 2-GW firm-power expansion across the Memphis cluster is a multi-billion-dollar turbine order pipeline for GEV.
- Catalyst: any new permit-driven turbine order is a near-term revenue event for GEV's gas-power segment.
- Anthropic — Amazon's largest AI investment — is the largest single tenant of Colossus 1 at ~$15B annualized through 2029.
- Concentration risk: Anthropic's frontier-model inference now sits partly on a competitor's (SpaceX-owned) data-center fleet rather than AWS.
- AWS's own 1 GW + 5 GW compute agreements with Anthropic (May 2026) leave AWS as both supplier and indirect subletter through Anthropic.