
UNSC briefing date
Sept. 23, 2026
Wednesday session, AI on the agenda; France holds the September Council presidency
H200 chips to China shipped
~0
Commerce official confirmed, Jul 14, 2026; US cleared licenses to ~10 buyers, deliveries blocked
Ascend 950 chips DeepSeek wanted
200,000
Huawei supplied only 16,000 — per Liang Wenfeng investor call, July 2026
Cambricon H1 2026 revenue
RMB 5.996B
+108% YoY; Q1 net profit already exceeded full-year 2025
SMIC Q2 2026 revenue
$3.01B
+36.1% YoY; foundry raising prices as AI demand tightens capacity
The event
DeepSeek lands inside the most powerful UN chamber, alongside Altman and Anthropic
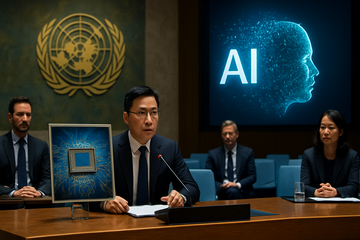
[DeepSeek] will brief the 15-member UN Security Council on Wednesday, September 23, on the risks posed by artificial intelligence, according to two diplomatic sources briefed on the meeting. [OpenAI] chief executive Sam Altman will brief the same session in person; diplomats also expect senior representatives of [Anthropic], and the Chinese AI developer Moonshot has been invited to address the chamber. France, the September Council president, called the high-level meeting to coincide with the UN General Assembly's leader week in New York.
DeepSeek founder Liang Wenfeng does not plan to attend in person, the sources cautioned, with plans described as fluid. That detail matters: Beijing is letting a Chinese frontier lab speak inside the Council's main chamber on the same platform as the CEO of the world's most valuable private AI company, but it is not elevating Liang to the lectern. The signal is institutional, not personal.
Geopolitical signal
Why a Chinese AI lab, why now — Beijing's 13-point governance plan is going multilateral
The briefing is the first test of the governance template Premier Li Qiang laid out at the 2025 World AI Conference: a 13-point Global AI Governance Action Plan built around equal participation, capacity-building for the Global South, and a UN-anchored multilateral body — explicitly positioned as a counterweight to the America-first Trump AI Action Plan. Beijing's framing calls any slowdown or frontier-control push a 'Cold War playbook' aimed at preserving US dominance and excluding China from the global AI governance system.
DeepSeek is the right messenger for that template. The lab's open-weight releases reset the cost-to-capability conversation globally, and its willingness to optimize models for domestic Huawei silicon gave China its first credible claim that frontier performance does not require US chips. Briefing the Council gives Beijing a venue where its standard — equal voice, no export-control linkage, no pre-approval from Washington — can be argued before the five veto-holding members, all15 elected members, and the wider UN membership watching.
- China's 13-point plan calls for a UN-anchored, multilateral AI body and equal participation — directly competing with US-led initiatives
- [Moonshot]'s July 2026 release of the open-weight Kimi K3 model (2.8T parameters) gives Beijing a frontier-capability proof point to pair with the governance pitch
- Anthropic's Sept. 10, 2026 threat intelligence report — covering cyber, biological, and distillation misuse — gives Washington the narrative anchor for the same session
- China's permanent Council seat makes any AI risk resolution veto-eligible, giving Beijing structural leverage over what an AI 'framework' actually says
The bottleneck
The chip gap that won't close: Liang's 200,000 chips versus the 16,000 Huawei sent
The briefing would land differently if DeepSeek were not, by its own founder's admission, hardware-starved. In a July 2026 investor call later leaked to Western media, Liang Wenfeng said DeepSeek required 200,000 Huawei Ascend 950 chips to train a frontier model, but Huawei had allocated only 16,000. He estimated Huawei's total annual capacity at roughly 750,000 Ascend 950 chips — a number that has to be split across every Chinese AI lab — and called the resulting shortfall 'currently basically unsolvable' for at least three years.
That confession reframes everything around the UNSC seat. DeepSeek is briefing the world's security chiefs on AI risk not from a position of strength but from a position of structural bottleneck — and is using that platform to argue for a governance framework where the constraint is recognized rather than punished. The lab's response has been to push the architecture of compute around the shortage: post-training a 1.6T-parameter model on just 1,000 Huawei Ascend chips, then in September 2026 announcing plans for a cluster of roughly 160,000 Huawei accelerators for a new data center — a build-out priced at an estimated $2.56 billion in hardware alone.
Chinese AI compute: demand versus domestic supply, 2026
Huawei Ascend 950 allocations vs. disclosed Chinese frontier-lab requirements
Unit: chips (thousands)
DeepSeek ask (per Liang Wenfeng)
200
Huawei total Ascend 950 capacity (year)
750
DeepSeek received
16
DeepSeek cluster plan (Sep 2026)
160
The trade lever
The H200 stalemate Trump's chip diplomacy couldn't unstick
The chip story behind the briefing is a year-long standoff. In December 2025, President Trump signaled NVIDIA could sell H200 chips to China, with the US government taking a 25% cut; by January 2026, the Commerce Department issued licenses to roughly ten Chinese firms including Alibaba, Tencent and ByteDance, plus distributors [Lenovo] and [Foxconn Hon Hai]. In March2026, Chinese authorities approved the import of an initial batch. Then, deliveries stalled — and a top US Commerce official confirmed in July 2026 that 'very few' H200 chips had actually reached China or Hong Kong.
Beijing has not stopped its cloud firms at the border — it has steered them away from US silicon at home. Chinese regulators reportedly pressed Alibaba, Tencent and ByteDance to slow or suspend H200 and predecessor H20 purchases on national-security grounds, the same playbook used in 2025. The message: Beijing will let US firms hold licenses, will let Washington claim a25% revenue cut, but will not let H200 silicon actually train Chinese frontier models. That asymmetry is the political backdrop to DeepSeek speaking at the Council this week.
Supply chain rerating
The China compute stack is the biggest winner — NVIDIA, TSMC and Micron read it differently
The rerating is already in the numbers. SMIC, China's largest foundry, reported Q2 2026 revenue of $3.01 billion, up 36.1% year-over-year and 20% sequentially, with gross margins expanding on price increases as AI demand tightens 7nm-class capacity that produces both Huawei Ascend 910B/910C and the Kirin mobile line. Cambricon, China's most visible domestic AI accelerator designer, posted first-half 2026 revenue of RMB 5.996 billion, up 108% year-over-year, with Q1 alone (RMB 2.88 billion) exceeding all of 2024 — though its Q2 sequential growth slowed to roughly 8% as HBM shortages and wafer constraints began to bite.
On the US side, the Q2 FY2027 print tells the other half of the story. NVIDIA reported revenue of $96.2 billion, up 106% year-over-year, with Data Center revenue of $89.0 billion (+117% YoY) and a 75% gross margin. That growth is now decoupled from China. The company explicitly excludes any China data-center contribution from its forward outlook — effectively conceding the China training market to domestic silicon and reserving H200-class business for inference and licensed-but-undelivered optionality.
| Company | Symbol | Latest reported revenue | Year/year growth | China exposure |
|---|---|---|---|---|
| NVIDIA Corp. | NVDA | $96.2B (Q2 FY2027) | +106% | Excluded from forward outlook |
| Taiwan Semiconductor | TSM | $4.44T NTD TTM | +36% (Q2 YoY USD-equiv.) | Foundry for non-China AI accelerators |
| Micron Technology | MU | $90.3B (TTM) | +57% YoY | HBM3E/HBM4 supply to NVIDIA/AMD |
| Cambricon Technologies | 688256.shh | RMB 5.996B (H1 2026) | +108% | Pure-play China AI accelerator |
| SMIC | SMICY | $3.01B (Q2 2026) | +36.1% | Foundry for Huawei Ascend |
IPO math
DeepSeek at the Council forces a fresh read on Anthropic's $2 trillion and OpenAI's $1 trillion
Anthropic's IPO math is the cleanest test. The company filed confidentially in June 2026 and is targeting a near-$2 trillion listing, anchored by a May 2026 Series H that valued the company at $965 billion post-money. Anthropic's annualized revenue run rate hit $65 billion at the end of July 2026, up from $47 billion in May and roughly $9 billion at year-end 2025. The Sept. 10 threat intelligence report — covering cyber, biological, distillation and surveillance misuse — is the kind of disclosure that justifies the safety premium inside that valuation.
But the DeepSeek seat at the Council cuts both ways. A Chinese lab that can publicly argue its model is safe enough to brief the Security Council on risk makes the 'frontier safety is only a US problem' narrative harder to monetize at the top of the IPO range. OpenAI is the most direct counterweight: targeting a $1 trillion+ listing in 2027, with annualized revenue above $40 billion in July 2026 and a confidential S-1 already filed. Both IPOs are now being priced against a world in which the safety story has a Chinese co-author.
The market for talent and capital is also tightening. Alibaba and Tencent — among the ten Chinese firms cleared by Washington for H200 imports — are being told by Beijing to slow US chip purchases while domestic labs consume every Ascend wafer SMIC can produce. That capital redirection flows into Cambricon-class accelerators and into the open-weight models DeepSeek and Moonshot distribute for free, which collectively compress the dollar revenue US frontier labs can extract from China-adjacent developers and enterprises.
What to watch
Short-term and long-term: the catalysts that actually move the chips
Short-term (days to quarters). The Council meeting itself is the near-term catalyst. Watch (i) whether China's ambassador to the UN attaches political conditions — for example, tying any Council endorsement of frontier risk management to a moratorium on new chip export controls, (ii) whether DeepSeek issues a written statement and whether that statement cites the 13-point plan, and (iii) any readout from the Trump-Xi summit later this week on whether chip terms moved. NVIDIA's next earnings cycle (Q3 FY2027, reported late November 2026) will quantify whether any H200 deliveries actually occurred.
Long-term (one to three years). The structural question is whether China can scale Huawei Ascend 950 production past Liang Wenfeng's 750,000-unit ceiling. If yes, the H200 stalemate becomes permanent and SMIC/Cambricon compound. If no, Beijing's leverage at the Council comes at the cost of a permanent compute-capability gap that keeps US frontier labs (and their IPO math) intact. The MIT-like independent AI scientific panel the UN launched in August 2025 is the institutional vessel both sides will use to argue the safety and capability case — and DeepSeek's seat at the Council this week is its first big test.
- NVIDIA Q3 FY2027 print (reported late Nov 2026) is the first hard data point on whether the H200 stalemate is breaking
- SMIC and Cambricon margin expansion in Q3 2026 will show whether China compute demand is being met by domestic supply — or only rationed
- Anthropic S-1 public filing (likely Oct/Nov 2026) is the test of whether the $2T target survives DeepSeek's UNSC appearance
- Any Council resolution language on frontier AI risk becomes a template for export-control fights at the Trump-Xi summit and beyond
Stocks to position around this event
- Data Center revenue of $89B in Q2 FY2027 shows the H200 China stalemate has not hurt the print yet — but China DC is excluded from forward outlook, capping optionality
- H200 deliveries stuck near zero after a year of approvals means the China upside is a paper option thatgets repriced every quarter it isn't converted
- A breakthrough at the Trump-Xi summit or a US-China AI dialogue would re-open the China training market; absent that, the $89B Data Center line must keep running on US hyperscaler demand alone
- H1 2026 revenue of RMB 5.996B (+108% YoY) reflects the first wave of Huawei-Ascend-substitute demand — and DeepSeek's UNSC seat cements that policy direction
- Q2 sequential growth slowed to ~8% on HBM and TSMC-equivalent wafer constraints, so the next leg depends on SMIC 7nm capacity — not on policy
- Liang Wenfeng's 200,000-versus-16,000 disclosure confirms structural demand for at least a decade of domestic accelerator build-out
- Q2 2026 revenue of $3.01B (+36.1% YoY) and rising wafer prices prove SMIC has pricing power on the 7nm Huawei Ascend line — a position it has not had in a decade
- Foundry allocation is the binding constraint on every Chinese frontier lab's training roadmap, so SMIC revenue scales with policy intent, not with end-demand cycles
- Pilot runs on a 5nm-class node in 2026 add a second vector if Trump's export-control regime loosens further — without that, the 7nm Ascend line is the anchor
- Approved by Washington for H200 imports, but Beijing has reportedly pressed Alibaba and peers to slow US silicon purchases — that contradiction caps Alibaba's near-term AI capex efficiency
- Alibaba Cloud's domestic stack increasingly uses Huawei Ascend and Cambricon accelerators, which reruns AI gross margin economics through a Chinese supply chain
- An H200 delivery breakthrough — even a small one — would re-rate Alibaba Cloud's training-side competitive position versus US hyperscalers
- Among the ~10 H200 licensees but among the firms Beijing has reportedly pressed to slow US silicon purchases — same contradiction as Alibaba
- Tencent's domestic AI training roadmap is increasingly tied to Huawei Ascend 910C/950 and to Cambricon-class accelerators, making it a derivative play on Chinese foundry capacity
- WeChat and gaming-adjacent AI workloads favor inference silicon, where H200 and Ascend economics differ materially — so any H200 delivery breakthrough is a one-line upside
- TSM is the foundry for the H200, Blackwell and Rubin generations feeding NVIDIA — China compute displacement does not directly hit TSM revenue, but it does cap the addressable market at US hyperscaler demand
- The May 2026 Trump-Xi summit explicitly avoided chip export controls — a signal that future US-China deals could re-route advanced packaging to China under license, a watch item for TSM capacity allocation
- OpenAI's $1T+ IPO and Anthropic's $2T target both run on TSM-fabricated silicon, so TSM revenue is the cleanest read on US frontier AI capex
- HBM3E and HBM4 supply to NVIDIA and AMD puts Micron on the wrong side of the US-China split — but on the right side of every US frontier-lab training run, including the ones that displace DeepSeek's
- Cambricon's H1 2026 report flagged HBM shortages as a constraint — that bottleneckcompounds Micron's pricing power on HBM4 through 2027
- Micron is not exposed to China DC chip sales, so any Trump-Xi deal that reopens them is upside; the base case is unchanged