
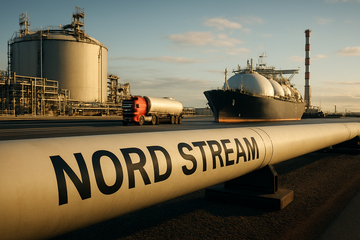
Nord Stream status
Exploratory talks
Oct. 8, 2026; no agreement or named U.S. investor disclosed
Russian gas still reaching the EU
35 bcm/year
European Commission estimate; 12% of overall imports in 2025
Long-term Russian LNG
Ban Jan. 1, 2027
Regulation (EU) 2026/261; pipeline gas by Sep. 30, 2027
The verified fact
The Headline Is a Russian Pipeline Story, Not a U.S.-LNG Sale
Reuters' Oct. 8 report described exploratory discussions involving Jared Kushner and Putin adviser Kirill Dmitriev. The asset was Nord Stream, the Russian pipeline company whose gas historically supplied Germany; a separate discussion concerned Lukoil assets and the U.S. DFC. The reported discussion changes the investable question from displacement to timing, because no named buyer, price, volume, restart date or waiver was disclosed.
- The potential flow would be Russian pipeline gas to Germany, not LNG liquefied in the United States.
- Reuters said a U.S. official said there had been no recent Nord Stream discussions and called a medium-term deal unlikely.
- Before the February 2022 invasion, Germany bought more than half its gas from Russia through the two lines; the pipelines were mothballed and then damaged in September 2022.
"Any restart illegal"
Because Nord Stream is sanctioned, damaged and politically opposed, the proposal remains an option rather than a forecastable cash flow. It does not yet cancel or reprice an operating U.S. LNG train. That is why the first-order market read keeps operating U.S. LNG cash flows outside the headline.
What Is Actually in the Chain
Asset
Nord Stream AG; Gazprom is the majority owner
Reuters identified two German holders and French and Dutch holders.
Political channel
Jared Kushner and Kirill Dmitriev
They met in Moscow and New York in recent weeks.
Separate discussion
Lukoil assets
The U.S. DFC and Qatari and Emirati investors were discussed; no agreement was disclosed.
Commercial LNG chain
[Cheniere Energy](lng); [Venture Global](vg); [Sempra](sre)
These companies are discussed as global LNG context, not as named Nord Stream investors.
The legal gates
Four Legal Gates Keep the Restart Out of Reach
Nord Stream is sanctioned by both the United States and European Union, according to Reuters; it cannot be restarted lawfully without changing those restrictions. The Reuters account describes a sanctions-waiver problem, not an agreed gas-price cap: no cap, license or purchase price was disclosed. The current legal position keeps the proposal outside commercial use.
| Gate | What is documented | What must change |
|---|---|---|
| U.S. sanctions | Reuters reported U.S. sanctions and said Trump could waive or soften them; congressional control after the November midterms could make that harder. | Sanctions relief is necessary before a restart. |
| EU law | Regulation (EU) 2026/261 ends long-term Russian LNG imports Jan. 1, 2027 and phases out pipeline gas by Sep. 30, 2027. | A U.S. waiver cannot legalize EU imports without an EU change. |
| Germany | A German ministry spokeswoman said Nord Stream and Russian gas are sanctioned, alternatives exist, and reopening is not desired; government approval is required. | German approval remains a separate gate. |
| Infrastructure | The Reuters report does not disclose a repair budget, capacity or timetable. | Physical restoration remains unpriced. |
The Commission describes limited emergency flexibility: origin proof can be suspended for up to four weeks during a gas-security alert, not for a standing sanctioned-pipeline exemption. Investors should therefore assign the restart an option value, not a base-case volume.
The demand mechanism
Europe's 35 bcm Phaseout Creates Replacement Demand
The European Commission estimates that 35 bcm of Russian gas still reaches the EU annually. Russia's share of overall imports fell from 45% to 12% in 2025, while spending on the remaining gas is about €10bn a year. The phaseout converts the loss of Russian supply into multi-year replacement demand for non-Russian suppliers.
Russia's Share of EU Gas Imports Has Already Fallen
European Commission estimates: 45% at the earlier dependency benchmark and 12% in 2025.
Unit: % of overall imports
Earlier dependency
Commission benchmark before the phaseout framework
45%
2025
Share of overall EU gas imports
12%
- RWE signed a 20-year, 1 mtpa LNG contract with Texas LNG, equivalent to about 1.4 bcm a year, with commissioning expected in 2030.
- Centrica signed a 10-year agreement with Devon Energy for 50,000 MMBtu a day starting in 2028, indexed to the European TTF hub.
- These offtake agreements put replacement demand beyond the immediate Nord Stream headline, because delivery begins in 2028–2030.
That transmission path is visible in contracts, not sentiment: RWE and Centrica sit downstream, while Texas LNG/Glenfarne and Devon Energy's U.S. gas supply sit upstream of their European portfolios. U.S. exporters such as Cheniere Energy and Venture Global occupy the liquefaction layer, converting gas into cargoes. The chain keeps U.S. LNG utilization in the replacement cycle until sanctions change.
The company read-through
U.S. LNG Fundamentals Are Already Moving
The October headline does not alter disclosed 2026 guidance for the listed companies in the supply chain. Cheniere Energy exported 672 TBtu in Q2 2026, versus 550 TBtu a year earlier, and raised full-year adjusted EBITDA guidance to $7.9–$8.4B. Venture Global reported 466.4 TBtu of LNG sold in Q2, while Sempra reported $762M of adjusted earnings and a $65B 2026–2030 capital plan. Those projects are not waiting for a Russia decision: Cheniere Energy's Train 7 is nearing completion and Venture Global's CP2 reached FID in March, so the committed capex path stays intact.
| Company | Q2 or first-half 2026 disclosure | What it means |
|---|---|---|
| Cheniere Energy | 672 TBtu exported; $7.9B–$8.4B FY2026 adjusted EBITDA guidance; Train 7 first LNG expected imminently. | Near-term execution is the driver, not a reported Nord Stream volume change. |
| Venture Global | $4.578B Q2 revenue; 466.4 TBtu LNG sold; $6.9B first-half capex; $8.6B CP2 project financing. | Expansion risk stays tied to commissioning and funding, not Russia headlines. |
| Sempra | $762M Q2 adjusted earnings; more than $6B first-half capital spending; $65B 2026–2030 plan; 95% allocated to Texas and California utilities. | Utility spending dilutes the headline's LNG sensitivity. |
| Devon Energy | 2,318 MMcf/d reported in its six-month gas-production mix; $3.674B Q2 operating cash flow. | The gas-supply contract is an outlet, not a liquefaction project. |
Cheniere Energy's near-term cash engine is Train 7 and guidance execution; Venture Global's is CP2 financing and commissioning; Sempra's is a broad utility plan; and Devon Energy's is its contracted gas supply. A Russian-pipeline headline can move sentiment, but it cannot become a revenue shock without a buyer, volume, contract and start date.
The counter-demand signal
QatarEnergy Adds a Separate Demand Bid
Reuters, in a report also summarized by Livemint, said on Sept. 11 that QatarEnergy was negotiating multi-year U.S. LNG contracts through 2031. Sources placed Venture Global and Cheniere Energy in those discussions, and Woodside was also named; no agreement was announced. The signal adds optionality without changing booked contracts.
| Market signal | What was reported | Investment interpretation |
|---|---|---|
| QatarEnergy procurement | Multi-year U.S. LNG talks through 2031 after damage to Qatari production assets. | A second demand source can absorb future liquefaction capacity. |
| Producer confirmation | Venture Global and Cheniere Energy declined comment; Woodside said it does not comment on speculation. | Treat the procurement story as an option, not backlog. |
| Nord Stream separation | No public evidence linked the Nord Stream discussion to QatarEnergy's procurement plan. | Do not combine political optionality with commercial bookings. |
- Near term: replacement demand can tighten global U.S. LNG sourcing even while European buyers avoid Russian gas.
- A binding QatarEnergy contract would improve utilization and financing visibility; no such contract was announced.
- Long term: a credible post-2027 Russian return could compete for buyer attention, but current EU law points toward non-Russian supply.
The two reports therefore point in opposite directions on different clocks: Nord Stream is a political option with no volume, while QatarEnergy is a commercial procurement campaign with no public term sheet. The contrast separates political optionality from commercial demand and argues against a blanket haircut to U.S. LNG capex.
The horizon
The Timing Runs From a Waiver to a Cargo
| Horizon | Base case | Catalysts and risks |
|---|---|---|
| Days–quarters | No binding sale, waiver or restart; equity response remains headline-driven while operating milestones dominate. | U.S. sanctions action, German coalition statements and EU implementation can move sentiment quickly. |
| 2026–2028 | Cheniere Energy expects Train 7 LNG imminently and substantial completion in fall 2026; Venture Global reached CP2 FID in March 2026. | Project delivery, financing and the EU's 2027 gas deadlines matter more than ownership speculation. |
| 1–3 years | RWE's 1 mtpa Texas LNG contract expects commissioning around 2030; Centrica's 50,000 MMBtu/day agreement starts in 2028. | War settlement, German politics, EU policy, insurance, repairs and Asian procurement determine the marginal supplier. |
- Days–quarters: until the legal gates move, the model's Nord Stream volume stays at zero.
- 1–3 years: track contracted offtake, not ownership headlines; disclosed delivery dates extend to 2028–2030.
- Main risk: a U.S. sanctions change does not guarantee EU access, so the upside case remains conditional.
Near-term investors should treat the headline as a tail-risk monitor, not an estimate change. Long-term investors should favor disclosed volumes, project financing and buyer contracts, while assigning no value to a restart until legal change and physical restoration are proven. That framework keeps U.S. LNG estimates tied to contracts and capacity.
The investable takeaway
The Thesis Is Contracts, Not Ownership Headlines
The verified fact is a discussion, not a deal. The structural driver is Europe's replacement of Russian gas; the company-level evidence is rising U.S. LNG output and long-dated offtake. That combination keeps U.S. LNG estimates tied to contracts and capacity, while making a Russian restart a low-probability policy option.
- Near term, Cheniere Energy and Venture Global retain structural demand; Sempra's utility plan dilutes the headline; Devon Energy has feedgas optionality rather than direct LNG exposure.
- Bull case for U.S. LNG: the EU phaseout and Asian replacement procurement fill capacity without requiring a Nord Stream restart.
- Bear case for U.S. LNG: U.S. sanctions relief and German policy jointly reopen Russian supply after the EU's 2027 deadlines.
Where the Disclosed Exposure Actually Sits
- The proposed restart does not remove 2026 U.S. LNG demand; Cheniere Energy exported 672 TBtu in Q2 and raised EBITDA guidance.
- The EU phaseout supports long-term contracting through 2027, but the cited disclosures did not quantify a European volume.
- Near term: Train 7 completion and guidance execution set the cash-flow path; no Nord Stream volume is disclosed.
- Reported QatarEnergy talks through 2031 add demand optionality for Venture Global, but no term sheet was announced.
- CP2's $8.6B financing and $6.9B first-half capex make execution the main near-term value driver, not Nord Stream.
- Long term: a credible post-2027 Russian return could weaken marginal contracting economics, while current EU law points toward non-Russian supply.
- Sempra's $65B 2026–2030 plan dilutes the headline's company-specific impact; 95% is allocated to Texas and California utilities.
- Sempra reported $762M adjusted earnings in Q2 and reaffirmed 2026 adjusted EPS guidance of $4.80–$5.30.
- Long term: Port Arthur LNG optionality benefits if non-Russian demand persists, while a sanctions reset creates the opposite risk.
- Centrica's 10-year agreement starting in 2028 for 50,000 MMBtu/day gives Devon Energy a contracted European-linked outlet.
- Devon Energy reported 2,318 MMcf/d in its six-month gas-production mix and provides feedstock scale but not LNG margin.
- Near term: the 10-Q disclosed no Europe-specific revenue, so avoids treating the Nord Stream story as a direct earnings catalyst.