
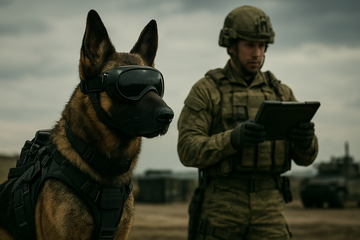
Unmanned ground meets cybernetic sensing
A $200M seed round turns working-dog logistics into a hardware-and-software procurement problem
Warhound—backed by a $200M seed—positions genetically enhanced military working dogs as a scalable platform for the U.S. military and law enforcement. A core claim in the public reporting is that Warhound will not just “make dogs,” but will also bundle Anduril sensing and protection into each fielded dog-and-handler team.
That matters because defense programs already wrestle with two costs that don’t show up cleanly in bid sheets: (1) fielding throughput (how quickly you can produce qualifying units) and (2) systems integration margin (how much “glue” value the prime can capture per unit shipped).
| Claim (public source wording) | What it implies for procurement economics | Primary source |
|---|---|---|
| Warhound “emerged from stealth with a 200 million seed round” | A venture-backed, unit-scaling business model is being pitched early | TMCnet, PRNewswire reprint (Oct. 22, 2026): https://www.tmcnet.com/usubmit/2026/10/22/10468835.htm |
| “all dogs will be equipped by Anduril's advanced cybernetic Augments, software, and battlefield situational awareness” | Anduril’s role shifts value from “program-only integration” toward reusable gear-and-software modules | TMCnet, PRNewswire reprint (Oct. 22, 2026): https://www.tmcnet.com/usubmit/2026/10/22/10468835.htm |
| Anduril “eye and ear protection and Eagle Eye technology” | Per-unit sensing/protection is framed as installable equipment on the platform | The Verge (Oct. 22, 2026): https://www.theverge.com/tech/1017343/warhound-palmer-luckey-anduril-colossal-war-dogs |
| Warhound aims to reduce reliance on European dog suppliers for military canines | It targets a supply bottleneck that historically behaves like a capacity constraint, not a one-time contracting issue | Yonhap (Oct. 23, 2026): https://www.yna.co.kr/view/AKR20261023115000009 |
Supply-chain map
The “unmanned stack” is being decomposed: biology + protection/sensing + handler software, instead of one monolith
A useful way to think about Warhound is as a supply-chain re-bundling.
Upstream: the platform starts with genetics/cloning capability (public reporting ties Warhound to Colossal Biosciences through its cofounder Ben Lamm). Middle: Anduril is described as supplying wearable protection and situational-awareness software (including “Eagle Eye” and “eye and ear protection”). Downstream: the end-user is a dog-and-handler team that can be deployed like a low-speed ground ISR/tactical assist asset.
The pivot is that Anduril’s public positioning treats sensing/protection as something you can attach to the platform per unit, not only something a prime can wrap into a bespoke system-of-systems package.
- Warhound targets a foreign-supply dependency (Europe-sourced dog supply), framing throughput as a solvable bottleneck (Yonhap, Oct. 23, 2026).
- Anduril’s described “cybernetic Augments” role implies a productized layer (Augments/software/situational awareness) rather than a pure integration service (PRNewswire reprint on TMCnet, Oct. 22, 2026).
- “Eagle Eye” and wearable “eye and ear protection” signals per-team sensing and protection hardware, enabling repeatable installation (The Verge, Oct. 22, 2026).
- The Pentagon’s buyer behavior (implied by the direction of funding and partnerships) shifts toward paying for attachable capability on a cheap ground platform, not paying only for prime-delivered integration.
Margin model tension
Why this can compress prime “software-and-integration” margin—without changing the prime’s role in the long run
Defense primes traditionally make money in three ways: (1) high-fixed-cost prime engineering, (2) program integration (wiring disparate components), and (3) sustainment. If a procurement model starts paying for a unitized sensing/protection layer from a smaller specialist, the integration work moves downstream into shorter, more repeatable tasks.
In that environment, primes can still win—through program management, safety certification, logistics integration, and platform-level autonomy safety—but the “take rate” per unit can decline if the cheapest capability is coming from modular hardware/software layers that are easier to scale.
| Prime financial baseline (recent filing) | Why investors should care for integration margin | Primary source |
|---|---|---|
| Lockheed Martin 2025 operating income: $7,731 million; revenue: $75,048 million | Large, diversified engineering base can absorb margin pressure, but modular competition can still affect incremental bids and program mix | Lockheed Martin 2025 10-K (filed Jan. 29, 2026): https://www.sec.gov/Archives/edgar/data/936468/000162828026004195/lmt-20251231.htm |
| RTX 2025 operating profit: $9,300 million; net sales: $88,603 million | Major air/space/defense software and sensing positioning means modular sensing competition can show up in customer allocation choices | RTX 2025 10-K (filed Feb. 6, 2026): https://www.sec.gov/Archives/edgar/data/101829/000010182926000006/rtx-20251231.htm |
| Northrop Grumman 2025 sales: $41,954 million; operating income: $4,511 million | Integration and mission engineering remain core; modular sensing/protection layers can reduce “bespoke glue” work per delivered unit | Northrop Grumman 2025 10-K (filed Jan. 27, 2026): https://www.sec.gov/Archives/edgar/data/1133421/000113342126000003/noc-20251231.htm |
| General Dynamics 2025 revenue: $52.6 billion; operating income: $5.356 billion | Ground/ISR adjacency means the platform economics matter, but the unit economics pressure can tilt budgets toward lower-cost platforms | General Dynamics 2025 10-K (filed Jan. 30, 2026): https://www.sec.gov/Archives/edgar/data/40533/000004053326000006/gd-20251231.htm |
| Leidos FY2025 revenue: $17,174 million; operating income: $2,109 million | If systems integration becomes more “componentized,” integrators that win logistics/mission tailoring may benefit even while pure integration margins face competition | Leidos FY2025 results in Form 10-K (filed Feb. 17, 2026): https://www.sec.gov/Archives/edgar/data/1336920/000133692026000030/ldos-20260102.htm |
Short-term / long-term horizons
What to watch next: contract signals, unit scaling, and whether modular sensing survives field conditions
- In the next quarters, watch for whether Warhound converts its “emerged from stealth” narrative into award headlines that include unit quantities (not just pilots).
- In the next 6–18 months, the critical technical-business gate is whether Anduril’s described “situational awareness” and wearable protection deliver repeatable performance under operational constraints (battery life, comms, handler workload).
- Over 1–3 years, the strategic bet is supply-chain substitution: whether Warhound reduces reliance on European dog suppliers as planned (Yonhap, Oct. 23, 2026).
- If those gates hold, the competitive model can spread: primes may respond by partnering deeper with modular suppliers, reducing the standalone value of full-stack integration bids.
A bearish risk case exists too: if modular wearable sensing/protection fails reliability targets, the procurement model can snap back toward monolithic prime delivery where primes bundle certification, training, and sustainment under one contract umbrella.
The article’s core thesis therefore stays conditional: Warhound is a plausible “end-of-the-unmanned-stack” unit-cost bet, but the market will ultimately price it on fielded unit throughput and measured operational effectiveness—not on seed-round ambition.
Investor takeaway
A new defense venture category is emerging: cheap, scalable ground “teams” with expensive sensing—where suppliers can win the attach rate
Warhound’s public story is a clean abstraction for investors in defense technology: build the platform (dogs) and attach sensing/protection software from a specialized supplier (Anduril). In that model, primes still matter, but the unit-by-unit value capture can migrate toward those who provide the attachable layer.
The most investable implication is not that robot dogs replace robots tomorrow; it’s that budgets may increasingly pay for per-unit capability modularity—a pattern that can influence which public defense technology suppliers are most insulated versus most exposed.
Listed defense names most exposed to integration-margin shifts if modular attach-rate grows
- Warhound-style attachable sensing can reduce incremental prime integration scope per unit, but Lockheed Martin should stay relevant via certification and sustainment baked into large programs.
- Lockheed Martin reported $7,731M operating income on $75,048M revenue in 2025, providing cash capacity to adapt contract strategy over 1–3 years.
- If modular suppliers win attach-rate, prime contract bids may shift toward higher-value program management and systems assurance rather than low-cost unit integration.
- A supplier-led attach model can pressure portions of software/integration margin, but it also increases demand for interoperable sensing standards primes can certify.
- RTX generated $9,300M operating profit on $88,603M net sales in 2025, suggesting near-term resilience if incremental bid mix shifts.
- If Eagle Eye–type capability becomes repeatable, investors should watch for RTX to repackage similar modular layers rather than only bundled program deliverables.
- If cheaper, scalable ground platforms expand, Northrop can face lower take-rate on “glue work” where attachable sensing moves to specialist layers.
- Northrop reported 2025 sales of $41,954M and operating income of $4,511M, so margin impacts can matter in quarters as program mix changes.
- The near-term catalyst to monitor is whether defense buyers fund pilots that explicitly separate platform procurement from sensing software modules.
- Cheap ground-team procurement can shift demand toward scalable platforms, which could re-balance contracts away from fully integrated stacks.
- General Dynamics reported 2025 revenue of $52.6B and operating income of $5.356B, implying some buffer while it adjusts partner strategy.
- A bullish offset is that vehicle, logistics, and tactical systems integration may still expand even if sensing becomes more modular.
- If sensing/protection becomes more componentized, mission-tailoring and operational integration services can grow, letting Leidos win integration that looks more like operations than “prime glue”.
- Leidos recorded FY2025 operating income of $2,109M on $17,174M revenue, supporting near-term investment into mission and data workflows.
- Watch whether defense buyers award programs that emphasize interoperability and handler training with modular sensing rather than monolithic deliverables.
- If the Pentagon extends a “low-cost platform + attachable intelligence” model from air/ISR to ground teams, AeroVironment could see demand spillover through payload-style interoperability over 1–3 years.
- AeroVironment reported fiscal 2026 revenue of ~$1,976.8M with operating loss of ~$311.0M, so investors should treat it as high-uncertainty until revenue improves.
- The key catalyst is whether future budgets explicitly fund ground-team equivalents to drone payload architectures with open interfaces.