
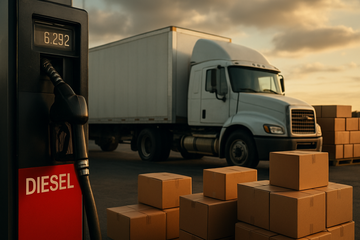
US on-highway diesel averaged $6.292 a gallon in the week of Nov 2, 2026, against $2.539 a year earlier. That $3.75 gap flows straight into the fuel surcharge line on every parcel, pallet and truckload, and into the price of a small merchant's last mile, while the demand side barely moves: Visa forecasts holiday retail sales up 4.5% in dollars but only 1.1% after inflation, with holiday goods prices up about 3.4%. This is a cost-push season, not a demand-led one, and the profit pool is migrating to whoever owns the fuel, the truck and the toll booth.
U.S. on-highway diesel, week of Nov 2, 2026
$6.292/gal
vs. $2.539 a year earlier — up 148%
Holiday spending, inflation-adjusted
+1.1%
Visa forecast, Nov 5, 2026; +4.5% in nominal dollars
Q4 2026 ground delivery pricing
+5.8%
Fourth-quarter forecast published Oct 26, 2026
Valero refining margin, Q3 2026
$39.24/bbl
vs. $13.14 a year earlier; refining segment operating income $8.8B
The cost side
Diesel at $6.29 Is the Pass-Through Mechanism
US on-highway diesel averaged $6.292 a gallon in the week of Nov 2, 2026, up from $2.539 a year earlier — a 148% move, and the reason holiday delivery prices are the most expensive on record. The cause is supply, not demand: global refinery inputs fell sharply in the second quarter of 2026 as Middle East outages cut runs, and refiners prioritised jet fuel, leaving US distillate inventories thin going into winter. Diesel is the mechanism that turns a refinery outage into a retailer's margin loss within a single shipping cycle.
Retail diesel: the shock now, and the relief EIA forecasts
Weekly US on-highway diesel average against the Energy Information Administration's annual retail diesel forecasts
Unit: $ per gallon
Week of Nov 2, 2026
Weekly average, released Nov 3, 2026
6.3
EIA 2026 annual forecast
Short-Term Energy Outlook, November 2026
5.2
EIA 2027 annual forecast
Short-Term Energy Outlook, November 2026
4.5
Week of Nov 3, 2025
Weekly average a year earlier
2.5
The forward path matters for every margin call in this article. The Energy Information Administration expects retail distillate to stay above $6 a gallon in October and then ease, with annual averages of $5.19 for 2026 and $4.49 for 2027. Even then, East Coast distillate inventories are forecast to sit 10% to 30% below the 2021-2025 average throughout 2027, so the cost base does not return to the pre-shock world.
Who passes it on
Carriers Turned Fuel Into Revenue and Kept the Margin
| Carrier | Shoulder period | Peak period | Peak vs 2025 | Additional handling at peak |
|---|---|---|---|---|
| UPS | $0.50 (Sep 27–Nov 21) | $0.75 (Nov 22–Dec 26) | +25% | $11.90 (from $8.75) |
| FedEx | $0.50 (Oct 26–Nov 22) | $0.80 (Nov 23–Dec 27) | +23% | $11.85 (from $8.80) |
The carriers' own accounts show what that does to the profit and loss account. UPS reported third-quarter revenue of $22.9 billion, up 6.7%, with US revenue per piece up 6.1% even as US average daily package volume slipped to 15.6 million. Revenue per piece rose while the package count fell, so price, not volume, is carrying the carrier's line. Consolidated operating margin was 7.6% on a GAAP basis, or 9.0% adjusted, against 8.4% a year earlier.
FedEx shows the other side of the same trade: revenue of $22.9 billion in the three months ended Sept 30, 2026, but operating income of $1.07 billion, a 4.7% margin, against $1.30 billion and 5.8% a year earlier, with net income of $290 million versus $824 million. Those surcharges recover the cost of the trip without paying for the network.
- Ground parcel rates are indexed 43.3% above the January 2018 baseline for the fourth quarter of 2026, express 20.3%, LTL 82.5% and truckload 23.4%, according to AFS Logistics and TD Cowen forecasts.
- Truckload capacity is exiting rather than returning: C.H. Robinson's November freight update flags declining capacity, regional disruption and Middle East routing costs lifting transit times and rates.
- UPS US Domestic segment operating margin was 6.1% on a GAAP basis and 7.0% adjusted in the third quarter, which makes the surcharge a tax on the shipper rather than a margin lift for the carrier.
The absorber
Small Retailers Cannot Pass the Bill On
The squeeze lands on the merchants who buy freight at list. Jenni Shields, who sells handmade hair accessories under Evie Pearl Handmade, paid about $4.50 for an average shipping label last year. A batch of orders taken to the post office in Kansas City last month averaged nearly $6 a package. She charges customers $6 in shipping, including roughly $1.50 to cover packaging supplies, so the math is unforgiving: she absorbs about $1.50 a package while charging a flat $6, and says she is losing money rather than breaking even on orders.
Losing money… no longer breaking even on orders.
The second problem is that small merchants cannot re-price. A $6 shipping charge on a $20 order is a 30% add-on to the purchase, and one apparel seller told CNBC he charged customers for return shipping for the first time this year after deducting it from refunds; another said sales slowed once shipping fees went up. Scale is the pass-through mechanism itself: large shippers buy dedicated contract capacity at pre-agreed rates, while small shippers buy spot, according to Jason Seidl, transportation analyst at TD Cowen.
Pass-through math on one $20 order
UPS residential peak surcharge
$0.75 per package
2025 peak: $0.60 — up 25%
FedEx residential peak surcharge
$0.80 per package
2025 peak: $0.65 — up 23%
Small merchant label cost
about $6.00 per package
About $4.50 a year ago — up 33%
Unrecovered freight per order
about $1.50
7.5 points of gross margin on a $20 order
Amazon quarterly shipping costs
$28.3B
Q3 2026, up 11.9% year over year
Walmart quarterly operating margin
5.0%
Quarter ended July 31, 2026
Bain's retail practice head Aaron Cheris told CNBC this is shaping up to be a record year for shipping costs, and that many retailers could be in financial distress in the first quarter of 2027 if they fail to get through the season. For these merchants the holiday is not a demand problem. It is a financing problem.
The scale absorber
Amazon Absorbs the Same Shock Without Paying More per Shipment
Amazon discloses the freight bill in its quarterly filings, and the numbers say scale wins. Shipping costs were $28.3 billion in the third quarter of 2026 against $25.3 billion a year earlier, a rise of $3.0 billion or 11.9%, while net sales grew 12.1% to $201.9 billion. The company holds shipping intensity flat at about 14.0% of revenue, and nine-month shipping costs rose to $81.9 billion from $71.2 billion.
The reason is structural. Amazon's delivery cost is mostly labour and network density rather than a diesel index, and it owns the trucks, the sortation capacity and the air freight it buys. Gross margin still expanded to 53.2% from 50.8%, operating income rose 61% to $28.1 billion, and fulfillment expense was $30.0 billion against $27.7 billion. A merchant buying a $6 label has none of those levers, which is why the same fuel price produces opposite outcomes.
The spread
The Spread Lands on Refiners, Brokers, LTL Carriers and the Card Network
| Company | Latest quarter | Role in the chain | Verdict |
|---|---|---|---|
| Valero | Refining margin $39.24/bbl vs $13.14; refining segment operating income $8.8B vs $1.6B | Upstream — owns the diesel | Captures the spread |
| C.H. Robinson | Revenue +29.5% to $5.36B; gross profit +127% to $808M; EPS $1.69 vs $1.36 | Broker — sets the shipper-carrier gap | Captures the spread |
| XPO | Revenue +12.4% to $2.37B; operating income +39% to $288M; EPS $1.55 vs $0.69 | LTL — repriced ahead of fuel | Captures the spread |
| Visa | Fiscal Q4 net revenue +13.2% to $12.1B; operating margin 59.8% | Downstream — earns on nominal spend | Captures the spread |
| Amazon | Shipping costs +11.9% to $28.3B; intensity flat at 14.0%; operating income +61% to $28.1B | Downstream — scale absorber | Absorbs and re-prices |
| J.B. Hunt | Revenue +20.4% to $3.68B; gross profit −17.3% to $350M; EPS $1.82 vs $1.74 | Truckload — buys the fuel | Absorbs |
| UPS | Revenue +6.7% to $22.9B; US revenue per piece +6.1%; operating margin 7.6% | Parcel — invoices the fuel | Passes through |
| FedEx | Revenue +2.7% to $22.9B; operating income $1.07B; margin 4.7% from 5.8% | Parcel — invoices the fuel | Passes through, thin margin |
Fourth-quarter 2026 rate indices against the January 2018 baseline
AFS Logistics and TD Cowen forecasts for the 2026 holiday peak
Unit: % above January 2018 baseline
LTL
82.5%
Ground parcel
43.3%
Truckload
23.4%
Express parcel
20.3%
The pattern is not subtle. Valero nearly tripled refining margin per barrel to $39.24 and its refining segment earned $8.8 billion against $1.6 billion a year earlier, because the diesel shock that ruins a small merchant's order is the refiner's revenue line. C.H. Robinson grew revenue 29.5% to $5.36 billion while gross profit rose 127% to $808 million — brokers earn on the gap between what the shipper pays and what the carrier costs, and that gap widened in a capacity-short peak. XPO turned 12.4% revenue growth into 39% operating income growth because LTL rates were indexed 82.5% above January 2018 levels. And Visa is the quiet winner: a holiday that is 4.5% nominal and 1.1% real still grows fee-bearing volume, because card fees are charged on dollars, not on units.
- The mix shift from travel to physical gifts converts service dollars into freight-intensive goods dollars — goods need a truck and experiences do not, and global air cargo at $3.37 a kilogram was up 43% year over year.
- Card data show a bifurcated basket: Visa found holiday airfare bookings up 29% and airfare spending up 38% in September among households earning above $200,000, while lower-income households pulled back sharply.
- Refiners are earning a cycle position rather than a moat: the same crack spread that made Valero's quarter makes it the most cyclical name in this article.
Cross-industry
The Same Cost Math Is Now Landing on Automakers
The warning General Motors issued with its third-quarter results is the retail squeeze restated in a different industry. Management put commodity, logistics and memory-chip costs at roughly $2 billion of headwind for 2026, with up to $1.5 billion of additional 2027 EBIT pressure if commodity prices hold. The company still earned $3.79 a share against $1.37 a year earlier, on revenue of $50.0 billion.
What GM cannot do is find volume. Global light-vehicle production is forecast at about 91.65 million units in 2027, essentially flat after a 2.1% decline in 2026, and the average US transaction price in September was more than $50,500 with a typical payment of $776 a month, the highest since December 2023. With no volume growth to dilute the cost and prices already near records, the arithmetic leaves no room to absorb a $2 billion headwind. In Europe, BMW said accelerated restructuring alone will cut its automotive pretax margin by 2.5 percentage points this year.
Horizons
Near Term the Surcharge Window Sets the Quarter; 2027 Relief Is a Forecast, Not a Fact
- The peak surcharge windows are the event: UPS charges $0.75 from Nov 22 to Dec 26 and FedEx $0.80 from Nov 23 to Dec 27, which makes the peak window the largest pricing event of the year for anyone shipping a parcel.
- UPS guided to fourth-quarter revenue of about $25.7 billion and adjusted operating profit of about $3.3 billion; the January print is the first clean read on whether surcharges cover the cost of the trip.
- Visa's January card data will show how much of the 4.5% nominal holiday growth was price, and whether gifts really crowded out travel in the mix.
- Stress at the small-merchant end is a first-quarter 2027 story, per Bain's Aaron Cheris, and should show up in receivables and charge-offs rather than in holiday headlines.
The relief case rests on the Energy Information Administration's forecast that retail diesel averages $5.19 a gallon in 2026 and $4.49 in 2027, with distillate inventories normalising toward December 2027. That is the single most important assumption in the trade: the whole 2027 margin case hinges on diesel averaging $4.49. If it happens, surcharges unwind through 2027 and the small-merchant squeeze is a one-to-two-quarter problem — but parcel revenue per piece fades and the refiner's crack narrows. If refinery outages persist and diesel holds above $6, the automaker's 2027 headwind roughly doubles and the retailer's problem extends into 2027 as well.
Where the holiday cost-push spread actually lands
- US revenue per piece rose 6.1% in Q3 2026 while consolidated operating margin slipped to 7.6% from 8.4% a year earlier, so fuel recovery is not margin expansion.
- Peak residential demand surcharge of $0.75 runs Nov 22 to Dec 26, adding about $0.15 a package versus the 2025 peak.
- Near term: guidance of $25.7B Q4 revenue and $3.3B adjusted operating profit tests whether surcharge revenue covers the network.
- Long term: EIA's $4.49 diesel forecast for 2027 unwinds surcharge revenue faster than volume replaces it.
- Operating income fell to $1.07B from $1.30B on revenue of $22.9B, cutting operating margin to 4.7% from 5.8%.
- Peak residential surcharge of $0.80 from Nov 23 recovers only part of a 148% diesel move, leaving a 4.7% margin base exposed.
- Near term: the Nov 23 to Dec 27 surcharge window is the only pricing lever before the December print.
- Long term: a $4.49 diesel price in 2027 would strip surcharge revenue from a network running thin margins.
- Shipping costs rose 11.9% to $28.3B in Q3 2026 while revenue rose 12.1%, holding shipping intensity at about 14.0%.
- Gross margin expanded 240bp to 53.2% and operating income jumped 61% to $28.1B.
- Near term: physical gifts taking budget share from travel adds parcel volume for the largest US network.
- Long term: a 33% label-cost move is a rounding error against $28.3B of quarterly shipping spend.
- LTL rates indexed 82.5% above the January 2018 baseline for Q4 2026 let carriers reprice ahead of the fuel bill.
- Q3 operating income rose 39% to $288M and EPS reached $1.55 from $0.69 a year earlier.
- Near term: December freight awards reset 2027 contract rates while capacity stays tight.
- Long term: contract gains repriced in a $6 diesel year persist into 2027 even as diesel falls to $4.49.
- Gross profit jumped 127% to $808M on revenue up 29.5% to $5.36B in Q3 2026, evidence the broker spread widened in a capacity-short peak.
- EPS of $1.69 beat $1.36 a year earlier even as truckload gross profit fell 17.3% for smaller carriers.
- Near term: fourth-quarter spot rates are the year's widest as truckload capacity continues to exit.
- Long term: a 2027 diesel decline shrinks surcharge revenue in the top line but not the spread.
- Fiscal Q4 net revenue rose 13.2% to $12.1B with operating margin of 59.8%, up from 57.3%.
- Holiday retail sales of +4.5% nominal on +3.4% goods prices means fee revenue grows even with real demand up only 1.1%.
- Near term: January transaction data confirms whether gifts crowded out travel in the card mix.
- Long term: a physical-gift basket is more card-intensive than experiences, lifting yield on nominal spend.
- Refining margin of $39.24 a barrel in Q3 2026 nearly tripled from $13.14 a year earlier.
- Refining segment operating income of $8.8B compares with $1.6B a year earlier on a total company operating income of $9.07B.
- Near term: diesel above $6 a gallon through October keeps crack spreads at record levels.
- Long term: EIA's $4.49 diesel forecast for 2027 erodes the crack, making this a 2026 trade.
- GM flagged about $2B of commodity, logistics and memory-chip costs, with up to $1.5B more 2027 EBIT pressure if prices hold.
- 2027 global light-vehicle production is forecast at 91.65 million units, essentially flat, leaving no volume to dilute costs.
- Near term: the fourth quarter absorbs roughly $400M of the headwind.
- Long term: a $50,500 average transaction price caps how much cost can be passed to buyers.