Industrials
Order books, backlogs and factory economics
Capex cycles, freight rates, automation and labour, followed through the machinery, transport and construction names that price them first.
2026-08-09

2026-08-08
USPS’s $2.5B quarterly loss is a parcel-economics stress test—and UPS/FedEx should expect margin squeeze from slower price/volume alignment
USPS reported a GAAP net loss of $2.5B in its latest reported quarter while operating revenue rose and operating expenses also rose. The mix matters: USPS grew “Shipping and Packages” revenue even as Shipping and Packages volume fell 3.4%, a pattern that points to persistent cost/volume friction—exactly the same variable pricing-power strategies depend on for UPS and FedEx.
Volkswagen’s US-built pickup play is a direct tariff-resistant hit at Ford’s truck profit engine
Volkswagen is moving a US-built pickup to the “end of the decade” timeframe as part of a broader US strategy overhaul under new leadership. The move matters to investors because it targets the same US profitability gravity well—Ford’s truck-and-commercial “Ford Pro”—where Ford posted $6.8B of EBIT on $66.3B of revenue in 2025 (10.3% margin), and it forces a rethink of EV-vs-ICE mix inside VW’s Chattanooga footprint.
2026-08-07
Microchip may be the rare analog/MCU story where guidance implies a broad inventory cycle already turning
In its latest SEC filing, Microchip links sequential net-sales strength to customers reducing excess inventory, and it shows inventory-days improving while gross margin benefits from lower inventory reserves. If the same “inventory-to-orders” mechanism keeps flowing, it’s a test of whether the semiconductor recovery is staying broad (industrial/auto/embedded), not only AI infrastructure.
Microchip’s inventory normalization shows the industrial analog/MCU cycle, not just AI accel, is turning
In Microchip Technology’s latest filings, both distribution-channel and direct-customer inventory days move toward “normal” while bookings and backlog strengthen. That combination—“trifecta” demand recovery plus fewer inventory gaps—argues the semiconductor inventory cycle is broadening beyond a single AI accelerator read-through.
2026-08-06
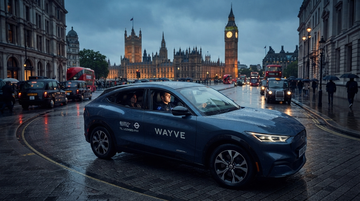
London’s robotaxi approval proves the “rules economy” will beat fleet scale—Uber and Wayve just cleared the UK’s supervised-PHV gate
Transport for London (TfL) licensed Wayve’s autonomous vehicles for Private Hire Vehicle (PHV) operations with a qualified driver onboard, under the Government’s AV Trialling Code of Practice and Uber’s TfL PHV operator licence. The strategic takeaway for investors: this isn’t about how big the first fleet is—it’s about whether a non-US, non-map-first stack can monetize autonomy under constrained supervision, a template regulators from Australia to Singapore are likely to benchmark.
FCC’s Chinese telecom import curbs are starting to act like a capex reroute—here’s the carrier + optical-networking transmission path investors can actually model
The FCC’s expanding ban on imports of certain Chinese telecom and video-surveillance equipment is framed in reporting as more than a pure security measure: it functions as a US-production-reroute lever that can shift how carriers source network buildout hardware. That changes the supply-chain winners by pulling incremental demand toward “non-Chinese-ruled-out” routing/transmission stacks and the US service/install ecosystem, with near-term spend typically landing in optics and network equipment refresh cycles rather than distant software-only compliance.
2026-08-05
Booking Holdings's Q2 only passes the “Hormuz shock decoupling” test if its region mix and monetization hold while US softens
In Booking Holdings's latest quarter, the company produced $7.352B of revenue and $2.54 EPS on $3.108B of free cash flow, giving a strong baseline for whether demand is geographically reallocating. But the decisive “US-subsidized by Europe/Asia” conclusion requires Q2 2026 geographic/segment disclosures that were not reliably retrievable from the filings pages in this session, so the article separates what is verified (financials) from what remains not disclosed (region-specific pressure) and flags the exact missing proof.
Cerberus’s $4B Supply Chain Fund II pitch turns private capital into a Pentagon policy lever—because Feinberg is now an underwriting mechanism
Cerberus is targeting at least $4B for its second supply-chain fund, framed as scaling U.S. domestic industrial capacity. The unusual signal isn’t just fundraising size—it’s that Stephen Feinberg’s post as Deputy Secretary of Defense creates a feedback loop where defense-aligned portfolio bets can directly shape the Pentagon’s procurement-and-industrial base priorities.
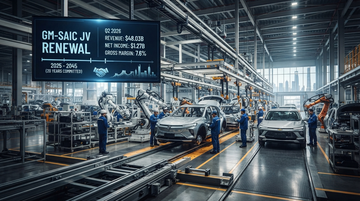
General Motors's SAIC JV renewal makes “decoupling” look optional—because it locks manufacturing in China through 2045
GM renewed its 50-50 SAIC joint venture for 20 years after a restructuring that included plant closures and model elimination, extending the partnership’s manufacturing commitment in China through 2045. That decision reframes the investing debate: US automakers aren’t just choosing where to sell—they’re choosing where to stay and who controls the production footprint. The second-order question now is whether Ford and Stellantis treat JV renewals as a supply-chain strategy template (or an overdue retreat).
Honeywell Aerospace is trading like an “inventory-and-labor” story after it cut its 2026 outlook for supply-chain reasons
Honeywell Aerospace’s first stand-alone guidance update reframes the supply-chain debate from macro “constraint noise” into a measurable operating squeeze: inventory normalization and labor execution risk show up in how it guides 2026. For investors, the read-through is less about “GE Aerospace-style sell-the-news” and more about who downstream can absorb delivery gaps while upstream (titanium/fasteners/avionics) still has the hardest bottlenecks to solve.
Wells Fargo’s “AI trickle-down” reframes Industrials: the winners are the grid-and-automation bottleneck, not just the factory-build line
Wells Fargo’s Aug 4 framing that hyperscaler AI spending is “trickling down” into older industrial supply chains makes the AI trade less about Mag-7 capex optics and more about domestic, capacity-constrained build cycles. The investable map is concentrated in electrification + control/automation equipment where capex shifts translate into order intake and backlog visibility—while broad-cycle heavy equipment is more rate-and-cycle sensitive.
2026-08-04
2026-08-03
2026-08-01
2026-07-31
Eaton’s 43% Electrical Backlog Surge Says AI’s Next Constraint Sits Between the Grid and the Chip
Eaton’s July 31 print showed that AI infrastructure demand is broadening from processors and power generation into electrical distribution: second-quarter sales reached $8.53 billion, while electrical backlog rose 43%. The opportunity is real, but so is the price of capturing it—Eaton spent $11.08 billion on acquisitions in the first half and nearly doubled net debt, leaving investors with a high-growth switchgear thesis carrying acquisition and valuation risk.
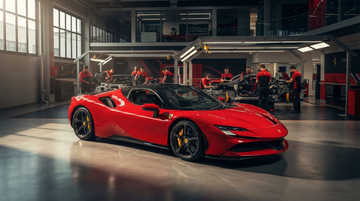
Ferrari's €7.6B raise says US super-rich demand is decoupling from the Iran/Hormuz luxury haircut — and it printed the cleanest luxury margin in Q2
Ferrari lifted FY26 guidance to ~€7.60B revenue and ≥€9.68 adj. EPS after Q2 net revenues rose 11% at constant currency to €1.94B, with a 39.0% EBITDA margin and order book fully sold through 2027 — a quarter in which Americas unit shipments actually fell on model changeovers. Against peer prints (LVMH fashion +1% organic, Kering +2%, Tapestry pressure), the Ferrari result is the first hard post-Hormuz data point showing ultra-luxury US demand is durably above the rest-of-world drag, and the contrast is what makes the multiple worth re-underwriting.
Rivian Has a Software Margin, but the R2 Ramp Must Turn It Into a Business
Rivian’s Q2 2026 results confirmed a more valuable mix: software and services generated $215 million of gross profit at a 42% margin, while R2 customer deliveries began on June 9. That margin is meaningful, but it does not yet make Rivian a software company—the company still posted a $379 million adjusted EBITDA loss and burned $849 million of free cash flow in the quarter. The investment case now depends on whether R2 can expand the installed base quickly enough for software profits to absorb automotive losses.
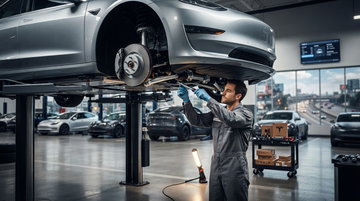
Tesla's 1.2 Million-Vehicle Probe Is a Valuation Test, Not Yet a Recall
NHTSA is investigating 1,198,300 older Model 3 and Model Y vehicles after 156 reports of a lower suspension link detaching, but it has identified no crashes, injuries or deaths. The direct repair liability is still unquantifiable; the larger issue is that Tesla trades at roughly 212 times trailing free cash flow while spending more than $25 billion this year on AI, making any evidence of weak hardware controls disproportionately important.
2026-07-30
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.