Industrials
Order books, backlogs and factory economics
Capex cycles, freight rates, automation and labour, followed through the machinery, transport and construction names that price them first.
2026-10-11

2026-10-10
2026-10-09
The $740 Billion Data Center Buildout Is a Completion Trade Now. Boockvar Says One Shock Could End It.
Peter Boockvar used an Oct. 9 CNBC appearance to reframe the AI data-center capex cycle as a clock: it works until it doesn't. With hyperscaler capex approaching ~$720–745 billion in 2026 and already consuming roughly 90% of operating cash flow, the trade is priced for the buildout to complete, not stall. Even a single trigger — a financing pinch, a power-cost spike, or a fresh wave of cancellations on top of the $260 billion already pulled in 2026 — could revalue the supply chain from completion to stall, with Vertiv at 27.8x and Equinix at 52x forward earnings the most exposed.
44 EU Industry Groups Just Signed the Trigger Letter — Why US Steel, Chemicals and Defense Are About to Sit in the Same Risk Channel
Forty-four European industry associations urged the EU on Oct. 8 to activate every trade-defence tool available against Chinese overcapacity, ahead of an October 15–16 leaders' summit where France and Germany are pressing for a US-Section-301-style rapid-response instrument. The move mirrors the 2018 US pattern — industry filings into Washington preceded a binding 25% Section 232 steel tariff — and turns Europe's rhetorical defence into a credible binding threat. Combined with US Section 232 derivatives at 50% on 407 product categories, this pulls Nucor, Cleveland-Cliffs, Steel Dynamics, Dow Inc, LyondellBasell, General Dynamics and Lockheed Martin into a coordinated Transatlantic defensive wave that props up US margins and lifts defense demand.
2026-10-08
2026-10-05
Buffett's 11.2% Lennar Bet Says the Housing Bottom Is Already Behind Us
Berkshire Hathaway has quietly accumulated an ~11.2% stake in Lennar — roughly 26.6 million shares worth about $2.16B at an average near $81 — by buying aggressively through the Sept. 16 delivery-guidance cut and the 30-year mortgage's breakout past 7%. The position sits next to the $8.5B Taylor Morrison acquisition Greg Abel closed in July, turning Berkshire into a top-five U.S. homebuilder at the precise moment peers are pulling guidance. The message: the worst of the rate damage is in the rearview mirror, not the next two quarters.
Schneider's $20B PTC Bid Forces a Reckoning for Dassault, Siemens — and Every PLM Holder
Schneider Electric is closing in on a roughly $20 billion all-cash takeover of PTC, the US leader in CAD and product lifecycle software, at a ~28% premium to PTC's last close. The deal would be the largest cross-border acquisition of a US industrial-software asset in years and would instantly re-rate the competitive map against Dassault Systèmes and Siemens, the two incumbents that have dominated PLM since the 2000s. The question for investors is no longer whether Autodesk and Cadence sit on the same M&A runway — it's how the financing math holds up: the bid would push Schneider's pro-forma net leverage from 1.7x to roughly 3.6x EBITDA, a stretch even for a serial acquirer that just spent $3.1B on Cognite.
2026-10-04
2026-10-01
Accelevation's $18 IPO Was Priced 10% Below the Mark, and the Multiple Stack Says Is Worse for the Neoclouds Behind It
Accelevation priced at $18 against a $20–$24 range, opened down 2.5%, and closed essentially flat on day one — a tepid verdict on the rack-builder model that puts the spotlight on listed neocloud peers trading at 12–43x EV/Sales. With ~$176B of GPU-collateralized debt on the books and a Lambda/Nscale/Groq IPO queue still to clear, the read-through forces a discount on every chip-collateralized name priced like hyperscaler-equivalent capacity.
The 88% Adoption Number Is Hiding a 6% Problem: Enterprise AI Hits Its Production Wall
A Reuters Breakingviews analysis (Sep 16, 2026) and McKinsey's 2026 State of AI show AI has saturated the workplace — 88% of organizations use it, only 6% capture meaningful EBIT from it, and only 23% scale any agentic system in production. For Salesforce, ServiceNow, MongoDB, and the wider 'AI-led growth' SaaS cohort, the pilot-to-production chasm is now the actual valuation test: vendor ARR is up 240%, but the buyers writing those checks are quietly routing their next dollar of capex to NVIDIA chips and Microsoft infrastructure, not software seats.
2026-09-30
2026-09-28
2026-09-26
2026-09-25
Eaton just paid €810M for an Italian switchmaker — Europe's AI-grid race is now a balance-sheet fight
Eaton agreed to buy Italy's COL Group from Oaktree for €810M, landing four manufacturing sites and an SF6-free switchgear specialty just as the company's Electrical Global backlog jumped 103% in Q2 2026 and the EU's January 2026 F-gas ban rewrote the rules. With European transformer lead times running four years and SF6 medium-voltage switchgear now banned, capacity — not innovation — is the gating constraint, and Siemens Energy, ABB, Schneider Electric, and Hitachi now have to match a balance-sheet move, not a product release.
Lowe's Drone Pilot Just Made Wing and DoorDash the Default Last-Mile Stack — and Forced Home Depot to Spend
Lowe's is using Wing drones and the DoorDash app to ship 2.5-lb hardware items to a five-mile Matthews, N.C. radius in as little as 20 minutes — the first credible proof that drone economics work for high-ticket, lower-velocity SKUs, not just sub-2-lb restaurant food. Wing now holds the last-mile infrastructure layer (Walmart + Lowe's + the DoorDash restaurant network), while DoorDash controls orchestration — and simultaneously stood up its own FAA Part 135 carrier, DoorDash Air, to operate alongside the partners it depends on. The repricing is already underway: Home Depot launched nationwide three-hour express delivery five weeks earlier, betting ground couriers can still hold the home-improvement SKU set.
Tesla's Nevada Semi Plant Just Reshuffled the 2027 Truck Story — Incumbents Are Now on the Clock
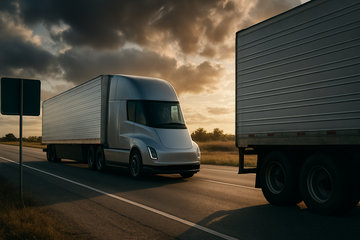
Tesla opened its first high-volume Semi factory in Sparks, Nevada on September 24, 2026 — a 1.8 million sq ft plant sized for 50,000 trucks a year, on the same site that builds its 4680 cells. With3,370+ Class 8 orders already in hand (WattEV, Einride, ZET SCALE) and 11 customers including PepsiCo and DHL taking delivery, the Semi line is real, ramping, and squarely aimed at the Daimler Truck / PACCAR / Volvo Class 8 incumbents. At $290,000 for the 500-mile variant, Tesla is priced ~$110,000 below the Daimler eCascadia — turning freight electrification from a side bet into Tesla's biggest 2027 growth lever.
2026-09-24
2026-09-23
2026-09-22

One Backhoe Cut Exposes the Gap Between the FAA's $875M AI Plan and Its $2.4B Verizon Contract
On the same day the FAA launched its $875 million SMART AI tool at Washington-area airports, a severed Verizon fiber line in New Jersey grounded thousands of flights across five Northeast hubs — proving that predictive software does not fix a single point of failure in the physical telecom layer. The episode puts United Airlines and American Airlines on the hook for the most exposed hub economics, hands Verizon its strongest argument for accelerating the long-delayed FENS contract, and shows investors why the administration's three modernization workstreams — the AI rollout, the $16B ATC overhaul, and the $2.2B 5G altimeter rebate — are not interchangeable.
Seoul's $350B US Investment Debuts With a Money-Losing Gas Plant — and That Changes the Calculus for Korean EPCs
South Korea's trade ministry has confirmed the $22.3B Encinal, Texas gas-fired power plant as the inaugural project under its $350B US investment pledge, but President Lee and Prime Minister Han have publicly flagged commercial-viability concerns — and lawmakers just demanded the project briefing be pulled. The deal's structure (an I-SPV with Lewis Energy as project owner, offtake tied to ERCOT or captive AI data centers) hands EPC work to Doosan Enerbility, Hyundai E&C, KEPCO E&C and Samsung E&A, while the same package's contemplated follow-on — up to eight US nuclear reactors — is itself a contested Westinghouse-vs-APR1400 design fight. For investors, the read-through is asymmetric: the deal tape is not a tailwind for Korean industrials, it is a proof-of-concept that the chaebol money is being deployed at returns below the listed companies' own hurdle rates.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.