Industrials
Order books, backlogs and factory economics
Capex cycles, freight rates, automation and labour, followed through the machinery, transport and construction names that price them first.
2026-07-26

2026-07-25
2026-07-24
Geely’s “No-Brand-Print” Play in Spain: China EVs First Enter Europe by Taking Over Ford’s Idle Capacity—Not Buying a Publisher-Brand
Geely’s agreement to use Ford’s Almussafes plant in Valencia to produce Geely EVs creates an EU-manufacturing “origin story” that Reuters links directly to avoiding EU tariffs on Chinese EV imports. The real supply-chain message is capacity arbitrage: idle European lines get monetized by China volume, shifting battery/material demand toward whatever can qualify for the JV’s EV ramp instead of whichever OEM owns the logo.
Volkswagen’s 2026 growth floor becomes an earnings/Europe demand-reset signal—restructuring moves from ‘cost program’ to OEM P&L control
Volkswagen AG is not merely trimming costs; it has framed 2026 as a low-growth band (sales revenue +0% to +3%) while pushing a transformation that targets overhead, plant efficiency, and product/tech complexity. That combination turns the EU demand reset into an internal OEM lever—meaning suppliers should expect slower volume pass-through and faster mix-driven re-rating rather than a clean demand rebound.
2026-07-23
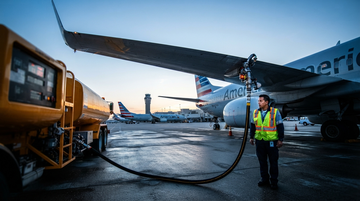
American’s fuel-cost warning matters because airline cash flow is the shock absorber—and it just looks too thin
When American Airlines Group warns that fuel costs can overwhelm margin improvements, the market shouldn’t just model weaker earnings—it should also model weaker operating cash generation. Using AAL financial statements, we show how small earnings-quality shifts can translate into a disproportionate free-cash-flow hit, which then raises industry-wide funding pressure and makes fare “pass-through” less timely than investors assume.
GE Vernova’s Backlog Is Strong—but the “Margin Leakage” Risk Lives in Equipment Mix and Execution-Cost Timing, Not Demand
GE Vernova reports a growing electrification and grid backlog (RPO) of $44.6B, but the backlog’s margin quality depends on equipment-vs-services mix and how execution costs and timelines hit project-level contracts. In its latest filings, GE Vernova shows large RPO growth concentrated in Power and Electrification equipment (where schedule and cost overruns matter most), while it separately flags tangible cost/timeline pressure in other execution-heavy businesses—an investor analogue for what can go wrong. The actionable takeaway: treat backlog growth as necessary proof of demand, and backlog composition + disclosed execution risks as the real predictor of margin and cash-flow outcomes.
GM’s “Resilient Demand” Margin Lift Implies a Very Specific EV Loss Cessation Path—And Tariffs Remain a Live Variable
GM’s July 21 update frames margin durability around resilient consumer demand and pricing discipline, while simultaneously publishing a 2026 GMNA EBIT-adjusted margin target of 8.0%–10.0% and a 2026 EBIT-adjusted tariff swing of roughly $2.5B–$3.5B. The underlying risk is that EV losses and EV-related charges have recently been material (e.g., multi‑billion dollar realignment charges in 2025), so “resilient demand” only holds if EV mix and incentive intensity don’t force GM back into similar loss dilutions.
Atoms’ $1.7B round is the robotics world’s bet on “robot-as-a-service,” not robot-as-a product—at least in how it will be financed
Travis Kalanick’s private robotics venture Atoms raised a $1.7B round led by Uber‑adjacent capital and Bain Capital‑style growth/venture investors, positioning its “digitize the physical world” stack around specialized robots with productive jobs. The financing size and the company’s “software-like” orchestration language point to a shift: customers may increasingly buy outcomes and deployment capacity, while investors fund fleet-like rollouts before unit economics are proven.
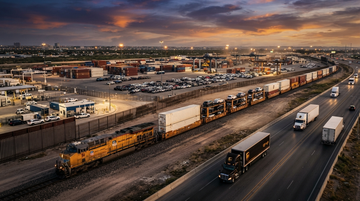
USMCA’s “Deadline Cliff” Is Losing Its Edge: Why a 2026→2027 Drag Changes Auto & Trucking Pricing Power
U.S. Trade Representative Jamieson Greer confirmed the U.S. did not renew USMCA in its current form and indicated the process could extend into next year via interim arrangements. For investors, that shifts the auto supply-chain from “meet the rule-or-pay tariffs” urgency into a “re-price production and capacity” regime—affecting Union Pacific, CSX, and UPS through timing of North America cross-border flows and planning.
2026-07-22
Tesla’s Q2 2026 Earnings Still Come Down to Automotive Margin Math—Energy Can Offset, But Not Replace the Signal
Tesla’s Q2 2026 print will be interpreted primarily through whether automotive gross margin stabilizes while deliveries normalize. The market focus is likely to treat energy storage as the stabilizer and automotive margin as the driver—because operating leverage in autos determines how much upside (or downside) the energy segment can absorb.
Wistron's $761M Fort Worth AI-Server Factory Is a “Domestic Scale” Test—Here’s What Could Still Break in Mid-2026
Wistron is building two Fort Worth AI supercomputer manufacturing sites totaling $761M, with the facilities expected to be operational by early 2026 and ramping mass production over the following 12–15 months. The deal is heavily structured around delivery/performance triggers (including minimum investment, jobs, and salary floors), turning execution capacity—not just demand—into the primary risk. The operational bottlenecks to watch aren’t only factory construction; they’re supply of server components, quality ramp, and the ability to sustain output once “pilot” becomes “production.”
2026-07-21
GM’s Q2 2026 Margin Beat Looks Like a Tariff-Refund Bridge—But EV Losses Leave the Sustainability Question Wide Open
General Motors’ Q2 2026 print lands at the intersection of two margin drivers: tariff-related refund expectations on one side and continuing EV-related cost pressure on the other. With US sales down 4.2% Y/Y in Q2 and ongoing EV strategic realignment charges, the key investor question is whether tariff benefits persist long enough to offset EV profitability drag in 2026.

Brookfield+[CPP Investments] to Take LXP Industrial Private for $5.2B—Industrial REIT M&A Is Pricing Control, Not Just Rent
Brookfield Asset Management and CPP Investments agreed to buy LXP Industrial Trust in an all-cash deal valued at about $5.2B (including net debt) at $61.20/share, a double-digit premium with a 40-day go-shop window. Using LXP’s recent fundamentals, the offer implies a rich takeover multiple versus the last several years’ revenue and cash flow—suggesting buyers are paying for asset/tenancy control and a path to recapitalize rather than buying a cheap stream of rents. For investors, this deal is a real-time “private-market bid” read-through to where industrial REIT control premium (and execution risk) is heading in 2H 2026.
3M’s Q2 2026 Setup: A Small EPS/Revenue Miss Is Less Concerning Than the Tariff-Cost Test to Its Back-Half Organic Growth
3M (3M Company) delivered Q2 2026 results that were slightly below consensus on both adjusted EPS and revenue, while reiterating full-year guidance for ~3% organic sales growth. The market focus is whether the post-Solventum footprint can keep the organic-sales pace as tariff drag hits consumer-leaning SKUs and pricing/mix. With recent quarterly revenue running in a narrow band (~$6.0B–$6.5B), the “execution” question is not demand collapse—it’s margin bridge durability.
2026-07-20
Molex-Prysmian's $6.29B Data-Center Cable Deal Is the Newest Anchor for the Hyperscaler Optical Supply Chain
On July 20, 2026, Koch-owned Molex struck a 10-year, up to $6.29 billion (€5.5 billion) deal with Italy's Prysmian for the supply of optical cables used inside AI data centers, including a €550 million upfront payment. The agreement — one of the largest hyperscaler-adjacent cabling contracts ever disclosed — follows Prysmian's May 2026 guidance that hyperscaler deals would push 2028 EBITDA up ~64% from 2024, and a $4.68B M&A exploration to bolt on capacity. The deal locks in critical optical interconnect supply at a moment when AI-driven data-center fiber demand is competing with telecom and subsea projects for the same Prysmian capacity.
Prologis's Third $18.2B Bid for Segro Just Got Rejected — What Happens Before the July 22 Takeover Panel Deadline
On July 17, 2026, Segro's board unanimously rejected Prologis's third sweetened takeover offer valued at approximately £13.5 billion ($18.16 billion), comprising £2.7 billion in cash and 0.0890 new Prologis shares per Segro share. The bid carries a 33.8% premium to Segro's June 23 closing price but was dismissed as still materially undervaluing the UK warehouse landlord. Under UK Takeover Panel rules, Prologis has until July 22, 2026 to either make a formal offer or walk away, with Bloomberg reporting a possible secondary London Stock Exchange listing as a sweetener. The proposed merger would create the world's largest industrial REIT at a time when data-center demand is reshaping the logistics property thesis.
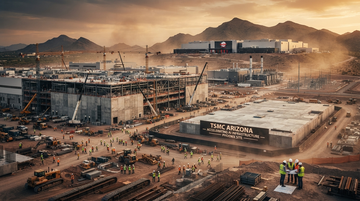
TSMC Accelerates Arizona Buildout, Lifts 2026 Capex to $60-64B — The AI 'Megatrend' Is Now a US Foundry Story
On July 20, 2026, TSMC CFO Wendell Huang told CNBC the company is accelerating its Arizona fab buildout to capitalize on what he called a 'multi-year structural' AI 'megatrend', with the Arizona pipeline raised to $265 billion on top of an additional $100 billion commitment. TSMC simultaneously lifted full-year 2026 capex guidance to $60-64 billion (from a prior $52-56B) and confirmed Phase 1 of Arizona is in production on 4nm, with advanced packaging also being built on-site. Crucially, Huang disclosed that US fab construction costs run 4-5x Taiwan levels, a key margin datapoint for assessing the long-run economics of US-based AI chip manufacturing.
2026-07-19
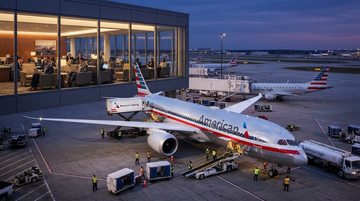
American Airlines’ $3 Billion Profit Gap: Turnaround Plan Meets a Structural Revenue Problem
American Airlines is trying to close a wide peer profit gap through premium cabins, lounges, schedule redesign, loyalty monetization, and fleet investment. The starting point is stark: revenue is only modestly below United's, but net income is far lower, which points to a structural monetization and cost-of-capital problem rather than a simple scale issue.
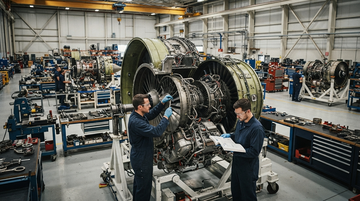
CFM's $2 Billion Repair Plan Says Aviation's Bottleneck Is Aftermarket Capacity, Not Engine Demand
CFM's five-year, $2 billion repair push is a signal that the supply problem in commercial aviation sits in maintenance, parts, and turn time. That has direct read-through for GE Aerospace, Safran, Boeing, and the airlines that are paying for missed utilization.

SpaceX's Pentagon AI Deal Turns Defense Compute Into a New Cloud Test
The Pentagon is reportedly considering a multibillion-dollar compute deal with SpaceX, which means defense AI is no longer just about models and chips. It is about who can deliver cheap, secure, and scalable data-center capacity without depending only on the usual cloud giants.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.