Policy & Trade
Tariffs, export controls, and who absorbs them
Rulings, sanctions and trade negotiations traced to the companies that pay for them — margin by margin, route by route.
2026-07-16

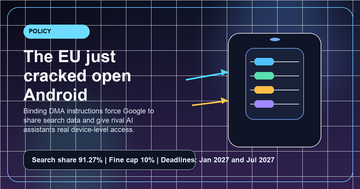
The EU Just Forced Alphabet to Open Android and Search Data to Rival AI Assistants
On July 16, 2026, the European Commission issued binding DMA guidance that forces Google to share certain search data with competitors and to give rival AI assistants equal access to Android features such as voice activation and background task execution. The immediate issue is regulatory, but the real issue is distribution: if Android stops being a closed assistant funnel, Google has to defend default behavior instead of assuming it. That changes the read-through for Alphabet, rival AI assistants, and every company trying to win the mobile entry point.
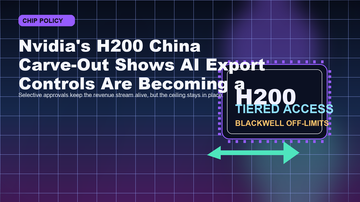
Nvidia's H200 China Carve-Out Shows AI Export Controls Are Becoming a Tiered Market
The latest H200 approvals do not reopen China. They make the AI chip war more granular: chip generation, named buyers, and compliance burden now define the market.
June Retail Sales Rose 0.2%, but the Real Signal Is a Split Consumer and a Fed That Still Cannot Relax
U.S. retail sales increased 0.2% in June, while ex-gas sales rose 0.7% and the control group gained 0.5%. The soft headline looks like consumer cooling, but the details say something more useful: spending is shifting, gas is masking strength, and the Fed still has to decide whether resilient demand or softer inflation is the bigger risk.
South Korea's AI Chip Boom Hit a Leverage Wall as SK Hynix and Samsung Electronics Drag the KOSPI Into a Bear Market
The July 16 selloff did not break AI memory demand. It exposed how crowded the trade had become after months of leverage, retail momentum, and rate-sensitive positioning.
Uber Agrees to Buy Delivery Hero for $14.8B - The Largest Cross-Border Food Delivery Deal in History and the Cleanest Single Consolidation Catalyst for the Global Online Food Delivery Duopoly
Investor's Business Daily reported on July 16, 2026 that Uber Technologies has agreed to acquire Berlin-based food-delivery peer Delivery Hero SE for $14.8B in cash + stock, in Uber's largest cross-border deal to date. The combined entity will have ~70 countries, ~40M+ monthly active eaters, and GMV scale approaching $200B run-rate. The deal hands Uber Eats clear #1 share in the Middle East, Japan, Korea, and Latin America, areas where Uber Eats has been sub-scale. The acquisition is the cleanest single most direct 2026 food delivery consolidation catalyst.
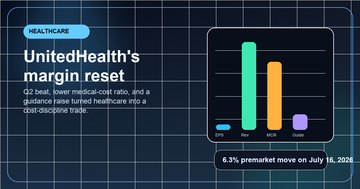
UnitedHealth's 86.7% Medical-Cost Ratio Turned a Healthcare Beat Into a Margin-Discipline Trade
UnitedHealth reported second-quarter 2026 adjusted earnings per share of $6.38 on $112.0 billion of revenue, lowered its medical-cost ratio to 86.7%, and raised full-year adjusted EPS guidance to $19.50-$20.00. The market reaction was immediate, but the real signal is that management is now prioritizing pricing discipline, mix, and cost control over top-line optics. That changes the read-through for managed care peers and for the healthcare sector's place in the July 16 tape.
2026-07-15
Australia's New AI Data-Center Rules Turn Power and Water Into the Next AI Capex Tax
Australia's July 15-16, 2026 policy shift says large AI data centers must secure their own power, cover their connection costs, manage peak-load behavior, and use water efficiently. The headline is about regulation, but the real message is capital discipline: AI infrastructure is no longer just a software or hardware spend, it is a grid, water, and permitting problem. That matters for Vertiv, Eaton, Equinix, Digital Realty, and every hyperscaler trying to scale demand without colliding with local utility politics.
BlackRock Crossing $15.3 Trillion AUM Turns Passive Flows Into the Real Market-Structure Trade
BlackRock reported Q2 2026 adjusted EPS of $13.91, revenue of $7.084 billion, and $15.3 trillion of assets under management after $192 billion of second-quarter net inflows and $321 billion in first-half inflows. The headline matters because it shows how equity beta, ETF dominance, and private-markets expansion are feeding the same fee engine. The stock's move was just the first-order reaction; the deeper read-through runs to State Street, Charles Schwab, KKR, Blackstone, and the active-vs-passive balance across the asset-management complex.
China's 4.3% Q2 GDP Reopened the Beijing Stimulus Trade — And the Nvidia H200 Path With It
China's Q2 2026 GDP printed 4.3% year-over-year, the weakest since Q4 2022 and below Beijing's 4.5%-5% full-year target. Real estate investment fell 18%, fixed-asset investment dropped 5.7% in H1, but industrial output rose 5.3% and retail sales rebounded to +1% from a -0.6% reading in May. The combination forced Beijing into a third-quarter policy-easing stance, which markets priced through China tech, the yuan, and a quiet re-rating of Nvidia on H200 export hopes. Alibaba, Tencent, PDD Holdings, BYD, and the China-exposed cyclicals all move with this trade.
June 2026 CPI at 3.5% YoY Is the Print That Just Reset the Social Security COLA Estimate - And the Fed Cut Path
The BLS June 2026 CPI report came in at 3.5% YoY, lower than expectations, driven primarily by a decline in energy prices, according to CNBC's reporting on July 14, 2026. The Senior Citizens League immediately trimmed its 2027 Social Security COLA estimate to 3.8% (unchanged from last month), while independent analyst Mary Johnson dropped her 2027 COLA estimate to 3.7% from 4.7% - a full percentage point cut in a single print. The disinflation reading is the first clean macro green-light of the cycle, and the rate-sensitive sectors (housing, regional banks, REITs, small caps) now have a real reason to lead.
June PPI's 0.3% Drop Gives the Fed Breathing Room, but It Does Not End the Inflation Trade
The U.S. Producer Price Index fell 0.3% in June, goods prices dropped 1.4%, services rose 0.2%, and year-over-year final-demand PPI still ran 5.5%. Markets immediately read the print as lower odds of further tightening, with the 2-year yield slipping and Fed pause odds rising, but the deeper message is that goods disinflation does not erase service inflation or energy volatility. The result still matters for BlackRock, JPMorgan, UnitedHealth, housing, utilities, and every rate-sensitive part of the market that lives off the next 25 basis points.
Alibaba and Apple Just Made Qwen the First Chinese AI Model Inside the iPhone Stack
Alibaba's U.S.-listed shares rose 4% in pre-market trading on July 16, 2026 after confirming its Qwen AI model will be integrated into Apple Intelligence across iOS, iPadOS, macOS, and visionOS for users in China. The Cyberspace Administration of China included Apple AI services on its approved-providers list alongside Huawei. The deal is the first time a Chinese AI model is inside the iPhone stack, and the read-through is direct for Apple, Alibaba, Huawei, Tencent, Baidu, and the entire cross-border AI-supply-chain complex.
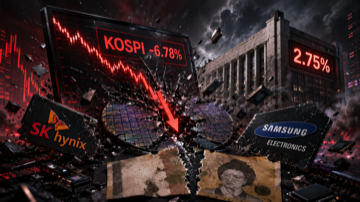
The Bank of Korea's First Hike in Three Years Is the First Asian Central Bank to Admit the Won Crisis Is Over
The Bank of Korea hiked rates 25bp to 2.75% on July 16, 2026 - the first hike since January 2023 - against June CPI at a three-year high of 3.2% and a won that had touched a 17-year low of 1,561.5 on June 5. The move is the first Asian central-bank admission that the regional currency-defense regime is ending, and the read-through is direct for Samsung Electronics, SK Hynix, Hyundai Motor, Kia, POSCO, KB Financial, and Shinhan Financial. The won at 1,484.86 is still 5% weaker than the 1,400 cycle-supportive level, and the BoK is buying time before any further tightening.
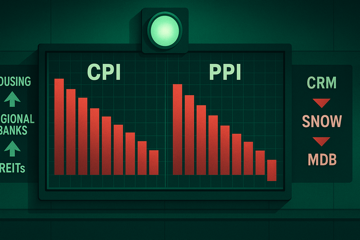
June 2026's -0.4% CPI and -0.3% PPI in the Same Week Are the First Real Disinflation Trade of the Cycle
The BLS June 2026 CPI fell 0.4% MoM (biggest drop since April 2020) and PPI fell 0.3% MoM (consensus was unchanged) on July 14-15, with goods prices dropping 1.4% (biggest since July 2022) on a 12% gasoline plunge. Core CPI slipped to 2.6% YoY and core PPI rose just 0.2%. The market read-through is direct: rate-sensitive sectors (housing, regional banks, REITs, small caps, dividend growth) now have a real green light, and the rate-cut pricing has collapsed from a near-certain hike to a 50-50 September bet. The cleanest expression is to be long the rate-sensitive rotation and short the high-multiple AI-application cohort that was the trade when the Fed was tightening.
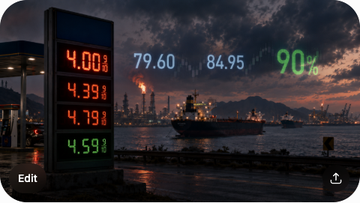
Kalshi Traders Now Put 90% Odds on Gas Crossing $4 This Month - And the Prediction Market Just Became the Cleanest Real-Time Tape on Hormuz Risk
CNBC reported on July 15, 2026 that prediction market Kalshi traders had priced a 90% probability that U.S. gas prices cross $4 per gallon by end of July - up from 56% just two days ago - with a 93% chance of crossing $4 and a 63% chance of exceeding $4.10, following the U.S. ending its Iran ceasefire and relaunching strikes. With WTI at $79.60 and Brent at $84.95, the prediction market is now the cleanest real-time tape on Hormuz risk - faster than futures, faster than retail gas data, faster than analyst notes. The read-through is direct for ExxonMobil, Chevron, ConocoPhillips, Valero, Marathon Petroleum, Phillips 66, United Airlines, Delta Air Lines, American Airlines, and the entire energy + transport complex.
LNG Deep Dive: How Cheniere Energy, Shell, TotalEnergies, QatarEnergy, and Woodside Run the $400B Global LNG Trade - and Why the 2026-2030 Supply-Demand Is the Binding Read on the Energy Transition
LNG (Liquefied Natural Gas) is a $400B/year global trade that has become the binding flexible-supply leg of the global energy transition. The 5 largest LNG suppliers are QatarEnergy (~25% global LNG export share), Cheniere Energy (~15%, the largest US LNG exporter), Shell (~10%, the largest IOC LNG portfolio), TotalEnergies (~8%), and Woodside (~5%, the largest Australian LNG exporter). This is a full-stack deep-dive into LNG: liquefaction technology (ConocoPhillips Optimized Cascade, Air Products AP-C3MR, Black & Black & Veatch PRICO), the FLNG revolution (Shell Prelude + Petronas PFLNG), the customer base (China, Japan, Korea, Europe), the top experts, the capex ($80-100B/year industry), the 2026-2030 supply-demand, and the read-through for the energy transition.
SpaceX Just Closed Below Its $135 IPO Price for the First Time - And the Private-to-Public Trade Is Now the Binding Test for Every Late-Stage Name in the Pipeline
CNBC reported on July 15, 2026 that SpaceX closed at $135.27 on its fourth consecutive losing session - the first close below the record $86B June 2026 IPO price of $135 - days after the Nasdaq-100 inclusion brought passive buyers in and ahead of the 13th Starship test flight on Thursday July 16. The break-under is the cleanest single read on whether the late-2025 / early-2026 private-mark pricing holds when $400B+ of cumulative private-tech paper tries to clear the public market. The read-through is direct for Anthropic, OpenAI, Stripe, Shein, Databricks, Canva, and the entire late-stage private cohort now queuing for 2026-2028 IPO windows.

Trump vs Hochul's NY Data-Center Moratorium Is the First Real Test of Whether AI Capex Has a Political Ceiling
President Trump publicly slammed New York Governor Kathy Hochul's new executive order barring for up to a year the construction of data centers that use 50+ MW of power, the first state-level moratorium of its kind in the U.S. Trump wrote on Truth Social that New York 'has made a terrible decision' and urged the state to change policy 'IMMEDIATELY.' The moratorium is the first concrete political constraint on the AI capex stack from a U.S. state, and the read-through is direct for Microsoft, Alphabet, Amazon, Meta, Nvidia, Equinix, Digital Realty, and every AI-infrastructure issuer with a NY exposure.
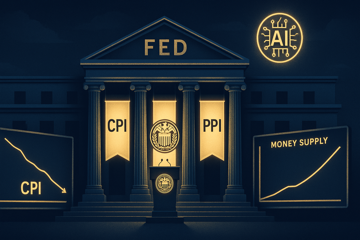
Warsh Just Turned the Fed From a Single-Mandate Inflation Fighter Into a Multi-Task Force Monetary Experiment
CNBC reported on July 15, 2026 that Fed Chair Kevin Warsh used two days of congressional testimony to launch a multi-pronged review of how the Fed measures inflation, restore money-supply reporting, and convene an all-bullish AI task force - all while CPI and PPI both printed unexpected declines. Fed Governor Lisa Cook pointed to AI spending as a potential inflation driver and warned 'inflation risks now outweighing employment risks.' The Fed meets in two weeks and markets are split on whether rates rise, hold, or fall - and the read-through is direct for every rate-sensitive sector, every AI capex issuer, and the bond market that is now repricing the Fed governance premium.
2026-07-14
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.