Energy
Crude, refining and the price at the pump
Supply, inventories, crack spreads and OPEC decisions, followed down to the producers, refiners and buyers who book the difference.
2026-08-03

KKR’s $19.2B infrastructure close marks the LP “go-ahead” for AI power + data-center deals (and it changes the deal math)
KKR’s KKR Global Infrastructure Investors V closing at $19.2B is the clearest public confirmation that large LP capital is willing to fund long-duration AI-adjacent infrastructure. The investable takeaway: this capital should compress the risk premium—and therefore improve entry valuations—for equity, credit, and lease/contract structures that sit between hyperscalers and the grid.
Trump turns supermajor capital return into a “gasoline-price” hostage—Exxon and Chevron can’t buyback their way out
On Aug 3, 2026, Trump told ExxonMobil and Chevron to “stop making too much money” and to “cut the retail price, the consumer price,” explicitly tying Big Oil’s high profits to gasoline affordability. The core investor risk is not that buybacks stop tomorrow; it’s that politicized price pressure forces Integrated majors to re-optimize cash allocation between returns, capex, and supply—raising second-order risk to Permian/Midcontinent-capex and refining feedstock plans.
2026-08-02
2026-07-31
Chevron's $12.1B Quarter Beats Exxon's $14.7B on Capital Return Math — The Iran-War Crude Print That Splits the Supermajors
Exxon Mobil and Chevron reported Q2 2026 earnings on July 31, fueled by Brent averaging $96.68/bbl during the Iran war — up 23% sequentially. Chevron's $6.06 EPS beat expectations by $0.50, while Exxon's $3.52 missed by $0.08, exposing a cleaner buyback/yield story at CVX versus XOM's scale advantage. Combined they returned $16B to shareholders and generated ~$35B of FCF in a single quarter, rewriting capital-return math into a sticky $90+ tape.
Westinghouse’s IPO Has a $30 Billion Shadow Price — but the Services Base Must Justify It
Westinghouse’s confidential filing is more than an IPO: it tests whether public investors will pay a premium for a reactor OEM that services roughly 63% of the operating fleet while retaining upside to a proposed 10-reactor U.S. buildout. The strongest valuation support comes from recurring fuel and outage work, not unbuilt reactors; the biggest complication is a government participation right that becomes economically relevant above a $17.5 billion threshold. For investors, the filing could reprice Cameco and Brookfield Renewable Partners first, then suppliers such as BWX Technologies if conditional projects become funded orders.
2026-07-30
Cenovus Energy proves oil’s operating leverage—then exposes how quickly it can flip
Cenovus raised its 2026 upstream production outlook as second-quarter net earnings surged to $2.87B, showing how a bigger barrel base can amplify profits when margins cooperate. But the same leverage also means the stock will be sensitive to any slip in crude differentials, refinery throughput/utilization, or capital/working-capital discipline—so the real question isn’t “can profits triple,” it’s “can they stay there.”
US Strike on Iran Forces a 2026 Risk-Premium Reprice: Oil’s “Discount” Is No Longer the Trade
A US strike on Iran reopens Strait-of-Hormuz tail-risk in hours, reversing the recent de-escalation-driven deflationary narrative for crude pricing. The fastest transmission is not headlines—it is how refiners’ and defense primes’ hedging, working-capital timing, and near-term contract marks must reprice under higher oil volatility.
2026-07-29
2026-07-27
Baker Hughes's backlog is growing—but it doesn't yet prove LNG is more durable than oilfield services
Baker Hughes ended 1Q26 with $36.1B of remaining performance obligations (RPO), including $33.1B in industrial-and-energy technology (IET)—yet the company does not disclose a backlog “duration” metric in the primary filings we reviewed. That means investors still have to validate how much of the LNG-weighted backlog converts into revenue on a timeline that actually beats oilfield-services cyclicality.
Baker Hughes’ LNG backlog looks like a counter-cyclical shock absorber—Q2 shows $37.1B IET RPO even as oil drilling economics soften
Baker Hughes’ latest filings show IET orders and remaining performance obligations (RPO/backlog) staying elevated through mid-2026, with IET RPO reaching record levels. That matters for the oilfield-service cycle because backlog visibility can mute crude-driven demand swings—but the oil rig count still provides an early warning that oil jobs can fade faster than LNG projects book.
Fed’s “Two‑Shock” Setup Doesn’t Just Move Oil—It Decides Whether Banks Get a Rate‑Cut Tailwind or Stay Discounted Under 3.5% Inflation
A weekend pause in US strikes on Iran drove a ~4% daily drop in WTI and ~4% in Brent, creating a near-term inflation relief impulse. But the Fed’s latest 2026 PCE inflation path still clusters around the high‑3s, so the key repricing question is whether policymakers treat oil relief as “transitory” or as another reason to keep rates restrictive—through this lens, banks and energy market dynamics diverge quickly.
Oil’s “Good News” Slide: US–Iran De-Escalation Cut WTI/Brent ~5%—and It Makes Rate-Cut, Airline-Fare, and Refining-Margin Calls Move in Reverse
A fresh US–Iran de-escalation triggered a rapid ~5% crude unwind, treating geopolitical risk as if it can disappear overnight. That “symmetric premium” is a direct problem for the usual playbook: it pressures near-term airline fuel-expense expectations and cracks refine-margin assumptions while simultaneously shifting Fed-rate odds faster than typical macro signals.
The SPR at 1983 Levels Makes the “$20 Refill” Argument Irreversible—Until Congress Restores a National-Security Buffer
With the U.S. Strategic Petroleum Reserve reported at 311.4M barrels—the lowest since March 1983—the policy debate stops being about price timing and becomes about survivability: there’s less reserve left to absorb shocks. The key investment implication is that oil-market “volatility hedges” (crude producers and refiners with inventory optionality) start mattering more than incremental downstream demand, because refill delays turn SPR capacity into a macro risk premium.
2026-07-26
2026-07-24
2026-07-23
American’s fuel-cost warning matters because airline cash flow is the shock absorber—and it just looks too thin
When American Airlines Group warns that fuel costs can overwhelm margin improvements, the market shouldn’t just model weaker earnings—it should also model weaker operating cash generation. Using AAL financial statements, we show how small earnings-quality shifts can translate into a disproportionate free-cash-flow hit, which then raises industry-wide funding pressure and makes fare “pass-through” less timely than investors assume.
GE Vernova GEV Backlog Confirms Electrification Demand—but Margins and Cash Timing Depend on What Gets Built, Not What’s Booked
GE Vernova’s June 30, 2026 backlog rose to $176.3B and its Electrification backlog to $44.6B (+30% sequential), giving investors unusually concrete evidence that utility electrification capex is still translating into orders. But the profit map is changing: near-term margins and working capital are driven by execution timing, segment mix, and “order-to-revenue” conversion rather than backlog level alone. The backlog can be a demand canary—yet it can still mislead on margin durability if the incremental dollars skew toward slower-to-earn projects or higher execution risk.
GE Vernova’s Backlog Is Strong—but the “Margin Leakage” Risk Lives in Equipment Mix and Execution-Cost Timing, Not Demand
GE Vernova reports a growing electrification and grid backlog (RPO) of $44.6B, but the backlog’s margin quality depends on equipment-vs-services mix and how execution costs and timelines hit project-level contracts. In its latest filings, GE Vernova shows large RPO growth concentrated in Power and Electrification equipment (where schedule and cost overruns matter most), while it separately flags tangible cost/timeline pressure in other execution-heavy businesses—an investor analogue for what can go wrong. The actionable takeaway: treat backlog growth as necessary proof of demand, and backlog composition + disclosed execution risks as the real predictor of margin and cash-flow outcomes.
Treasury’s Iran sanctions repricing is a term-premium shock in disguise—watch how oil risk leaks into rates, dollar funding, and credit hedges before CPI
The July 2026 Iran sanctions cycle is not just an oil story: market pricing implies a higher embedded “energy risk premium,” which then spills into Treasury term premium and the macro risk register. The investable implication is hedge selection—duration and curve hedges may outperform purely commodity hedges early, while FX and credit hedges are likely to require faster, more conditional trigger rules.
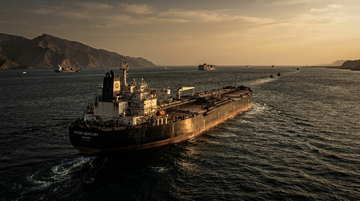
Oil’s “six-week high” is often a shipping-risk repricing: the payoff belongs to tankers and margin-flex refiners, not to everyone holding crude
When Middle East shipping risk rises, part of the crude move is a time-spread shipping-and-uncertainty premium rather than pure physical tightness. That distinction changes who wins: oil-product margins at refiners like Valero Energy and Marathon Petroleum can benefit if product spreads widen faster than feedstock, while airlines such as Delta Air Lines face asymmetric fuel-cost pressure. Conversely, tanker owners like Frontline and Scorpio Tankers tend to capture a more direct shipping-risk revenue pass-through—if the premium persists into the next charter/freight cycles.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.