Energy
Crude, refining and the price at the pump
Supply, inventories, crack spreads and OPEC decisions, followed down to the producers, refiners and buyers who book the difference.
2026-08-19

2026-08-18
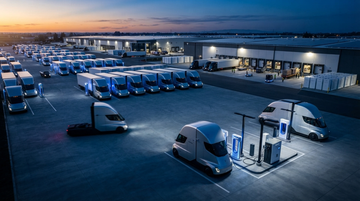
Tesla's non-auto truck bet gets a real fleet test: Einride's 500-Semi rollout targets September 2026 start
Einride says it will deploy 500 Tesla Semi trucks across North America on its Saga AI platform starting in September 2026. For investors, the order is less about near-term vehicle volume and more about whether electric trucking economics can clear a full fleet TCO hurdle—while also stress-testing Tesla's non-auto revenue mix and charging-related capex needs.
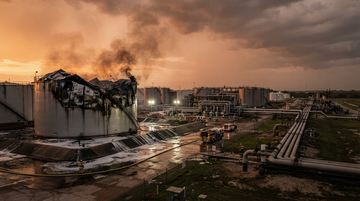
Lightning Tore Through a US Fuel “Bottleneck” — and Crack-Spread Trades Now Have a Physical Supply Shock Washington Didn’t Model
A lightning-triggered fire at the Explorer Pipeline Glenpool tank farm in Oklahoma forced operations to shut and is now tightening refined-product supply logistics on a key pipeline corridor. For crack-spread trades, the implication is simple: even if Washington caps “refinery output” expectations, physical downtime at storage/transport nodes can still move forward the timing (and size) of product shortages that widen differentials.
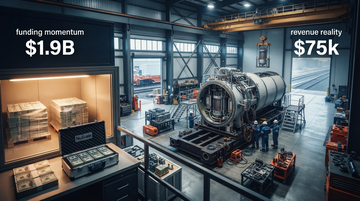
NuScale Power revenue barely exists—while liquidity swells, and the timing matters more than the narrative
In NuScale Power’s Q2 2026 results, revenue totaled just $75k for the quarter while cash, cash equivalents, and investments rose to $1.9B—an extreme mismatch that forces investors to separate “funding momentum” from “revenue reality.” The filing ties the year-over-year revenue plunge to completed Fluor FEED Phase 2 work in late 2025 and the absence of comparable 2026 activity, not a broken business model at every moment; but it still shows that the SMR economics are pacing far behind the AI power-demand storyline.
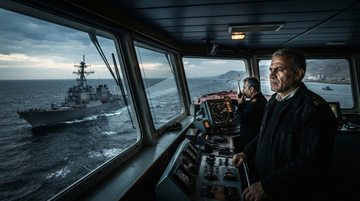
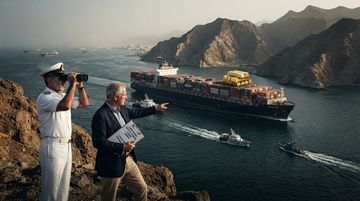
Ceasefire expiry flips the “fade” trade: oil lifts back toward $85 as term premium and shipping risk reprice
When the U.S.–Iran ceasefire looked set to expire on Monday, policy language tilted toward coercive pressure and Iran signaled a harder posture—pushing oil and yields higher. The trade implication is not just crude sensitivity: airlines, margin-flex refiners, tanker operators, and long-duration equity exposures can whipsaw as term premium and freight risk re-price before the market regains direction.
Washington’s “more refinery output” push just set a ceiling on the crack-spread trade
Energy Secretary Chris Wright said the U.S. will announce steps within days to help refiners boost fuel output. When policymakers target throughput, the usual winners are volume/working-capital operators—and the usual losers are refiners’ margin flexibility that depends on tight product markets, especially during record crack spreads.
2026-08-17
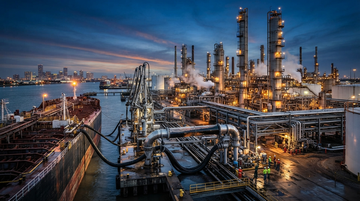
Chevron’s Aug 17 OFAC license step adds heavy barrels back—forcing a new U.S. Gulf Coast refining-margin test
An OFAC amendment released Aug 3, 2026 makes Chevron’s Venezuela-linked authorization operative on or after Sept. 17, 2026—raising the odds that heavy Venezuelan crude availability (and its refining economics) moves from headline risk to measurable margin impact. For investors, the key question is whether the restarted heavy flows are large/steady enough to tighten U.S. Gulf Coast heavy differentials and lift refiners’ realizations, without reintroducing political delivery risk.
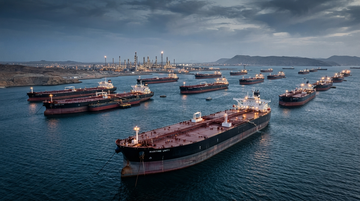
Crude can stay near $82 while Hormuz convoys slow—because the tape is priced by global balances, not one strait
Even with renewed tanker attacks around the Strait of Hormuz and stalled US–Iran talks, crude can trade in a “calm” range when markets believe supply buffers and demand destruction are doing the heavy lifting. Investors should watch for the moment the disruption shows up in inventories, freight/insurance spreads, and refinery throughput rather than in headlines—because that’s when US-listed shipping-linked names and refiners tend to re-price.
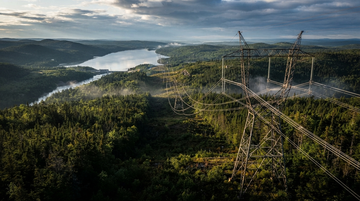
Hydro-Québec and Newfoundland lock in firm hydro for the U.S. Northeast—at a price that forces utilities to model higher “AI firm-power” costs
A new Hydro-Québec–Newfoundland and Labrador Churchill Falls framework would replace the old 1969 economics with a much higher long-term effective purchase price and a defined path to deliver up to 985 MW of firm transmission capacity through Quebec to U.S. markets. For power buyers chasing AI-driven reliability, the deal matters less as headlines about volume and more as a supply-side pricing signal that can tighten what “firm” gets priced like.
2026-08-16
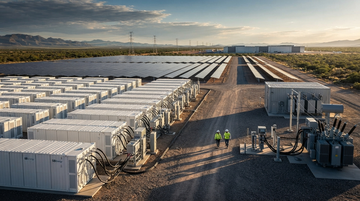
Nvidia’s $3B SB Energy bet highlights the missing “grid-firming” link in AI power
Nvidia’s reported move to invest up to $3B into SB Energy underscores that AI data-center growth is constrained less by chips than by 24/7 power availability. The real supply-chain margin sits in grid-scale storage, power-electronics, and fast interconnection—areas where equipment and energy-storage firms can see order-flow spillover once projects lock fuel (or storage) and transmission timelines.
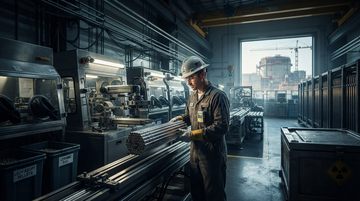
AI data-center power demand isn’t choking reactor builds—fuel-cycle bottlenecks are tightening uranium-to-fabrication capacity
The hyperscaler PPA wave is being stress-tested by the slowest part of the nuclear supply chain: the front-end fuel cycle. ConverDyn-scale conversion, enrichment capacity, and downstream fuel fabrication are the binding constraints on when new megawatts can actually produce—turning uranium, enrichment, and fuel makers into the margin hinge for AI-linked deployments.
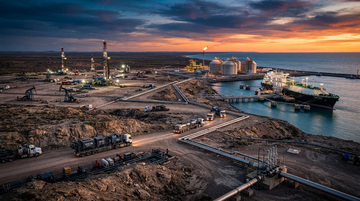
Thiel’s 1% Vaca Muerta stake reframes global gas: Argentina is trying to graduate from “energy chance” to LNG rival
Peter Thiel’s 1% filing stake in Vista Energy turns Vaca Muerta from a niche Latin shale story into an investor-recognizable gas-export bet. The key read-through for US E&Ps is that the marginal “next shale” may be Argentina for LNG-linked timelines, while the near-term winners are companies that can convert unconventional output into export-grade barrels fast.
2026-08-15
2026-08-14
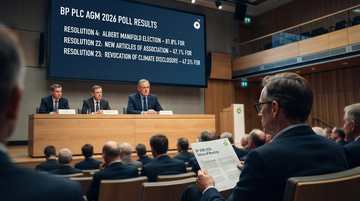
BP’s AGM vote didn’t just reject resolutions—it pressured the company to defend its climate governance and capital discipline trade-off in front of the market
At BP’s AGM on 23 April 2026, shareholders rejected three key contested items (resolutions 22, 23, and 24), including moves tied to climate disclosure and project-level reporting. The pattern matters for investors because it tests whether BP can keep funding shareholder returns while simplifying governance—without losing the institutional consensus that supports supermajor capital-return frameworks.
The market just priced the Iran oil-shock “fade.” The US plan due next week re-prices the term premium—and shipping risk—before crude ever fully turns
A White House “economic isolation” approach for Iran—paired with continued pressure at Hormuz—reintroduces an anxiety channel the market already tried to dismiss: higher risk premia in rates and energy transportation costs. The immediate trade is less about another WTI headline and more about whether financial isolation again makes future barrels costlier to move and insure.
2026-08-13
2026-08-12
2026-08-11
Alpha Compute’s Pennsylvania play reframes the AI data-center bottleneck: buying gas rights to beat the power queue
Alpha Compute ALP reportedly plans to buy Pennsylvania land plus gas rights to anchor a 55MW AI data-center campus—an unusually fuel-first approach to a project pipeline dominated by utility interconnect timelines. If the gas-rights control is real and bankable, it shifts “site control” from the grid side to the upstream fuel side, tightening the link between midstream gas operators and data-center power buildouts.
Trump extended the Jones Act waiver—but the narrow “case-by-case” change shifts who benefits from US coastal fuel trade
The 90-day extension keeps foreign-flag ships eligible to move certain energy commodities between US ports, but it replaces blanket access with voyage-by-voyage review. That design reduces broad “market-wide” arbitrage benefits while still easing the specific shipping bottlenecks driving US fuel-cost pressure.
Western Gateway’s $5B midstream bet: Kinder Morgan and Phillips 66 lock in the West Coast refined-products corridor while HF Sinclair pays for capacity certainty
Phillips 66, Kinder Morgan, and HF Sinclair have finalized the $5B Western Gateway refined-products pipeline, including a reversal of existing assets and a new-build Borger, Texas-to-Phoenix segment. The project is structured around long-term contracted economics (primarily ~10-year take-or-pay), which shifts the West Coast refined-products logistics moat toward these three sponsors and reduces merchant exposure during a tariff/refining-margin regime. Investors should track how quickly the corridor monetizes the 230,000 bpd design capacity and whether completion risk stays on track for mid-2029.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.