Energy
Crude, refining and the price at the pump
Supply, inventories, crack spreads and OPEC decisions, followed down to the producers, refiners and buyers who book the difference.
2026-09-06

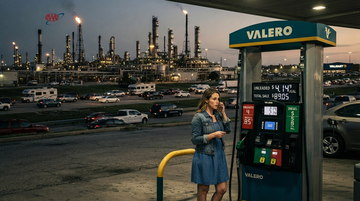
Three Refiners Just Pocketed $12.6B as the Pump Set a Labor Day Record — The Windfall Won't Fade Before November
AAA' national average of $4.14 a gallon on Labor Day weekend — the first holiday above $4 in U.S. history — and diesel at a record $5.85 are not a consumer blip. They reflect a refining margin boom that handed Valero, Marathon Petroleum, and Phillips 66 a combined $12.6B in Q2 2026, with the diesel crack spread breaching $100 a barrel for the first time. With U.S. refineries at 98% utilization, WTI parked near $90 on Iran risk, and an FOMC that just voted 9–3 against holding easy, the political pressure for cheaper gas collides with a structural margin floor that should keep refiners printing cash through the midterms — and squeeze Walmart and the rest of the consumer-discretionary complex in the process.
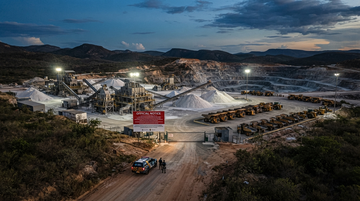
Sigma Lithium just lost its Brazilian permits again — and the ruling exposes who really wins in a Western lithium cycle
On September 5, 2026, a Brazilian court suspended every environmental permit for Sigma Lithium's Grota do Cirilo mine, the fourth legal shock in eight months, even as Albemarle's Q2 print revalidated the lithium cycle and the DFC funnels billions into Western-miner alternatives. The ruling doesn't move global tonnes meaningfully, but it re-prices Brazilian jurisdiction risk inside a market that has spent a year betting on policy-backed US supply: Sigma Lithium trades at a discount for the right reason, Albemarle and Lithium Americas collect the spread, and downstream battery makers face a louder case for sourcing from DFC-aligned projects.
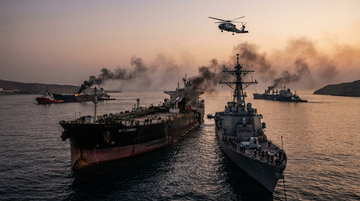
Missiles on Warships, Missiles on Tankers: Why War-Risk Insurance — Not Crude — Breaks First
An IRGC ballistic-missile launch at two U.S. warships on Sept 5 triggered CENTCOM strikes that disabled three Iranian shadow-fleet tankers — the M/T Downy, Stark 1 and Kylo — under a new 'tanker-for-tanker' doctrine. The first market to break isn't Brent, which has plateaued near $95/bbl; it's war-risk insurance, already at 7.5-10% of hull value after a 40-fold rise from pre-war levels, against a Lloyd's consortium capacity of just $400M. Listed VLCC pure-plays Frontline, DHT Holdings and International Seaways sit on the right side of the freight squeeze; defense names from Lockheed Martin to Northrop Grumman get a secondary bid as Iran tests the U.S. Navy's Aegis air-defense envelope.
2026-09-05
2026-09-04
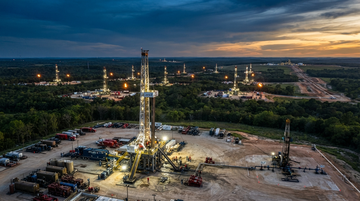
Apex runs more rigs than any other Haynesville operator — and Citadel owns it
When Ken Griffin's Citadel paid $1.2B for Paloma Natural Gas in March 2025, it became the first major hedge fund to run a US shale E&P at scale. Eighteen months later, Apex Natural Gas runs 14 Haynesville rigs, lifted production from 600 MMcf/d to 1.4 Bcf/d in a single winter, and drove more than half of the basin's 2 Bcf/d of growth since October 2025. The thesis: financial buyers can now set M&A multiples for US natural gas — Comstock Resources cashed out its Shelby Trough position to Apex for $430M within a year — and the midstream response is already in the billions, with Williams Companies closing a $5.5B acquisition of Momentum Midstream on Sept. 3, 2026.
US operational control over Venezuela’s oil moves the China-crude bottleneck to Beijing’s balance sheet
A Sep. 4, 2026 step by the US to control Venezuelan oil exports tightens the link between crude supply and PDVSA’s payment mechanics, threatening China’s ability to keep receiving cargoes and recycling proceeds into debt service. The immediate market question becomes which downstream buyers and refiners absorb the rerouted heavy barrels—and which capital structures face the largest working-capital stress.
2026-09-02
Sep. 2 broke the “resilience” script: 10-year yields hit 2026’s top zone while earnings-season support ended and oil surged
On Sep. 2, the US reignited direct hostilities with Iran as the 10-year Treasury yield pushed to its highest level since Nov. 2023, while crude prices firmed after the conflict flare-up. With the Q2 earnings window effectively done and buyback blackouts typically starting, investors lose two key sources of dip-buying support just as the market’s discount-rate sensitivity returns.
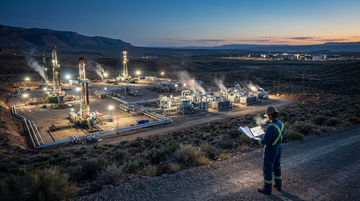
Fervo’s 396 MW Google PPA turns geothermal into an AI-grade “24/7” contract test—without proving the margin math yet
Fervo FRVO spiked on Sept. 1 after announcing a 396 MW enhanced-geothermal power purchase agreement with GOOG for its Cape Station GeoCluster, targeted to come online in 2028 and expandable to nearly 1 GW by June 2030. The market is treating that contract as a commercialization signal for the drill-to-ORC-to-PPA supply chain—yet Fervo’s latest financials still show revenue at the hundreds of thousands and negative operating cash flow, so any “AI multiple” is being priced ahead of repeatable cost and margin delivery.
2026-09-01
CME’s ERCOT Power Futures Go Live: The AI-Load Hedge Finally Has a Texas Price Signal
CME started trading ERCOT power futures and options on Aug. 31, 2026, bringing exchange-listed hedging to the exact node-to-bill signal that drives Texas scarcity economics. For investors, the new contract surface turns a previously “opaque” risk channel into something easier to price, trade, and compare—raising the odds that AI-driven load demand (and its scarcity episodes) shows up in market-implied hedging costs before it shows up in generator stocks.
India’s “Urals stop-buy” risk: when a 100% secondary-tariff threat forces discount crude to reprice—tankers, refiners, and the diesel balance sheet
Washington’s 100% secondary-tariff threat on buyers of Russian oil turns energy sourcing into a live diplomatic lever for India. The shift matters because Urals discounts don’t just move barrel economics; they change the whole logistics stack and the regional product balance, where refinery runs, product spreads, and vessel earnings can move in the same quarters.
Texas’s AI “scarcity rent” is being earned inside merchant P&Ls — not paid for by customers that think they’re buying power
In ERCOT, the AI/data-center load wave doesn’t just raise prices—it shifts upside into the merchant stack with high hedge coverage. Vistra shows the core mechanic: when it hedges ~100% of 2026 volumes but only ~94% of 2027, the timing and roll risk of scarcity rent can dominate results even if generation economics look strong on the surface.
2026-08-31
Oil back above $90 after a fresh strike on Iran—yet stocks barely blink: the market is pricing “duration,” not direction
A U.S. strike on Iran’s Larak Island helped lift Brent crude back above $90, but equity risk gauges stayed subdued and traders leaned toward a September hike odds shifting rather than a full-blown recession shock. The key difference is that the market appears to be treating the latest escalation as a near-term supply “headline” while assuming the Fed’s path (and risk appetite) won’t reprice materially unless disruption looks prolonged.
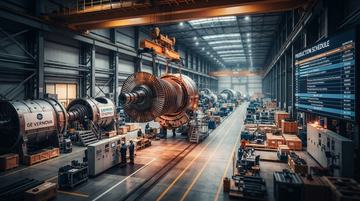
The gas-turbine order book is turning hyperscaler power into a timing bet—OEM slots beat permits by 2027
GE Vernova and Siemens Energy are sitting on huge gas-turbine backlogs while AI-era demand is colliding with unusually tight delivery slots. But the binding constraint for getting megawatts online by 2027 is turning from turbine manufacturing capacity into emissions/permitting sequencing—where delays can strand already-ordered equipment and shift revenue capture toward OEMs with the longest order visibility.
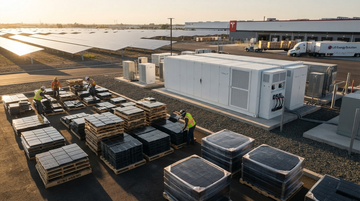
Tesla's Solar Roof exit is a confession, not a setback — it killed 0.17% of US residential solar to free up the energy segment that actually scales
After a decade and roughly 3,000 installed systems, Tesla quietly told certified installers in mid-August 2026 it will stop supplying Solar Roof tiles and only sell conventional panels going forward. The retreat is small in unit terms but huge as a signal: Tesla's energy segment — now a $12.77B business at a 29.8% gross margin in FY2025 — is Megapack-led, not roof-tile-led, and the $240M Q2 warranty true-up shows what custom-manufactured products cost when they don't scale. The move tightens the moat around utility-scale storage, validates Enphase and SolarEdge as the inverter standard for the rest of residential solar, and hands roof-replacement economics back to traditional players like Sunrun and the legacy installer base — while LG Energy Solution collects a $4.3B tailwind from the Megapack cell deal.
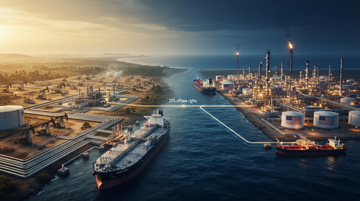
Washington turns sanctions into state shareholding: a 35% equity stake and 20% offtake rights in Venezuela could rewrite Chevron’s barrel math
The U.S. is moving from restrictions to direct economic ownership in Venezuela, seeking a 35% stake in North American Blue Energy Partners alongside preferential rights to buy 20% of production under a 25-year framework targeting more than 1.5 million bpd. If the deal’s throughput materializes, it strengthens the U.S. margin capture link from upstream barrels to Gulf Coast refiners—while forcing investors to reassess how quickly Venezuelan supply can be “made bankable” for U.S. counterparties.
2026-08-30
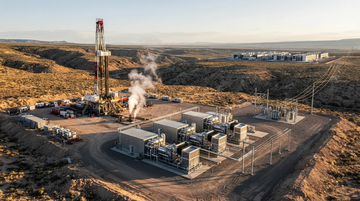
AI’s 24/7 power sprint just found a missing supply-chain map: geothermal’s drill-to-ORC-to-PPA chain
Fervo Energy is converting geothermal from “pilot projects” into bankable 24/7 capacity for AI and data centers—by locking megawatts in PPAs and then moving fast through drilling, permitting, and Organic Rankine Cycle (ORC) equipment. That creates a measurable, investable supply-chain pattern: drill capacity that delivers contracted MW on schedule, ORC turbine/generator OEM scope that scales, and utility-grade offtake economics that are designed to survive the interconnect clock.
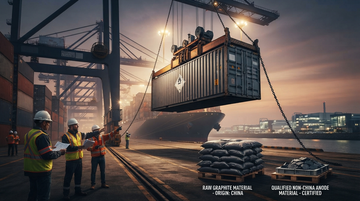
Graphite anodes just became the EV-and-storage bottleneck—because the U.S. tariff/export-control regime targets the active-anode link
The binding constraint in the lithium-ion supply chain is shifting from headlines about lithium to the graphite anode value chain—where China’s processing dominance collides with U.S. trade enforcement. A February 17, 2026 Commerce dumping determination for “active anode material from China” sets estimated weighted-average dumping margins at 93.50% (and 102.72% for the China-wide rate), making non-China qualification and contracting the near-term scramble for EV and grid-storage developers.
Venezuela’s potential OPEC exit meets a fading Brent—if quotas never mattered, the “cartel test” becomes who buys the marginal barrel
Venezuela is reportedly considering leaving OPEC as U.S.-backed access to its oil expands, but the quota mechanics matter less than the market’s new swing factor: excess supply discipline vs. marginal-buyer power as Brent slides. The cleanest investor takeaway is that the market share battle after an exit would not be about “freeing barrels” that were already exempt, but about who captures additional volumes when OPEC’s signaling weakens.
2026-08-29
2026-08-27
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.