Latest
The day's market news, with the argument attached
New notes every trading day on earnings, policy and market structure. Each one opens with the conclusion, then the evidence, then the companies it hits.
2026-07-16

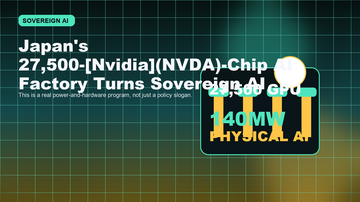
Japan's 27,500-Nvidia-Chip AI Factory Turns Sovereign AI Into Hard Capex
Japan's AI push is no longer abstract. It has a chip count, a 140MW power budget, and a 2028 deployment target, which makes it look like real infrastructure rather than a slogan.

J.B. Hunt Transport (JBHT) Q2 2026 EPS $1.73 Beat + Stock +7% After-Hours - The Bellwether for the US Freight Cycle Turn
J.B. Hunt Transport (JBHT) reported Q2 2026 EPS of $1.73 vs. consensus $1.55 (~12% beat) and revenue of $3.5B vs. $3.25B consensus (~8% beat) on July 15, 2026, with stock +7% post-close. The signal: the US freight cycle has decisively turned after the 2023-2024 freight recession. The read-through is for FDX, UPS, XPO, CHRW, and the broader US freight + logistics + intermodal cycle.

Eli Lilly Acquires AtaiBeckley for $2.8B - The First Big Pharma Validation of the Clinical-Stage Psychedelics Pipeline
CNBC reported on July 16, 2026 that Eli Lilly has agreed to acquire psychedelics maker AtaiBeckley (ATAI) for $2.8B upfront ($6.75/share, 26% premium) plus up to $1B in contingent value rights tied to development/regulatory milestones, for a total deal value of up to $3.8B. The lead asset is BPL-003 - a DMT-derived intranasal spray in Phase 3 for treatment-resistant depression (TRD) with ~2-hour in-clinic administration.

Truist Downgrades Lululemon (LULU) to Sell with $94 PT - The 4th Sell-Side Cut in 6 Weeks Validates the Premium-Discretionary Bear Case
Truist Securities analyst Joseph Civello downgraded Lululemon (LULU) to Sell from Hold on July 16, 2026, with a price target of $94 (down from $115, ~21% downside). FY26 EPS cut to $10.50 (from $11.25, -7%) and FY27 EPS cut to $10.25 (from $11.75, -13%). This is the 4th sell-side cut in 6 weeks. New CEO Heidi O'Neill (ex-NKE) starts September 2026. The read-through: long COST + WMT + TGT + TJX + ROST + BURL + FIVE + OLLI, short LULU + NKE + ONON + GPS + ANF + AEO + URBN.
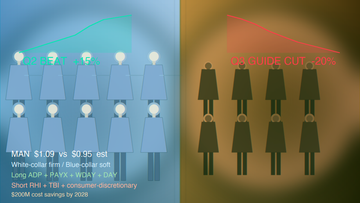
ManpowerGroup (MAN) Q2 2026 Beat + Q3 Guide Cut - The Real-Time Labor Market Signal That the 2026 Consumer-Discretionary + Consumer-Staples Cycle Is Bifurcating
ManpowerGroup (MAN) reported Q2 2026 EPS of $1.09 vs. consensus $0.95 (~15% beat) and revenue of $4.7B vs. $4.5B consensus, but cut Q3 2026 EPS guidance to ~$0.80 vs consensus $1.00 (~20% cut). The signal: the labor market is bifurcating - white-collar staffing is firm, but blue-collar + industrial + light-industrial staffing is decelerating. The read-through is for short consumer-discretionary + long consumer-staples + long HR tech + long payroll cycle.
Morgan Stanley's Record Wealth Flows Turn the IPO Boom Into a Fee Machine
Morgan Stanley's second quarter showed that the bank is no longer just trading a volatile tape. It is converting IPO and M&A activity into durable wealth assets, and the scale of those inflows says the fee cycle still has room to run.

Nvidia Unveils Cosmos 3 Edge + Expands Japan Physical AI Ecosystem - The Cleanest Single Pivot from AI for Chatbots to AI for the Physical Economy
CNBC reported on July 16, 2026 that Nvidia unveiled Cosmos 3 Edge - a foundation model for robotics and vision AI agents - during Jensen Huang's two-day Japan visit. The launch is accompanied by industrial partnerships with Fujitsu, Hitachi, and Kawasaki Heavy Industries, plus a healthcare/bio expansion into Astellas Pharma, Daiichi Sankyo, and Ono Pharmaceutical via the BioNeMo drug-discovery toolkit.
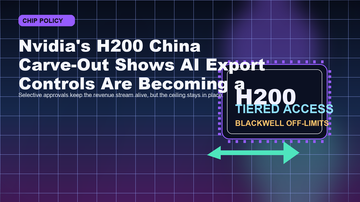
Nvidia's H200 China Carve-Out Shows AI Export Controls Are Becoming a Tiered Market
The latest H200 approvals do not reopen China. They make the AI chip war more granular: chip generation, named buyers, and compliance burden now define the market.
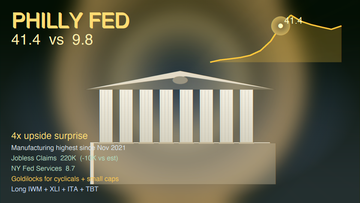
Philly Fed Manufacturing Surges to 41.4 vs. 9.8 Consensus - The 4x Upside Surprise Is the Goldilocks Confirmation for the 2026 Manufacturing + US-Exceptionalism Cycle
The Philadelphia Fed Manufacturing Index surged to 41.4 in July 2026, vs. consensus 9.8 (~4x upside surprise), the highest since November 2021. New orders, shipments, and employment all accelerated. Combined with jobless claims at 220K (-10K vs consensus) and a softer Retail Sales print (-0.2% MoM ex-autos), this is the cleanest goldilocks setup for the 2026 manufacturing + US-exceptionalism cycle. The read-through is for cyclicals + short duration + small caps.
June Retail Sales Rose 0.2%, but the Real Signal Is a Split Consumer and a Fed That Still Cannot Relax
U.S. retail sales increased 0.2% in June, while ex-gas sales rose 0.7% and the control group gained 0.5%. The soft headline looks like consumer cooling, but the details say something more useful: spending is shifting, gas is masking strength, and the Fed still has to decide whether resilient demand or softer inflation is the bigger risk.
SK Hynix's U.S. ADR Premium Says HBM Scarcity Is Being Priced in Dollars, Not Won
The premium on SK Hynix's U.S. listing is too large to call convenience. It is the market pricing scarcity, convertibility, and direct HBM access at the same time.
South Korea's AI Chip Boom Hit a Leverage Wall as SK Hynix and Samsung Electronics Drag the KOSPI Into a Bear Market
The July 16 selloff did not break AI memory demand. It exposed how crowded the trade had become after months of leverage, retail momentum, and rate-sensitive positioning.
Truth API Turns Trump Media Into a Market-Data Toll Booth - and That Changes the Incentives for Anyone Trading on Truth Social
Trump Media said it will launch Truth API, a licensed real-time feed of top Truth Social accounts for financial institutions. The obvious read is monetization. The deeper read is that the company is trying to turn political attention into a data product, which creates a new market structure risk for traders who already rely on Truth Social as an information source.
Uber Agrees to Buy Delivery Hero for $14.8B - The Largest Cross-Border Food Delivery Deal in History and the Cleanest Single Consolidation Catalyst for the Global Online Food Delivery Duopoly
Investor's Business Daily reported on July 16, 2026 that Uber Technologies has agreed to acquire Berlin-based food-delivery peer Delivery Hero SE for $14.8B in cash + stock, in Uber's largest cross-border deal to date. The combined entity will have ~70 countries, ~40M+ monthly active eaters, and GMV scale approaching $200B run-rate. The deal hands Uber Eats clear #1 share in the Middle East, Japan, Korea, and Latin America, areas where Uber Eats has been sub-scale. The acquisition is the cleanest single most direct 2026 food delivery consolidation catalyst.
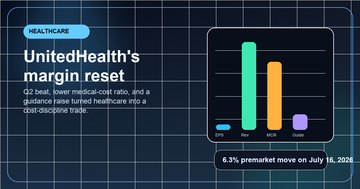
UnitedHealth's 86.7% Medical-Cost Ratio Turned a Healthcare Beat Into a Margin-Discipline Trade
UnitedHealth reported second-quarter 2026 adjusted earnings per share of $6.38 on $112.0 billion of revenue, lowered its medical-cost ratio to 86.7%, and raised full-year adjusted EPS guidance to $19.50-$20.00. The market reaction was immediate, but the real signal is that management is now prioritizing pricing discipline, mix, and cost control over top-line optics. That changes the read-through for managed care peers and for the healthcare sector's place in the July 16 tape.
Verizon's 3,000-Job Restructure Turns Telecom Coverage Into an Operating-Leverage Test
Verizon's latest layoff round and store divestiture are not just cost cutting. They show how Verizon is trying to turn a slow-growth wireless franchise into a higher-margin distribution machine while the carrier wars, retail footprint, and AI-driven customer-service automation all reset at once.
2026-07-15
ASML Raised Guidance Again Because EUV Capacity Is Still the Binding Constraint in the AI Chip Cycle
ASML reported Q2 2026 net sales of €9.3 billion and net income of €2.9 billion, then raised 2026 sales guidance to €43-45 billion and gross-margin guidance to 54%-56%. The company also said it plans to add 30% to low-NA EUV capacity in 2027 and may add another 30% in 2028, which is the cleanest proof that the AI chip cycle is still constrained by lithography, not demand. The read-through reaches TSMC, Samsung Electronics, Intel, Nvidia, Micron, Applied Materials, Lam Research, and KLA.
Australia's New AI Data-Center Rules Turn Power and Water Into the Next AI Capex Tax
Australia's July 15-16, 2026 policy shift says large AI data centers must secure their own power, cover their connection costs, manage peak-load behavior, and use water efficiently. The headline is about regulation, but the real message is capital discipline: AI infrastructure is no longer just a software or hardware spend, it is a grid, water, and permitting problem. That matters for Vertiv, Eaton, Equinix, Digital Realty, and every hyperscaler trying to scale demand without colliding with local utility politics.
BlackRock Crossing $15.3 Trillion AUM Turns Passive Flows Into the Real Market-Structure Trade
BlackRock reported Q2 2026 adjusted EPS of $13.91, revenue of $7.084 billion, and $15.3 trillion of assets under management after $192 billion of second-quarter net inflows and $321 billion in first-half inflows. The headline matters because it shows how equity beta, ETF dominance, and private-markets expansion are feeding the same fee engine. The stock's move was just the first-order reaction; the deeper read-through runs to State Street, Charles Schwab, KKR, Blackstone, and the active-vs-passive balance across the asset-management complex.
China's 4.3% Q2 GDP Reopened the Beijing Stimulus Trade — And the Nvidia H200 Path With It
China's Q2 2026 GDP printed 4.3% year-over-year, the weakest since Q4 2022 and below Beijing's 4.5%-5% full-year target. Real estate investment fell 18%, fixed-asset investment dropped 5.7% in H1, but industrial output rose 5.3% and retail sales rebounded to +1% from a -0.6% reading in May. The combination forced Beijing into a third-quarter policy-easing stance, which markets priced through China tech, the yuan, and a quiet re-rating of Nvidia on H200 export hopes. Alibaba, Tencent, PDD Holdings, BYD, and the China-exposed cyclicals all move with this trade.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.