Latest
The day's market news, with the argument attached
New notes every trading day on earnings, policy and market structure. Each one opens with the conclusion, then the evidence, then the companies it hits.
2026-08-24

EPA’s Sept. 1 RFS deadline delay rewires the margin trade between refiners and ethanol—turning late-August SRE decisions into the real price catalyst for RIN-linked cashflows
EPA confirmed it is issuing decisions on small refinery exemption petitions and has maintained a Sept. 1 compliance deadline framework for 2025 RFS obligations—creating a near-term timing window where RIN prices can move sharply on policy certainty. For obligated refiners such as Valero, Marathon Petroleum, PBF Energy, and Phillips 66, that timing directly affects the cost of meeting renewable volume obligations, while for ethanol-linked credit holders it can swing expected cash margins.
Europe’s EV share above 25% makes the “demand split” real—while the U.S. stalls
Europe’s July EV momentum marks a demand milestone at >25% of new-car registrations, tightening the linkage between EV volume growth and downstream winners in batteries and charging. With U.S. EV share stuck around the low-single digits (and July sales down ~41% YoY), the market’s relative-demand math now favors firms levered to Europe’s next wave—and pressures ICE-heavy and “EU-limited” EV strategies.
Evergrande’s sentencing turns the property-debt crisis into a balance-sheet timetable for steel and iron ore
When China sentenced Evergrande’s founder to life in prison and fined connected entities, it didn’t “buy” new apartments—but it did tighten the endgame timeline for how losses are absorbed across lenders and suppliers. The next read-through for markets is not construction demand alone; it is how banks and developers reprice risk and how that propagates into steel output intensity and iron-ore buying behavior.
Exxon’s reported bid for Shell’s U.S. chemicals assets tests the ethane advantage—against a global oversupply that can turn “margin” into a margin trap
Reportedly bidding for Shell’s U.S. chemicals assets would be a strategic shift: Exxon is effectively paying for more integrated cracking capacity at the very moment global petrochemicals risk staying structurally oversupplied. For investors, the key question is whether Exxon can translate U.S. ethane feedstock advantage into durable cash margins—without inheriting the same downcycle volatility that has repeatedly hit global polyolefins.
A $6B Robotics Mark Signals “Embodied AI” Is Becoming a Public-Market Trade, Not a Venture Curiosity
Point72 and Valor-backed funding pressure around General Intuition’s $6B pre-money robotics round marks a fresh institutional inflection: AI investment is shifting from screen-bound models toward robot-ready “general” systems. For public equities, the move sets a clearer valuation benchmark for the embodied-AI exit pipeline—and it spotlights which automation incumbents (and compute suppliers) look most exposed to the next wave of capex.
Grok 4.6 appears inside Google’s Model Garden—xAI just bought enterprise distribution from its biggest cloud rival
When Grok 4.6 was made available through Google’s Model Garden on the Gemini Enterprise Agent Platform, xAI gained a direct enterprise on-ramp via Google Cloud without building its own large-scale channel. For buyers, it shifts the leverage from “who owns the cloud deployment” toward “who owns the model access layer,” tightening the distribution math facing OpenAI and Anthropic.
Who buys Hugging Face at $13B? A consolidation bet that could price “open” out of the distribution layer
A new report says Hugging Face is exploring a sale that could value it at $13B+, but no buyer or deal terms are confirmed yet. The strategic risk is that owning the model hub (and its hosting/inference trust layer) turns today’s “open weight” distribution into a toll-based pipeline—forcing developers, GPU providers, and inference competitors into tighter, paid ecosystems.
Iran sanctions hit—and oil still faded to $92.83: the trade just proved it survives headlines
The latest U.S. Iran sanctions announcement tested the “oil fade” setup and, instead of forcing crude higher, WTI traded down to about $92.83. At the same time, refinery economics strengthened: Ampol’s Lytton refining margin in Q2 jumped to $30.93/bbl (up from $8.71 a year earlier), supporting a cracked-spread divergence that can outlast sanctions-driven headlines.
IREN’s Aug. 27 earnings are the first real “miner-to-AI landlord” stress test after power volatility—and the 10‑Q already shows why margins can’t be treated as fixed
IREN IREN is set to report on Aug. 27, and the pivot story lives or dies on how quickly electricity cost shocks flow through to profitability. In its latest filed results, the company reports electricity as a major cost driver for both bitcoin mining and AI Cloud Services, including earlier history of switching electricity procurement terms at its Childress site—exactly the kind of mechanism that can turn short-term power volatility into margin volatility.
Japan’s long-end auction jitters are tightening the “foreign supply” screw on U.S. Treasuries
A weak pocket in Japan’s long-end bond supply is showing up as a funding-demand headline at the same time the U.S. Treasury is trying to cushion the long-end with larger buybacks. The key question for investors: whether Bessent’s 10- to 30-year containment can offset JGB spillover into global duration risk—without relying on a market that keeps repricing term premium upward.
KPMG Australia’s 5% cut is a Big-4 demand signal—because it happens while AI is compressing billable labor
KPMG Australia says it will cut about 5% of its workforce, affecting 27 partners and around 360 staff, and it warns that “difficult market conditions” may persist into 2027. The setup matters for investors: it coincides with an industry-wide pricing shift where AI reduces the staff-hours needed to deliver the same output—so even modest demand softness can trigger headcount actions faster than revenue trends show up.
Mexico’s “14% Q2” GDP surge is real—but the story is tariff-bloc math, not pure nearshoring momentum
Mexico’s Q2 output rebound is strong enough to validate parts of the nearshoring thesis for North American supply chains, but the magnitude is likely inflated by how tariff blocs (and trade-policy uncertainty) re-route demand. Investors should treat the headline as a signal of re-pricing and production reallocation first, and as a durable growth engine only if USMCA certainty improves.
Napco Security Technologies proves SMB security can stay “hardware-premium” while AI-native software tightens the stack
In its most recent fiscal-quarter disclosures, Napco Security Technologies showed recurring service revenue scaling alongside higher margins, with equipment growth still participating in the mix. The investor question is whether “platform thinking” (software-led security) can compress hardware value—or whether Napco Security Technologies can keep its RMR economics while AI-native features increase attach and renewals.
California is pressuring Paramount-Warner to sell TV cable channels just as the FCC loosened station consolidation—making divestiture terms a moving target for bidders
California Attorney General Rob Bonta is expected to push a settlement remedy that includes divesting certain TV/cable channels in the Paramount–Warner Bros. Discovery deal. With the FCC voting to eliminate the 39% national local-station ownership cap, the bargaining value of any forced station or channel relief shifts—potentially changing what station-group buyers can pay and what price Paramount–WBD must justify to close.
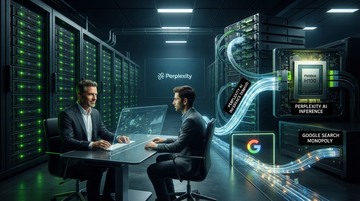
Nvidia’s “equity seat” bid in Perplexity would make $30B+ AI search a compute-powered toll road to Google’s ad machine
Recent reporting says Nvidia is in discussions to invest in a Perplexity funding round that would value the answer-search startup at more than $30B, potentially turning Nvidia’s existing inference relationship into an equity-and-platform lever. If that happens, investors should watch not just Perplexity’s growth, but the first-order supply-chain economics: higher inference demand, faster iteration of model-serving stacks, and a tougher monetization path for Google’s search monopoly as “answer” turns into the default entry point.
Pinecone Nexus beats “frontier-only” agent stacks on enterprise knowledge—suggesting the retrieval layer, not the model, decides whether agents work at scale
Pinecone says its Nexus knowledge layer improved an agent’s performance on Sierra’s τ‑Knowledge enterprise-support benchmark to a 47.4% task-success rate, edging the best frontier model (46.4%) while cutting cost per task by 74%. For enterprise buyers, the implication is architectural: budgets shift from “bigger models” toward governed compilation, retrieval, and on-prem/owned-data deployment patterns.
Bank-charter “deposit war” is accelerating—Tioga-Franklin’s $68M FDIC loss is the warning label for the rush
The FDIC’s record shows a $68.0M (approximate) failure cost tied to Tioga-Franklin Savings Bank, while the OCC has conditionally approved new charters tied to crypto-linked business models—explicitly ruling that certain stablecoins are not FDIC-insured deposits. For incumbents, new bank formation raises the odds of higher deposit competition and funding costs; for investors, the key risk is not charter count, but whether growth banks can match rates without breaking underwriting discipline.
Samsung Electronics record payout stops moving the stock because memory cash returns are now “priced, not proven”
Samsung’s 2026 shareholder-return program is large enough to matter on cash, but investors are treating it as table stakes while they underwrite the next leg of AI/HBM demand. The market reaction fits the new memory playbook: capital returns are no longer the catalyst—unit pricing, HBM share, and capex discipline are.
Shein’s HK IPO pricing at up to $27B confirms the de minimis shock—and shows the “late backers” got marked down the most
Shein’s Hong Kong IPO has priced with a maximum valuation of about $27B, roughly one-third below the previously reported $40B “reset” level. The final print lands after the formal end of U.S. de minimis treatment, a change Shein disclosed as a direct headwind to U.S. net revenues and profitability.
GE Vernova should get a rerating if “steam capacity” stays the next AI power choke point
Reuters reported Siemens Energy is weighing a spin-off (or IPO) and a stepwise stake sale for its “Transformation of Industry” unit, which includes industrial steam turbines. That matters because hyperscaler-driven power buildouts increasingly hinge on steam-side equipment lead times as much as on gas turbine delivery—setting up a valuation read-through to GE Vernova’s power-and-steam franchise.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.