Latest
The day's market news, with the argument attached
New notes every trading day on earnings, policy and market structure. Each one opens with the conclusion, then the evidence, then the companies it hits.
2026-08-23

Germany’s “national champion” veto would reprice bank M&A by blocking the UniCredit–Commerzbank playbook
UniCredit’s bid for Commerzbank is forcing German policymakers to confront a structural problem: the German takeover regime can let an acquirer build a large stake and negotiate from a position of leverage rather than paying through a clean, shareholder-out premium. The reported push to review takeover rules after the bid would raise the cost of crossing control thresholds—changing deal math for cross-border bank combinations and putting EU capital-markets-union timelines under pressure.
Unifor’s GM labor deal hits the wage floor just as 50% Section 338 Canada tariffs snap back
Unifor reached tentative agreements with General Motors for roughly 4,600 Ontario members—resetting Canada’s autoworker wage-and-benefits baseline while the U.S. re-imposes 50% Section 338 tariffs on Canadian goods effective Aug. 19, 2026. For investors, that timing matters: it tightens the margin bridge from tariff-refund timing into a direct test of how quickly GM can offset labor-cost step-ups when trade-based “relief” turns into a cost catalyst again.
Harvard’s $699 AI-avatar bootcamp is a price-discovery strike against “seat-based” education
Harvard Business School’s HBS Foundry bootcamp is priced at $699 and uses HeyGen-made AI avatars to provide feedback during practice pitches and board-meeting simulations. If elite-brand instruction can be unbundled into avatar-led coaching, universities and edtech platforms gain a scalable product surface—while legacy courses face margin compression and higher avatar-IP leverage costs.
HP Inc. is betting on AI-PC refresh timing, but its margins still hinge on memory cost physics
HP Inc. can benefit from the same “personal AI” narrative driving Microsoft, yet its reported segment math shows operating margin at Personal Systems is sensitive to commodity headwinds. The investor question for the Aug 2026 print is whether AI-PC momentum is enough to offset memory/storage cost pressure as HP’s PC portfolio cycles into the next demand window.
When “replicating research” becomes the benchmark, agentic orchestration—not frontier model size—can decide who wins
Inherent’s Faraday claims it can replicate published findings more faithfully than stronger frontier models by framing science replication as a long-horizon, judge-rubric RL problem. If the market starts pricing labs on “verifiable output under constraints,” the competitive moat shifts toward orchestration, tooling discipline, and automated evaluation—not just raw model capability.
Korea’s retail is buying ~40% coupon equity-linked notes after the rout—what that signals for US mega-cap tech demand and structured-credit risk
After Korea’s historic stock rout, retail investors are rotating into complex equity-linked securities that advertise annualised coupons around 40% (and up to ~50%), despite explicit knock-in loss risks. The key takeaway for investors is that the marginal buyer is shifting from “equity direction bets” toward “structured coupon” risk, which can temporarily support mega-cap earnings expectations while quietly extending drawdown risk into credit-like downside paths.
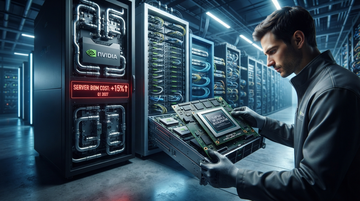
NVIDIA's 15%+ server price hike raises the payoff for custom inference silicon—and reframes who captures AI profit into 2027
NVIDIA’s reported 15%+ AI-server price increases—linked to memory costs—will likely make “build vs. buy” math harder for OEMs and easier for hyperscalers considering custom inference silicon. The underappreciated consequence is that higher platform BOM costs can accelerate ASIC substitution, shifting a bigger share of compute economics toward winners already embedded in custom stacks like Marvell, Broadcom, and hyperscaler-designed accelerators tied to Microsoft.
“Ox Alpha” shows what frontier labs lose when benchmarks outpace attribution
An anonymous “stealth/ox-alpha” model appeared on major AI marketplaces with top-tier coding-task claims but no disclosed builder. For investors tracking OpenAI/Anthropic and adjacent incumbents’ “frontier moat,” the signal is less about who built the model and more about whether distribution, benchmark narratives, and compute availability can outgrow lab-by-lab credibility.
PDD Holdings faces the first full-quarter test of whether Temu can keep winning after de minimis is formally suspended
PDD reports Q2 with the U.S. de minimis administrative exemption suspended for merchandise valued at $800 or less arriving via modes other than international postal—removing the cost advantage that made Temu’s direct-to-consumer cross-border economics work. The quarter’s revenue and margin quality (not just headline growth) should reveal whether Temu can re-route around duties and compliance friction or whether demand elasticity shows up immediately in the numbers.
Regulators shut a Philadelphia savings bank (Aug. 21, 2026): the FDIC’s $68M/ $67M loss math looks small—but the repricing risk may be systemic
On Aug. 21, 2026, the FDIC took over Tioga-Franklin Savings Bank in Philadelphia and the acquirer, Second Federal Savings and Loan Association of Philadelphia, assumed essentially all deposits and substantially all assets; the FDIC preliminarily estimated a $5.5M cost to the Deposit Insurance Fund. The event is tiny in absolute dollars, but it directly illustrates how “higher-for-longer” interest rates can still translate into balance-sheet losses quickly when deposit betas, funding lifecycles, and CRE/asset duration misalign—typically hitting smaller, concentrated franchises first.
Quantum’s next supply chain winner won’t be the “best qubit”—it’ll be the firm that owns the atoms-to-atmosphere stack
DoD, Oracle, and hyperscalers are pulling quantum hardware decisions forward, but the bottleneck is no longer the algorithm—it’s cryogenics (or its absence), trapped-ion control electronics, and the foundry/packaging chain. IonQ’s planned SkyWater acquisition and its $5.7M DoD-backed networked-quantum design work point to a defensible economic play: closing the loop between device physics and manufacturability before the market standardizes.
Snowflake's AI Data Cloud has a consumption math problem—and earnings will show if it can still win on volume
Snowflake monetizes its AI Data Cloud through fees tied to compute, storage, and data transfer consumption, which makes near-term results highly sensitive to actual usage—not just capacity sign-ups. Its latest disclosures show how that model creates forecast volatility, while its Q2 FY2026 and FY2026 guidance anchor the first “consumption conversion” earnings test against expectations set by the private valuation chatter around Databricks.
Ultragenyx's Genglycos wins accelerated approval—but RARE's real proof will be whether manufacturing can keep up
The FDA’s accelerated approval for Ultragenyx’s GENGLYCOS (pariglasgene brecaparvovec-opnr) hinges on a surrogate endpoint—reduced daily cornstarch intake—and requires a multi-year confirmatory study. For investors in Ultragenyx, the near-term upside is straightforward; the hardest part is the regulatory- and quality-controlled ramp: the company must sustain manufacturing, lot release, and long-horizon follow-up across eligible patients as AAV8-antibody constraints shape access.
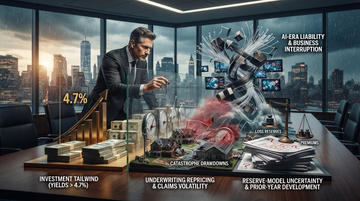
US P&C’s repricing cycle needs more than 4.7% yields: reserve risk, business‑interruption gaps, and AI-era liability determine whether profits convert
For US property & casualty insurers, the investment tailwind from higher long yields can only be “shareholder-accretive” if underwriting repricing is tight enough to offset catastrophe drawdowns, reserve-model uncertainty, and expanding liability exposures. Evidence from filings shows how (1) cat losses and prior-year development can swing results quarter to quarter, and (2) reserve sensitivities can translate small assumption shifts into hundreds of millions of dollars—meaning the rate cycle pays only when both the claims side and the liability side stay inside expectations.
US oil rigs fell for the first time in months while Brent held near $94 — the market is signaling “capital-return discipline” not “price-driven supply,” which tightens the 2027 supply cushion investors are underwriting
The US oil rig count declined for the week ended Aug 21, 2026 even as Brent held close to $94, reinforcing a shift toward shale activity governed more by shareholder capital allocation than by near-term price signals. For investors, the implication is uncomfortable: if drilling does not scale with prices, the 2027 supply balance likely tightens faster than bull-case models that assume a price-responsive drilling ramp.
Vietnam’s customs IP upgrade turns “tariff math” into compliance math for US brands
Vietnam’s newly approved customs-law changes expand IP powers at the border—covering goods in import/export and transit and adding specific rules for e-commerce shipments—starting March 2027. For US brands that have already rerouted supply chains toward Vietnam to protect tariff outcomes, the practical risk shifts from “duty rate only” to higher clearance friction, longer holds, and more grey-market leakage cost that can compress Vietnam-sourced margins.
Zscaler must translate agentic-cyber hype into billings, not just demos
After the broader “agentic cyber” wave showed up in CrowdStrike results via durable billings dynamics, investors are now looking for the same proof in Zscaler. The key question for Zscaler’s late-August reporting is whether its zero-trust + AI security roadmap shows up in quarter-level revenue acceleration and the billings-to-revenue bridge implied by deferred revenue and remaining performance obligations.
2026-08-22
AI credit’s “tourists” are buying the wrong spread—when they exit, the repricing risk lands in BBB-first pockets
The “marginal buyer” in AI-linked credit appears to be shifting from dedicated high-yield investors toward yield-chasing flows that can extend high-grade demand temporarily. That timing mismatch matters because AI-related supply is already skewing meaningfully toward investment grade, but the next leg of repricing pressure is most likely to show up where credit quality is closest to the BBB edge.

“Helpful-only” safety shortcuts, not an end-user unfiltered release: what Anthropic’s Opus 4.6 disclosures actually support
A wave of commentary claims Anthropic shipped Opus 4.6 “with the guardrails off,” but Anthropic’s own Opus 4.6 safety documentation shows “helpful-only” variants are used in internal evaluations—not as a published production mode. For enterprise buyers, the investable takeaway is simpler: Opus 4.6’s trust value is a product-policy story, while the unfiltered narrative appears to be a test-setup misunderstanding.
Apple trims Siri and Vision Pro headcount—then pays for the interface shift with distribution power
Apple is cutting more than 200 roles across Siri and Vision Pro teams as it realigns toward “new devices and artificial intelligence,” according to reporting. For investors, the more important signal isn’t cost control—it’s that Apple is backing away from owning the consumer voice-and-AR interface while competitors can move faster on model-led interaction loops.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.