Healthcare
Trial data, approvals, and what they are worth
Readouts, FDA decisions, drug pricing and payer behaviour, sized in revenue rather than in press-release adjectives.
2026-08-14

Bristol-Myers Squibb's Zenbexus flips the myeloma bet: one MRD endpoint, a 2x-to-41% hurdle
On Aug. 13, 2026, the FDA granted accelerated approval for Bristol-Myers Squibb's iberdomide (Zenbexus) in combination therapy for multiple myeloma, anchored to a major MRD-negative complete response endpoint. For investors, the key question isn’t whether Zenbexus “enters the market”—it’s whether this first CELMoD label can shift the post-Revlimid growth narrative fast enough to matter before market expectations fully price in a crowded daratumumab-centric landscape.
FTC’s Epic probe targets the EHR gatekeeper’s leverage—an interoperability shift that could reprice payer data deals and speed health-AI training timelines
The FTC has opened an antitrust investigation into Epic Systems and is seeking information about how it grants or withholds access to health records. The key investor question is not whether Epic is “pro-” or “anti-” AI—it’s whether enforcement tightens the practical meaning of interoperability, changing bargaining power and data availability for payers and health-data platforms.
2026-08-12
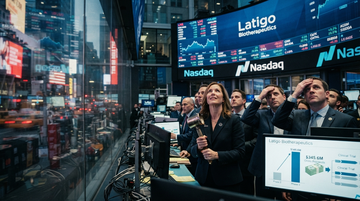
Latigo Biotherapeutics prices a $345.6M IPO for Nav1.8—turning the post-opioid pain trade into a “Phase 3 or bust” bet
Latigo Biotherapeutics priced an upsized IPO at $18 (top of range) to raise $345.6M, valuing it at a fully diluted ~$1.3B at launch. The story investors are paying for is simple: Latigo Biotherapeutics’s Nav1.8 inhibitor (LTG-001) is positioned as opioid-sparing fast relief, but the cash is being used to cross into pivotal Phase 3 while the company still lacks commercialization revenue.
Eli Lilly turns retatrutide into a patent-and-enforcement signal for the next oral GLP-1 TAM
Eli Lilly has sued six companies over alleged illegal sales of its experimental obesity drug retatrutide while it remains unapproved, signaling that commercial IP conflict is arriving before the molecule’s launch. The case matters for investors because retatrutide’s tri-agonist profile raises the odds of a faster-than-expected leapfrog—while the enforcement push aims to protect the pathway toward broader, more scalable obesity treatment economics.
2026-08-11
Hims & Hers’ branded GLP-1 pivot turned cost of revenue into the story—Q2 gross margin fell from 76% to 64%
Hims & Hers’ strategy shift toward branded GLP-1 medications drove a much wider quarterly loss and compressed gross margin, with management citing sharp increases in product/packaging, shipping, and medical consultation costs. For telehealth models, the implication is direct: branded drug sourcing turns “subscriber growth” into “cost pass-through risk,” and intermediaries pay for brand capture.
Trump’s Aug 10 MMR “Three Shots” EO Could Break Merck’s Only Bundle Advantage—If Pediatrics Adopts It at Scale
On Aug 10, 2026, the White House signed an executive order directing HHS to shift MMR from a combined product toward three separate single-disease shots when domestically available, and to favor separate clinical visits. The policy design attacks the operational “bundle” convenience that already exists in the current MMR system—creating a structural compliance tax for pediatric offices and a new runway for monovalent developers like Sanofi and other vaccine suppliers.
2026-08-10
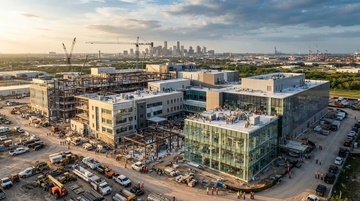
Bristol Myers’ $2.3B Houston campus turns pharma reshoring into build-out of finished-goods capacity
Bristol Myers is committing about $2.3B to a new multi-modal manufacturing campus in Houston, with ~600,000 sq ft sized for small molecules, biologics and antibody-drug conjugates. Framed alongside Reuters’ “tariff threat” push, the investor takeaway is that the reshoring wave is shifting from announcements to hard, finished-product capacity—raising near-term demand for engineering, CDMO services, and lab/bioprocess tooling while compressing execution risk into 2027–2030 timelines.
Hims & Hers turns subscriber growth into guidance proof—telehealth becomes a volume platform
In its latest earnings update, Hims & Hers reported subscribers rising to nearly 2.6M (+9% YoY) and raised full-year 2026 revenue guidance to $2.8B–$3.0B. The key investor takeaway is that the company’s top-line beat is now subscriber-driven—supporting a shift from “one-product GLP-1 cycle” risk to a broader telehealth platform with measurable, repeatable volume.
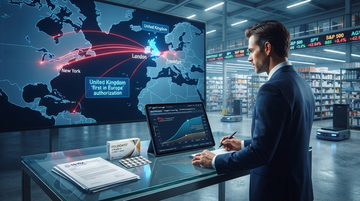
UK calls Eli Lilly’s orforglipron “first in Europe” (10 Aug 2026)—and that sequencing risk compresses the EU/US GLP‑1 oral TAM while it’s still awaiting FDA/EMA timing
The UK’s MHRA authorized Eli Lilly’s oral GLP‑1, orforglipron (Foundayo), on 10 Aug 2026 as “the first country in Europe” for weight management and type 2 diabetes—before broader EU and US timing is locked. For investors, the key is not just access; it’s how an early UK regulatory imprimatur can reshape prescribing momentum, contracting expectations, and competitive sequencing while FDA review is still pending in the US.
2026-08-08
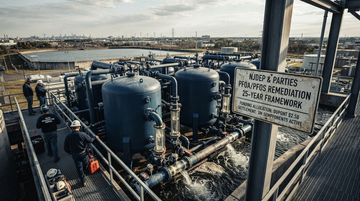
NJ’s $2.5B PFAS deal turns “forever chemicals” into a funded balance-sheet item—and rewrites who bears the next wave of US water risk
New Jersey’s court-approved PFAS settlements with DuPont (plus its spinoffs) and 3M convert open-ended “forever chemical” liability into scheduled, allocable payments through a 25-year remediation framework. For investors, the immediate read-through is less about one state getting paid—and more about how the payment+trust model pressures insurers, reshapes utility capex planning, and strengthens the enforcement pipeline across the US water system.
SEC’s pardon-linked dismissal turns a once-binary insider tail risk into a discretionary policy lever—biotech executives should price the upside differently
When an insider-trading defendant receives a presidential pardon, the SEC can choose to drop the civil case rather than litigate the merits. That “pardon-as-procedural-shield” enforcement discretion is likely to lower expected legal tail-risk for politically connected healthcare and biotech executives—while keeping M&A and trial-disclosure conduct in focus, because the operational information advantage still drives market outcomes.

Judge Halts DoD’s WuXi “Chinese Military Company” Label—But BIOSECURE’s Clock Can Re-Start Differently
A U.S. judge preliminarily enjoined the Pentagon from enforcing its June 2026 Section 1260H “Chinese military company” designation for WuXi AppTec, blocking the immediate BIOSECURE reactivation path tied to that label. For investors, the key question is not whether the BIOSECURE restriction exists, but how CROs and US biotechs must re-route procurement after the compliance trigger is legally paused.
2026-08-07
Anthropic’s 85% fewer biology fallbacks reframes biosecurity as a measurable, cost-to-serve moat
Anthropic says its Aug 7, 2026 update cut biology-related “fallbacks” by about 85% in testing by tightening the boundary of its biology safeguards (constitutional classifier tuning). If regulated labs buy based on operational friction—not just policy—this kind of measurable false-positive reduction can lower reroute-and-retry costs while improving throughput into life-science workflows.
Anthropic’s 85% fewer biology fallbacks turns biosecurity from “friction” into a measurable cost-to-ship advantage for regulated labs
Anthropic reports that an update to Claude Fable 5’s biology safeguards reduced biology-related fallbacks by about 85% in testing, while keeping higher-risk dual-use controls intact. For enterprises running AI in regulated laboratory environments, fewer fallbacks means less workflow interruption, fewer manual handoffs, and lower total cost per usable “research session”—even when safety remains a hard requirement.
2026-08-06
Insulet's US guidance cut shows Omnipod is priced like a reimbursement negotiation product, not a TAM story
Insulet beat Q2 expectations but cut full-year U.S. Omnipod revenue guidance (constant-currency growth) to 17%–19%, down from 20%–22%—a move the market treated like a structural “pricing trap.” The read-through is that diabetes hardware demand in the U.S. is increasingly gated by payer terms and coverage velocity, shifting outcomes for DexCom, Abbott, and Medtronic.
One produce supplier can hit multiple QSR banners at once—what the Taylor Farms Cyclospora case implies for next-quarter same-store sales risk
A FDA-linked, 9-state Cyclospora outbreak traced to iceberg lettuce from Taylor Farms de Mexico exposed Taco Bell customers across 9 states and sickened 1,947 people. The investor takeaway isn’t just recall-cycle headlines—it’s that a single ingredient failure can become a chain-wide same-store-sales variable through franchise remedies, insurance claims, and distributor pull-through effects before the next earnings print.
2026-08-05
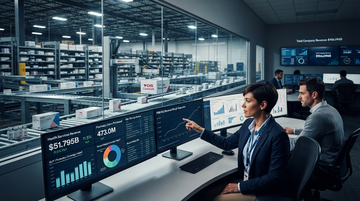
CVS just proved PBM drug revenue can outgrow the retail “GLP-1 siphon”—here’s the mechanism investors should track
In its Q2 results, CVS showed Health Services (Caremark/PBM) growing faster than the headline narrative suggests: Health Services revenue rose 11.5% YoY to $51.795B, with pharmacy claims processed up slightly. The counter-intuitive part isn’t that retail dispenses more cash-pay GLP-1s—it’s that CVS’s PBM economics can still expand through mix/brand inflation and formulary coverage even as retail captures a slice of demand.
Eli Lilly Is Raising Guidance Because Volume Beat Prices — So the Supply Ramp Is Likely Catching the Demand Curve
In its latest update, Eli Lilly raised 2026 revenue guidance to $82.0B–$85.0B from $80B–$83B, with the company pointing to volume growth as the primary driver. For investors, the key question is not whether GLP-1 demand exists, but whether Lilly’s manufacturing ramp is now keeping pace—determining whether 2026 looks like a production story (constrained) or a consumption story (inflecting).
2026-08-04
Clorox Just Got a Real-Staples “Re-Rate” Test—Purell Is Doing the Work
Clorox’s GOJO/Purell bolt-on did not just add scale—it changed the company’s 2026 outlook math, with guidance explicitly tracking margin headwinds and transaction costs tied to the deal. For investors, the question shifts from “does hygiene sell volumes?” to “can margin-mix from higher-quality hygiene assets defend earnings through the AI-era spend normalization?”
Gilead Sciences's HIV growth buys time—but only if its R&D spend translates into “next-legs” before Biktarvy peak cash turns into renewal risk
Gilead Sciences reported base business up 8% and raised full-year guidance to expect HIV sales growth of 8% in 2026. But the investable question is how long that HIV duration can keep funding pipeline bets: in FY2025, free cash flow was $9.46B while R&D is ~$5.80B—meaning the “duration” thesis hinges on near-term clinical conversions, not just franchise resilience.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.