Healthcare
Trial data, approvals, and what they are worth
Readouts, FDA decisions, drug pricing and payer behaviour, sized in revenue rather than in press-release adjectives.
2026-08-24

2026-08-23
2026-08-22
Brii’s 42.9% HBsAg-loss readout turns hepatitis B “cure” into a pricing problem, not just a scientific milestone
Brii 2137.hk reported an end-of-treatment HBsAg-loss rate of 42.9% (42/98) with BRII-179 in a BRII-179 + elebsiran + PEG-IFNα regimen, one of the strongest public functional-cure signals in chronic hepatitis B. If this translates into durable HBsAg loss off treatment, it re-rates the entire industry from “lifelong suppression” to “finite-course, cure-priced” commercial models—benefiting HBV-focused incumbents and RNA- and immune-modality platforms while raising a new diligence question: rebound durability.
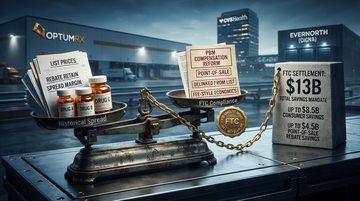
FTC’s Caremark deal turns PBM “spread” economics into a compliance liability for CVS, OptumRx, and Cigna
The FTC’s Aug. 21 settlement with Caremark is not just another drug-pricing fight—it forces PBMs to restructure how rebates and reimbursements are handled at the point of sale, including delinking PBM compensation from drug list prices. That directly threatens the margin mechanics that historically let PBMs capture value via spreads and rebate pass-through design, shifting the industry toward fee-style economics.
Gossamer Bio's $250M financing bets seralutinib can still win a reshaped PAH market after Merck's Winrevair label expansion
On Aug. 21, Gossamer Bio announced up to $250M of structured private-placement funding to drive seralutinib toward an FDA approval path in pulmonary arterial hypertension. The wager lands right after new Merck Winrevair label evidence strengthened the “clinical worsening” argument—raising the bar for any late-stage PAH competitor that hopes to displace (or add to) standard-of-care.
2026-08-21

argenx wins Phase 3 for autoimmune myositis, pushing its FcRn autoantibody franchise further into chronic immune disease
argenx’s Phase 3 ALKIVIA readout in autoimmune myositis (IMNM + DM) landed a statistically significant primary endpoint, with a 15.4-point Total Improvement Score advantage over placebo. The investor question shifts from “can autoantibodies win?” to “how wide can the FcRn reach go without payer/label friction,” especially as the broader autoantibody-adjacent complex just saw repricing risk after AstraZeneca’s Wainua CARDIO-TTRansform miss.
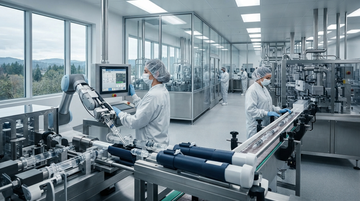
Roche’s $750M Oregon device fill-finish plan turns reshoring into a combination-product systems build
Genentech (Roche’s U.S. subsidiary) will invest about $750M in Hillsboro, Oregon to add a drug-delivery-device fill-finish plant expected to start commercial operations in 2031. That is a contrarian reshoring datapoint versus reports of German companies pulling back U.S. direct investment in H1 2026, and it reframes “onshoring” from just APIs/biologics to full drug-device manufacturing capacity.
2026-08-20
Trump’s FDA pick Overton turns therapy-class FDA odds into a portfolio bet: psychedelics & non-opioid pain up, vaccines down
Heidi Overton’s nomination is being read by sell-side analysts as a cross-therapeutic shift in how FDA leadership signals risk tolerance—supportive for psychedelic and non-opioid pain programs, but less friendly for vaccines. The investors’ problem is that this “repricing by class” can move approval timelines without yet proving which platform companies actually monetize first.
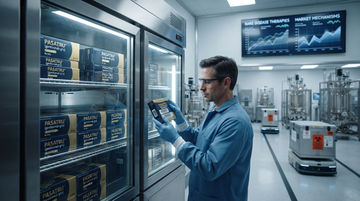
Regeneron's Pasatru turns an ultra-rare bone disease into an FDA pricing stress test—proof that sub-10,000-patient markets can still clear and fund premium drug economics
Regeneron won FDA approval for Pasatru (garetosmab-grts) in adults with fibrodysplasia ossificans progressiva (FOP) on Aug. 19, 2026, backed by OPTIMA results showing large lesion reductions at 56 weeks. The approval matters to investors because it spotlights whether ultra-orphan demand signals and list-price frameworks can support high-cost biologic commercialization even when the eligible population is extremely small.
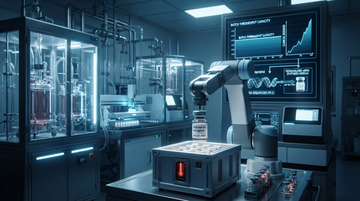
INTerpath-001 proves the science—but Moderna’s personalised mRNA build is the sales “throughput” limiter investors must model
On Aug 19, 2026, Merck and Moderna reported positive Phase 3 topline results for intismeran autogene plus Keytruda (INTerpath-001). But the product is “made-to-order” per patient using that patient’s tumor mutations, so capacity is constrained by sequencing turnaround and bespoke mRNA manufacturing/fill-finish, not just by clinical demand.
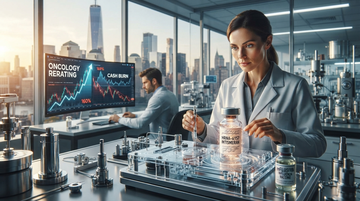
Moderna's 160% surge on intismeran has priced in a near-miss level of oncology upside—while the cash-burn and mFLUSIVA reality can still decide whether this rerating sticks
After Moderna moved sharply higher on Aug. 19–20 following positive late-stage melanoma vaccine data for intismeran, investors repriced the company as an oncology platform in hours. But the equity math implied by a “double” rerating conflicts with the cash-burn profile shown in recent financials—and it may be underweighting the more immediate, commercial (flu) ramp from mFLUSIVA and the continuing operating cash needs.
2026-08-19
Haemonetics HAE just locked CSL CSLLY into a plasma-collection device flow—without exclusivity. The stock jump is the market betting the “bottleneck” is CSL’s capacity, not Haemonetics’ supply.
Haemonetics HAE formalized an expanded, non-exclusive plasma-collection supply agreement with CSL CSLLY that lets CSL use Haemonetics’ NexSys PCS devices with Persona PLUS technology and buy related disposables in the U.S., with no minimum purchase commitments. The deal shifts the adoption test to CSL’s collection-center transition plan—exactly where plasma liquidity is structurally constrained—explaining why investors treated the announcement as a high-signal catalyst.
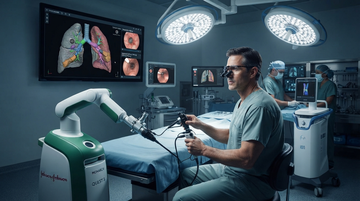
J&J’s MONARCH QUEST 3 clearance targets early lung-cancer diagnosis—now the key question is whether it can out-pace Intuitive’s Ion on procedure yield
Johnson & Johnson secured U.S. 510(k) clearance for MONARCH QUEST 3 on Aug. 17, 2026, positioning the software update to improve bronchoscopy planning, navigation, and targeting for earlier lung-cancer diagnosis. The near-term investor swing is whether faster, higher-yield biopsies translate into more reimbursed procedure volume in a market already served by Intuitive Surgical and its Ion platform—especially as Johnson & Johnson is also managing 2026 EPS drag from recent deals.
Moderna’s cancer-vaccine readout puts mRNA oncology on the board—and forces Merck’s pipeline economics to re-rate
A Merck–Moderna personalized mRNA cancer vaccine program has produced a positive, late-stage signal in high-risk melanoma, shifting investors from “platform hope” to “repeatable oncology engine.” The immediate implication is not just upside for Moderna: it also changes how Merck & Co. has to think about the probability-weighted value of personalized mRNA add-ons to KEYTRUDA across the pipeline—and how manufacturing capacity will gate commercial timing.
2026-08-18
FDA’s generative-AI device rulemaking starts Aug. 18: compliance costs will concentrate in companies that already run “real-world” validation
On Aug. 18, 2026 the FDA opened the formal public-feedback phase for regulating generative-AI-enabled medical devices, centered on risk assessment, premarket “competency assessment,” and postmarket monitoring. The near-term market impact is less about who gets first approvals and more about who can afford the validation tax—making established medtech platforms with existing QA and clinical-feedback loops structurally advantaged versus AI-native startups.
Fulcrum Therapeutics pays for the Slate Medicines merger with equity—and the $245M financing sets a clearer biotech funding window
Fulcrum Therapeutics and Slate Medicines have agreed to combine in an all-stock deal that comes with a $245M concurrent private placement for the Slate side, plus a $270M special dividend for Fulcrum holders at closing. The structure is a direct signal that, for small-cap genetic/next-gen drug developers, the cash-constrained consolidation path right now is equity-first—using capital markets timing and pipeline risk-sharing rather than pure cash buyouts.
2026-08-17
Medicare Advantage plan exits are the “recovery” trade’s first true stress test—CMS 2027 rate math tightens while only consolidators can recapture
Humana’s announced 2027 Medicare Advantage plan exits (impacting ~600,000 members) show how quickly “margin recovery” can turn into a footprint problem once bids get too close to the cost line. CMS’s 2027 payment framework still projects a 2.48% average MA rate increase, but key risk-adjustment changes (especially exclusions tied to unlinked chart review records) can make plan-level economics diverge—rewarding consolidators who can recapture volume and punishing retreaters who can’t.
WuXi AppTec double-from-panic signals the market is treating the BIOSECURE tail-risk as temporarily paused—not structurally dead
A D.C. court preliminarily blocked the U.S. Department of Defense from enforcing its Section 1260H “Chinese military company” designation of WuXi AppTec as litigation proceeds. That legal reprieve, paired with ongoing operating momentum, helps explain why shares can re-rate quickly—but it also suggests investors may be pricing a “timed relief” window rather than the end of U.S.–China biotech de-risking once the BIOSECURE timeline turns.
2026-08-16
2026-08-15
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.