Healthcare
Trial data, approvals, and what they are worth
Readouts, FDA decisions, drug pricing and payer behaviour, sized in revenue rather than in press-release adjectives.
2026-09-12

Apollo's $20B DePuy Bid Pays Less Than Half Stryker's Sales Multiple — And the Orthopedics Map Just Shifted
Apollo Global Management is in talks to buy Johnson & Johnson's DePuy Synthes orthopedics unit for roughly $20 billion, valuing the $9.3 billion-revenue business at about 2.1x sales — a sharp discount to Stryker's roughly 4.0x and roughly in line with the public Zimmer Biomet multiple. The deal would let Johnson & Johnson exit its slowest-growing medtech franchise at a take-private premium, hand Apollo Global Management a seat at the orthopedics top table backed by $1.05T in AUM, and re-rate the cost-of-capital math for every large-cap medtech in the Stryker-Zimmer Biomet competitive orbit. The near-term read is concrete: Stryker inherits a slower-moving rival; Zimmer Biomet faces a private-equity operator with both incentive and balance sheet to grab share; the contract manufacturers and hospital systems tied to DePuy's $9.3B book get a new negotiating counterparty.
Arizona just opened a state-level liability lane on hair-relaxer cancer — and L'Oréal's €44B group is the test case
Arizona Attorney General Kris Mayes filed the first state consumer-fraud suit against L'Oréal on September 10, 2026, alleging the company concealed cancer risks tied to its Dark & Lovely, Optimum and Mizani relaxers. With 12,129 federal MDL plaintiffs already lined up for a January 2027 bellwether trial and the EU banning 12 cosmetic substances months ahead of any FDA action, L'Oréal's €16B Consumer Products division now sits at the center of a liability template that drags in Godrej Consumer Products, the private Wella Company (now filing for a US IPO), and global peers Coty, Estée Lauder, and Procter & Gamble.
Apollo's $20B DePuy Bid Resets Orthopedic Valuations—Stryker's Premium Just Became a Moat
Apollo's reported $20B equity / $28B enterprise bid for Johnson & Johnson's DePuy Synthes prices the largest US orthopedic franchise at ~2.15x equity-sales—roughly half of Stryker's FY2025 5.84x multiple, and barely above Zimmer Biomet and Globus Medical trading levels. The deal crystallizes a two-tier orthopedic industry: one premium player (Stryker, with 3,000+ Mako systems installed) and a compressed cluster of private-equity-vulnerable tier-2 OEMs competing on cost, scale, and partial robotic systems. Contract manufacturers like Integer Holdings and the merged Tecomet/Orchid platform become the read-through winners as cash-strapped OEMs outsource more.
Trump's $500 ACA Refund Is the Headline — the Real Margin Story Is a 60-Basis-Point User Fee Cut Markets Haven't Priced
The September 10 announcement of $500 refund checks to ~1M unsubsidized ACA enrollees grabbed the headlines, but the bigger investor story is already locked in: CMS's May 2026 final rule cut the federally-facilitated exchange user fee from 2.5% to 1.9% of monthly premiums for 2027, redirecting an estimated $500M+ per year of insurer expense into margin. Combined, the two interventions cushion Centene, Oscar Health, and the rest of the ACA marketplace complex against a brutal 2026 enrollment year, with the largest pure-play leverage at Oscar Health and the largest footprint lift at Centene.
2026-09-11
2026-09-10
2026-09-09
2026-09-04
2026-09-03
FDA’s new GLP-1 compounding crackdown hits the telehealth cash-pay playbook—Hims must now win on branded economics, not scarcity arbitrage
On Feb. 6, 2026, the FDA publicly announced it intends to restrict GLP-1 active ingredients used in non–FDA-approved compounded drugs that are mass-marketed as alternatives to approved products—explicitly naming companies that include Hims & Hers. For Hims & Hers, the follow-on quarter already shows profitability stress (Q2 2026 gross margin in the company’s financials compressing to 76%→64% context from prior work and now broader operating losses), while the agency’s “shortage resolved” posture removes the regulatory tailwind that made compounding-led models economically durable.
Teva's celiac antibody win lands as MFN economics tighten—pipeline optionality now competes with margin reset
On Sept. 2, 2026, Teva reported positive Phase 2a results for its anti–IL-15 antibody (TEV ‘408) in adults with celiac disease, using a gluten-challenge biopsy endpoint. Two weeks earlier, Teva was included in a White House MFN pricing framework that is designed to bind future innovative launches to lower “most-favored” reference pricing—an economic headwind for any autoimmune “blockbuster path.” The stock debate shifts from “can Teva win biologics?” to “can it win enough high-value autoimmune volume before MFN pricing reshapes the upside math?”
2026-09-02
GLP-1’s “aftermath” is boosting breast implant demand—why Establishment Labs could be the next device-spillover trade
A fresh TD Securities note ties rising GLP-1 use to a faster pace of U.S. breast augmentation procedures and related “post-weight-loss” volume demand, framing the opportunity as the drug’s downstream correction cycle rather than the drug sales themselves. For Establishment Labs, the bullish setup hinges on whether GLP-1-driven weight loss keeps shifting patients toward implant-based restoration as the Motiva U.S. launch scales.
Medtronic's raised FY27 EPS guide lands right after a 13.7% organic quarter — and it reads like a medtech demand rerate, not an execution beat
Medtronic reported Q1 FY27 revenue of $9.756B with 13.7% organic growth, including cardiovascular up 18.9% organic, and it raised FY27 EPS guidance to $5.94–$6.00 (non-GAAP). The signal looks strongest in contrast to Johnson & Johnson, which lowered FY26 EPS guidance due to deal-related costs by about $0.64, shifting attention from pipeline timing to near-term purchasing behavior.
2026-09-01
OpenAI just moved into the EHR itself—compressing AI scribes and point tools before it hits the wider market
On Sep 1, 2026, OpenAI said ChatGPT Health can be connected to Epic’s EHR to bring authorized patient context into the clinician workflow, with an option for AI help directly inside the EHR interface. The move shifts AI competition upstream from add-on documentation and “point solutions” toward the EHR distribution choke point—while the FTC’s ongoing scrutiny of Epic’s data-access practices becomes the regulatory wildcard for how fast this embedding scales.
September’s 5 FDA binaries are real—but the “MRK” name doesn’t map to Merck & Co or Merck KGaA (yet)
Three of the five named September PDUFA binaries are anchored by primary company disclosures with specific decision dates: Telix Pharmaceuticals (Sep. 11), Ionis Pharmaceuticals (Sep. 22), and Mirum Pharmaceuticals (Sep. 26). For the other two names—Ultragenyx Pharmaceutical and “MRK”—the month’s slate appears to mix multiple products and/or renewals, so the “five binaries land in September” story is directionally useful but needs exact product-to-company confirmation before pricing math.
2026-08-31
BioNTech’s colorectal mRNA-vaccine trial stop spotlights a structural risk: FDA-style “safety first” scrutiny can break neoantigen optimism even after melanoma momentum
BioNTech and Genentech [BNT122/“autogene cevumeran”] stopped a Phase 2 resected colorectal-cancer trial after an independent DSMB flagged a numerical overall-survival imbalance and recommended terminating treatment, even without a newly disclosed safety signal. The timing—just days after Moderna and Merck celebrated Phase 3 [INTerpath-001] melanoma efficacy—shifts investor focus from endpoint math to trial design exposure, DSMB trigger thresholds, and what “safety-risk caps” mean for the personalized neoantigen class.
Bristol-Myers Squibb's Cellares exit shifts CAR-T CDMO economics from “capacity bet” to “qualification tax”
Bristol-Myers Squibb ended a CAR-T manufacturing capacity reservation and supply arrangement with Cellares after concluding Cellares’ Cell Shuttle system could not meet specific regulatory requirements for Breyanzi. The breakup turns a high-visibility outsourced-manufacturing bet into a cautionary model: CDMO success hinges less on throughput promises and more on process-control qualification—especially when commercial-scale dosing is at stake.
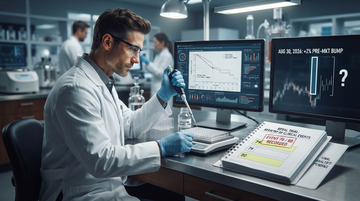
Sellas' GPS Just Needs 2 More Deaths — Why a 2% Pre-Market Bump Is Hiding a One-Day Repricing Event for Sellas Life Sciences
Sellas Life Sciences climbed 2% in pre-market trading on Aug 30, 2026 after LinkedIn comments from AstraZeneca and Johnson & Johnson sales executives called its Phase 3 AML drug 'game changers' — but the real story is the binary trigger sitting two deaths away. With 78 of the 80 events recorded in REGAL, an 80th death hands Sellas a same-day catalyst that can halve or double the stock on a single survival readout, while 28% of the float is already short.
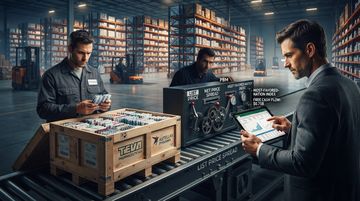
Trump’s Teva and Astellas “most-favored-nation” deals shift drug-price risk toward manufacturers—and toward PBMs’ net-price math
Trump’s administration announced a new round of bilateral “most-favored-nation” style pricing agreements that include Teva and Astellas Pharma, tied to state Medicaid access and foreign-price parity. Unlike the IRA negotiation framework, this voluntary approach can change net-price expectations across generics and branded portfolios—and force PBMs and manufacturers to re-cut incentives around list-to-net spreads.
2026-08-30
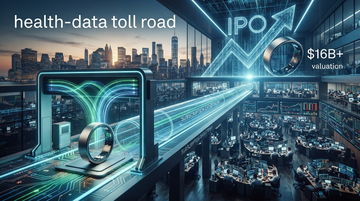
Oura’s $3B IPO bet isn’t on smart rings—it’s on a subscription “health-data toll road” that investors must underwrite at a $16B+ valuation
Oura has signaled a potential U.S. IPO that could raise up to $3B and value the business at more than $16B, while projecting roughly $2B in 2026 sales. That combination implies the market is paying consumer-tech multiples for recurring health-data economics—so the real debate is whether retention and downstream monetization can persist even as Apple, Garmin, and other smart-ring entrants scale marketing and device cycles.
Smart-ring value doesn’t start in sapphire or sensors—it locks in at the recurring health-data subscription
The next wearable “boom” is still constrained by the physical parts—biosignal optics, power, and skin-contact materials—but the investable margin is increasingly determined by who controls the recurring health-data layer. Oura’s move toward public markets makes that hardware-vs-subscription split measurable, while FDA’s stance on non-authorized glucose claims shows why regulated signal quality—not the enclosure—drives durable platforms.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.