Healthcare
Trial data, approvals, and what they are worth
Readouts, FDA decisions, drug pricing and payer behaviour, sized in revenue rather than in press-release adjectives.
2026-08-29

AstraZeneca–Ionis CARDIO‑TTRansform reopens the outcomes bar: RNA can hit biology, but this dataset resets expectations for mass-market cardiology
AstraZeneca and Ionis’ [eplontersen] update for ATTR cardiomyopathy missed the trial’s primary composite cardiovascular outcomes endpoint through Week 140, despite a nominally positive result in a prespecified monotherapy subgroup. The new ESC-season debate is less about whether RNA drugs work mechanistically—and more about whether they can clear the statistical-and-context hurdles that separate rare-disease efficacy from scalable cardiometabolic impact.
BioXcel–Teva asset sale reframes small-cap biotech funding: distressed developers are monetizing FDA-window optionality instead of selling equity
BioXcel’s Aug. 28, 2026 court-supervised agreement to sell CNS assets to Teva centers on a product with an FDA PDUFA target of Nov. 14, 2026—priced with an upfront payment plus FDA-timing-linked contingencies. The deal highlights a survival path for cash-starved small biotechs: asset-level M&A that converts an “FDA-binary week” financing window into buyer-operated development and more structured milestone payoff.
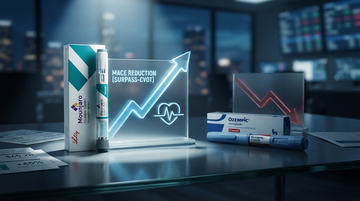
Eli Lilly's Mounjaro approval turns GLP-1 into a cardio franchise—at Novo Nordisk's expense
Eli Lilly won an FDA cardiovascular-risk reduction label for Mounjaro (tirzepatide) in high-risk type 2 diabetes, effectively widening the GLP-1 outcomes market beyond glucose control. With the SURPASS-CVOT readout showing a relative MACE reduction versus Trulicity, Lilly now has a cleaner payer script and a faster path to address higher-acuity cardiovascular patients. For Novo Nordisk, that label expansion raises competitive pressure on its GLP-1 outcomes posture and makes the next few quarters less about diabetes uptake and more about whether prescribers treat Mounjaro as a default cardio-risk option.
Rusfertide’s FDA nod turns hepcidin mimicry into a bankable PV franchise—and rewrites who wins the iron-biology arms race
On Aug. 28, 2026, the FDA approved Mimrylo (rusfertide) as the first drug of its kind for polycythemia vera (PV), validating hepcidin-mimetic control of iron trafficking as a prescription-grade mechanism. The approval directly crystallizes the commercial “tollbooth” for Protagonist Therapeutics—$275M triggered to date and tiered royalties—while also setting a clearer competitive benchmark for rival hepcidin-modulating programs aimed at PV, post-PV myelofibrosis, and anemia.
Walmart’s $50M opioid case close removes an EPS overhang—and tightens the remaining “liability ladder” on manufacturers and distributors
On Aug. 28, 2026, the U.S. government announced a $50 million settlement with Walmart to resolve allegations tied to invalid opioid prescriptions filled by its pharmacies. The amount is small versus Walmart’s prior multistate opioid framework, and the case is framed as “allegations only,” which matters for how investors should think about remaining exposure across the opioid supply chain.
2026-08-28
Braveheart Bio’s $382.5M IPO priced at $18—and it quietly widens the “FDA-binary week” stress test for biotech IPO risk
Braveheart Bio BRVE priced an upsized IPO at $18.00 and raised $382.5M in gross proceeds, immediately following the kind of “midterm healthcare repricing” that often makes biotech buyers more selective. With the IPO timed into a high-information FDA cycle and the market just absorbed Latigo’s LTGO $345.6M Nav1.8 pricing, Braveheart’s debut looks less like a one-off and more like the latest read-through on how much biotech uncertainty the IPO window will fund.
Roivant and Priovant win the first oral dermatomyositis win—but it’s what comes after the pill that matters
On Aug 27, the FDA approved Roivant and Priovant’s LISRAYA (brepocitinib) as the first oral therapy for adult dermatomyositis. The competitive question shifts from “who has the right biology” to “who captures a wider treatable population”—because oral dosing can lower the real-world friction that has historically kept most patients on non-targeted, corticosteroid-heavy regimens.
ImmunityBio needs one “week 104” proof point to compete with big-pharma’s mRNA oncology winners
A fresh milestone update tied to ImmunityBio’s Chairman Patrick Soon-Shiong said the company’s cancer-vaccine trial has been fully accrued and reached its one-year mark, with the primary assessment at week 104 expected around 2027. The market read-through is straightforward: if this non-mRNA platform can translate a process milestone into credible efficacy data on a competitive oncology timeline, ImmunityBio could earn a larger share of investor attention currently dominated by mRNA oncology optimism.
PhRMA’s Medicare-negotiation bid just failed—IRA drug price cuts shift from legal risk to a permanent revenue-mix problem
On Aug. 27, 2026, the U.S. Court of Appeals for the Fifth Circuit upheld the Medicare Drug Price Negotiation Program after PhRMA’s legal challenge was rebuffed. That outcome turns IRA-negotiated Part D pricing into a durability factor investors must underwrite: revenue now depends on how much of each company’s U.S. demand sits inside the negotiated “maximum fair price” lane (and how aggressively launches and contract structures adapt).
2026-08-27
AstraZeneca and Amgen's Tezspire win in EoE tests whether the ‘late-stage discount’ finally flips on a GI bellwether
AstraZeneca and Amgen say Tezspire (tezepelumab) delivered positive Phase 3 results in eosinophilic oesophagitis (EoE), meeting co-primary endpoints at Week 24 in the CROSSING trial and sustaining improvements through Week 52. The investor question is not just efficacy—it’s whether a confirmed late-stage readout in a Dupixent-adjacent GI indication meaningfully reduces the pipeline execution risk that has recently pressured AstraZeneca’s growth narrative.
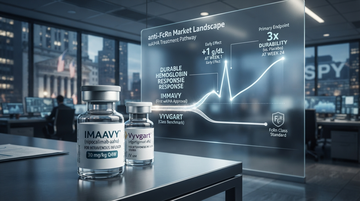
J&J’s Imaavy approval turns wAIHA into the anti‑FcRn class’s first real pricing proving ground—and raises the bar for argenx’s Vyvgart
On Aug. 24, 2026, the FDA approved Janssen’s Imaavy (nipocalimab-aahu) as the first treatment specifically cleared for warm autoimmune hemolytic anemia (wAIHA). Because this is the first commercially approved test of the anti‑FcRn mechanism in wAIHA, the launch will quickly become a benchmark that shapes payer and physician expectations for future FcRn expansions—including whether Vyvgart remains the default reference point within the class.
Moderna’s $2B convertible bets oncology—dilution math hinges on capped calls, not the headline bond size
Moderna MRNA announced a $2.0B private placement of convertible senior notes due 2032 to fund oncology growth flexibility and repayment of debt, while also paying for capped-call hedges to limit dilution. The “bull trap” debate is less about whether the company needs cash and more about whether the equity’s implied conversion path is realistic given the capped premium and Moderna’s persistent cash burn.
Novo Nordisk clears China NMPA acceptance for an oral Wegovy bid—shifting the obesity “pill-first” battlefield toward price-controlled, domestic-led competition
China’s NMPA has accepted Novo Nordisk’s application to sell an oral version of Wegovy, giving Novo a first-mover regulatory position in the world’s second-largest obesity market. The bigger investment story is how China’s price controls and fast-growing domestic oral GLP-1 copycats can compress Novo’s China margin upside, even as the oral category expands the global TAM for semaglutide-class therapies.
Veeva’s Q2 FY2027 print answers the “seat cuts vs. surprises” question: R&D/Quality growth stayed intact
In Veeva June-ending Q2 FY2027 (ended Jul 31, 2026), total revenue grew 18% year over year and subscription revenue grew 16% year over year, with R&D and Quality Solutions delivering $419.4M in the quarter. The release also points to continued Development Cloud/Quality Cloud adoption and a large biopharma selecting Veeva EDC—suggesting that “budget tightening” shows up more as deal timing and mix, not wholesale seat loss.
2026-08-26
Boston Scientific's cyberattack hits order/shipping systems—so medtech investors should price a new “working-capital + revenue-timing” risk
Boston Scientific BSX disclosed a global cyberattack that disrupted operations and is expected to continue limiting access to systems that support “the ability to process and ship customer orders.” The immediate market question isn’t just whether product manufacturing stopped—it’s whether order intake and fulfillment delays push revenue recognition into later quarters and increase working-capital and charge risk at the same time BSX is running a large restructuring program.
FDA clears the first continuous dual glucose–ketone wearable—turning CGM into the metabolic control panel the GLP-1 era never had
On Aug 25, 2026, the FDA authorized Abbott’s Libre Duo 10 Day as the first wearable in the U.S. to continuously monitor both ketones and glucose in a single device, primarily to provide earlier warning of rising ketones that can precede diabetic ketoacidosis. The upgrade matters for investors because it expands the measurement layer of metabolic health beyond diabetes, and it forces a new competitive map for CGM-like “sensor + app + alerts + integrations” platforms across the obesity/GLP-1 value chain.
Generate Biomedicines’ lock-up expiry isn’t “just” an overhang—it’s a test of how scarce investors view AI-native protein design
Generate Biomedicines’ post-IPO lock-up is set to end roughly 180 days after its Feb. 27, 2026 public trading start, setting up a predictable supply overhang. The stock’s rally into the date implies investors believe AI-native protein design (and the company’s drug-development execution) can absorb the added float risk faster than dilution anxiety can spread.
Jazz’s Ziihera approval is the HER2 biliary-tract moment—now the investor question is how much profit Merus monetizes and how fast Jazz can move beyond a “niche” BTC label
The FDA’s Aug. 25, 2026 approval of [Ziihera (zanidatamab-hrii)] for HER2+ first-line gastroesophageal adenocarcinoma (plus the previously approved HER2+ biliary tract cancer label) ends the “yes/no” binary—turning the market focus to launch pace and unit economics. The co-development terms mean a meaningful share of incremental value flows back to Merus’ partner structure via Zymeworks milestone/royalty economics, so the profit split—not just clinical uptake—will decide whether this becomes a durable earnings lever for Jazz Pharmaceuticals rather than a headline-only win.
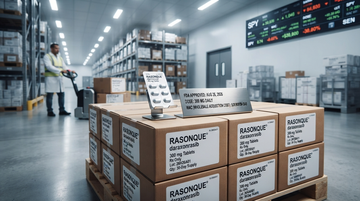
Revolution Medicines’ RASONQUE cracks pancreatic cancer with a $39,800/30-day price tag—turning KRAS from “undruggable” to monetizable
Revolution Medicines‘s FDA approval for RASONQUE reframes pancreatic cancer economics around a daily, targeted pill rather than chemotherapy-only leverage. The approval’s core bet is that a KRAS/RAS-driven subset can generate durable, reimbursable demand—starting at a wholesale acquisition cost of $39,800 for a 30-day supply—while established oncology majors face slower switching unless they can match both survival and market access.
2026-08-25
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.