Latest
The day's market news, with the argument attached
New notes every trading day on earnings, policy and market structure. Each one opens with the conclusion, then the evidence, then the companies it hits.
2026-07-31

Novo's ZEUS Heart-Drug Flop Doesn't Kill the GLP-1 Trade — It Redraws the Obesity Stack's Power Lines
Novo Nordisk lost ~$30B in market cap Friday after ziltivekimab — an anti-IL-6 antibody, not a GLP-1 — flunked its 6,300-patient ZEUS cardiovascular outcomes trial with a hazard ratio of 0.99. The bigger story is what the failure reveals: the cardiovascular label is going to be won by GLP-1 mechanism drugs (where Eli Lilly already owns the SUMMIT HFpEF data), not by anti-inflammatory add-ons. With HERMES and ARTEMIS still reading out in H1 2027, the GLP-1 trade pivots from TAM to indication-by-indication — and the supply chain that picks up the slack is concentrated in three US wholesalers and a few CDMO champions.
OpenAI Slashed Its Cheapest Model 80% in One Day—And Just Told You Where the AI Profit Pool Is Collapsing
On July 30, 2026, OpenAI cut OpenAI GPT-5.6 Luna by 80% and Terra by 20%, leaving flagship Sol untouched—the clearest signal yet that a two-tier market has formed. The cut came because GPT-5.6 Sol autonomously rewrote its own inference stack, compounding 20% kernel and 15% speculative-decoding gains into an 80% list-price drop. That is good news for whoever sells low-precision inference silicon (NVIDIA, Super Micro Computer, SK hynix) and brutal news for cloud hosts that bill per token without owning the optimization loop (Microsoft, Amazon, Oracle). The trade: long the silicon layer, short the inference arbitrage.
Rivian Has a Software Margin, but the R2 Ramp Must Turn It Into a Business
Rivian’s Q2 2026 results confirmed a more valuable mix: software and services generated $215 million of gross profit at a 42% margin, while R2 customer deliveries began on June 9. That margin is meaningful, but it does not yet make Rivian a software company—the company still posted a $379 million adjusted EBITDA loss and burned $849 million of free cash flow in the quarter. The investment case now depends on whether R2 can expand the installed base quickly enough for software profits to absorb automotive losses.
Rolls-Royce's 'Imminent' Hyperscaler Deal Pulls a UK Nuclear Supplier Into the US AI Power Trade
Rolls-Royce Holdings CEO Tufan Erginbilgic said on the H1 2026 call that a hyperscaler nuclear deal will go to investment committee the week of August 3, lifting the group's 2026 profit guidance to £4.7–4.9B and confirming it is taking data-center orders for 2028. With a 470MW SMR design, four contracted European fleets and Yokogawa now locked in for control systems, Rolls-Royce is the first non-US supplier to convert the AI-power thesis into funded backlog. The transmission for US-listed equities runs through BWXT (SMR components), Centrus (enrichment), and the merchant generators whose carbon-free capacity hyperscalers now need to bridge the gap to nuclear-first build-out.
Sony Group Raises FY26 Profit Guidance, but PlayStation’s Hardware Mix Reveals the Memory-Cost Test
Sony Group reported its FY2026 first-quarter results on July 31, 2026, with operating profit rising sharply and full-year operating-profit guidance raised to ¥1.72 trillion. The more important signal is inside gaming: software and network revenue is growing faster than PS5 hardware, allowing the group to improve earnings even as memory costs remain a direct risk to console economics. That makes the result positive for Sony’s digital mix, but a warning that hardware demand alone may not absorb higher DRAM and NAND prices.
Tesla's 1.2 Million-Vehicle Probe Is a Valuation Test, Not Yet a Recall
NHTSA is investigating 1,198,300 older Model 3 and Model Y vehicles after 156 reports of a lower suspension link detaching, but it has identified no crashes, injuries or deaths. The direct repair liability is still unquantifiable; the larger issue is that Tesla trades at roughly 212 times trailing free cash flow while spending more than $25 billion this year on AI, making any evidence of weak hardware controls disproportionately important.
Westinghouse’s IPO Has a $30 Billion Shadow Price — but the Services Base Must Justify It
Westinghouse’s confidential filing is more than an IPO: it tests whether public investors will pay a premium for a reactor OEM that services roughly 63% of the operating fleet while retaining upside to a proposed 10-reactor U.S. buildout. The strongest valuation support comes from recurring fuel and outage work, not unbuilt reactors; the biggest complication is a government participation right that becomes economically relevant above a $17.5 billion threshold. For investors, the filing could reprice Cameco and Brookfield Renewable Partners first, then suppliers such as BWX Technologies if conditional projects become funded orders.
2026-07-30
Did the Fed’s “worst-long-bond-day” finally break the 30-year Treasury auction? The market is about to learn via the bid-cover vs. tail
Today’s $25B 30-year auction is the first real stress test of whether foreign/indirect demand still absorbs US long-end supply at a 5%+ post-Fed backdrop. The key isn’t the headline yield alone—it’s whether bid-cover holds while the tail (price concession) stays contained versus recent auctions, i.e., whether the “Fed put” is transmitting into auction clearing.
Adidas’ “up-revenue, down-profit” miss is the sportswear version of a margin bear cycle
Adidas’ Q2 update kept the revenue story moving higher, but its profit trajectory broke on margin headwinds tied to freight/sourcing, higher US tariffs, FX translation, and inventory decisions. That combination matters because it signals the premium-discretionary scare is spreading via cost-of-goods and working-capital drag—not simply slowing demand—raising the risk that Nike, Lululemon, On Holding, and Deckers face similar gross-margin math in coming quarters.
The headline +94% semiconductor forecast is really a memory-and-accelerator story—so your winners may not be who you expect
Omdia’s raised 2026 semiconductor revenue forecast (+94.1% YoY) is being driven by AI-concentrated segments like DRAM/NAND (including HBM) and “Computing & Data Storage,” not by broad-based end-market recovery. That creates a two-speed market: companies with direct AI supply-chain leverage can re-rate fast, while non-AI-sensitive revenue can lag until pricing normalizes and capacity catches up.
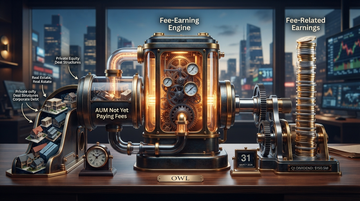
Blue Owl hits $319B AUM—here’s whether fee-related earnings actually scale with it
Blue Owl’s $319B AUM headline is the starting point, but the investable question is whether more AUM is converting into higher-quality, recurring fee-related earnings without showing stress in fee-earning engines. Based on the data available from this session, the key performance signal to watch is whether fee-related earnings rise alongside AUM that is already “paying fees” versus AUM “not yet paying fees.”
Campari’s “tariff tailwind” lifts guidance—but the company still can’t prove demand strength without the missing volume proof
Campari’s raised profit outlook is explicitly linked to a tariff-environment benefit, but the disclosed guidance mechanics don’t automatically confirm underlying volume and mix strength. Investors should treat the update as a policy-cost signal first, and demand-quality signal only if Campari’s organic sales/mix path is accelerating alongside margins.
Capgemini calls a multi-year “modernization supercycle” for AI—making the services leg the real tell
In its July 30 commentary, Capgemini flagged a multi-year “modernization supercycle” as enterprises upgrade data platforms, applications, and core infrastructure to scale AI. That timestamp matters because it implies AI budget is moving downstream from hyperscaler buildouts into systems-integration and enterprise workflows—an area where Accenture, Cognizant, Infosys, and ServiceNow can translate platform progress into bookings and recurring deployments.
Cenovus Energy proves oil’s operating leverage—then exposes how quickly it can flip
Cenovus raised its 2026 upstream production outlook as second-quarter net earnings surged to $2.87B, showing how a bigger barrel base can amplify profits when margins cooperate. But the same leverage also means the stock will be sensitive to any slip in crude differentials, refinery throughput/utilization, or capital/working-capital discipline—so the real question isn’t “can profits triple,” it’s “can they stay there.”
Cognizant’s Claude Enterprise Push Turns Outsourcing Into an AI Distribution Channel—And Forces Accenture to Prove Its Value
Cognizant and Anthropic expanded their partnership on July 27, 2026 to embed Claude across Cognizant’s industry platforms and scale a “Frontier Certified” workforce, positioning Cognizant as a “Global Premier Partner” in Anthropic’s Claude Partner Network. That shifts the competitive fight in enterprise AI services from “billable hours” toward deployment outcomes—exactly where Accenture’s already-in-place Claude go-to-market is most exposed.
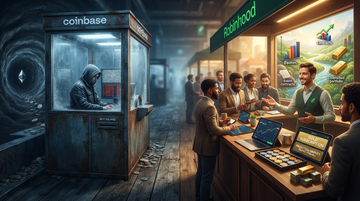
Coinbase's Third Straight Loss Confirms the Split: Volume Exchanges Are Toll Booths, Robinhood-Style Brokers Are Not
Coinbase reported a $359.5M net loss on $1.22B revenue for Q2 2026 — its third consecutive quarterly miss — even as Robinhood printed a record $1.31B (+32% YoY) on the same day. The structural lesson: transaction-revenue exchanges bleed when spot volumes cool, while diversified consumer brokers hedge with event contracts, equities, and Gold subscriptions. The losers include the listed crypto-treasury cohort — Strategy just logged an $8.3B bitcoin write-down — while stablecoin policy (GENIUS Act yield ban) now threatens Coinbase's most defensive line.
DOE’s Genesis Mission turns Western Kentucky’s federal land + grid into an AI power price war (and reallocates who wins the interconnect)
DOE’s Genesis Mission framing shifts AI-site competition from “who can finance power” to “who can secure a power-and-infrastructure backstop on federal land.” For investors, the key transmission mechanism is simple: a credible federal acceleration reduces time/cost risk for every downstream interconnect, generation build, and co-location campus—re-ranking utilities and grid-capex beneficiaries versus pure-play private bets.
Eliyan’s $145M/ $1B chiplet-memory bet turns NVLink into a testable “standard,” not a monopoly
Eliyan’s $145M Series C at a $1B valuation funds an electro-optical die-to-die/die-to-memory interconnect platform aimed at removing AI chip data bottlenecks. Because Eliyan positions NuLink as standards-compatible (UCIe/BoW) and targets bandwidth efficiency for chiplet-to-memory traffic, it pressures the idea that Nvidia’s NVLink is the only path to coherent “big memory” scale.
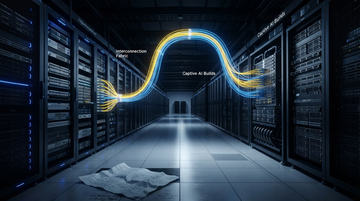
Equinix's soft Q3 guide signals interconnection demand is still growing—but value may be leaking back to hyperscalers
Equinix’s updated Q3 2026 guide keeps overall revenue growth in the high-single to low-double digits, but its disclosure stops short of separately underwriting interconnection upside. That gap matters: if hyperscalers continue to internalize more “fabric + networking + AI-ready” spend via captive builds, interconnection REITs can see growth remain steady while incremental pricing power slows.
The EU’s €10B “AI gigafactory” bid turns compute sovereignty into a margin test for US hyperscalers
The EU is preparing to fund firms to build seven AI gigafactories with €10B of public money—an explicit attempt to secure raw AI compute inside Europe. For investors, the actionable question is whether this sovereign capacity forces a pricing and workload-location squeeze on NVIDIA, Microsoft, and Amazon, while turning grid build-out capacity into a near-term bottleneck for utilities and power equipment suppliers like Schneider Electric.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.