Latest
The day's market news, with the argument attached
New notes every trading day on earnings, policy and market structure. Each one opens with the conclusion, then the evidence, then the companies it hits.
2026-07-30

FCC license-renewal pressure turns broadcast regulation into a “viewpoint risk premium”—ABC is warning station groups to price it in
ABC and Disney argue the FCC is using broadcast license-renewal leverage to chill network and local editorial coverage, framing it as unconstitutional intimidation. For listed station-group owners like Nexstar and Sinclair, the investor-relevant risk is not just a single license outcome—it's that regulation could be repriced as a standing probability of editorial interference, compressing deal multiples and raising “Washington discount rates.”
Fed Day Broke the Stock/Bond “Crash Cushion”—Because Inflation Risk and Real Rates Repriced Together
On Fed decision day (July 29, 2026), equities and Treasuries sold off in the same direction, not the usual hedge pattern. The move wasn’t just “rates stayed high”—it reflected a regime where inflation/risk premium and real-rate expectations rose together, weakening the diversification benefit long-duration Treasuries typically provide during growth scares.
Fed’s 9–3 “hawkish hold” turns internal dissent into a credibility premium for rates
When three voting regional presidents dissented in a 9–3 hold, it didn’t just change the policy path—it changed how markets price the next move. For investors, the actionable risk is not the hold itself, but that repeated visible dissent can widen the policy-risk premium and stress rate-sensitive earnings narratives—especially for banks whose income depends on the curve.
Fitch Calls an “AI Market Correction” a Top Global Credit Risk—So Hyperscaler Downgrades Look Like the First Domino, Not the Last
Fitch’s framing turns AI capex from a company-credit story into a system-credit variable: a potential market correction would hit funding costs, debt rollovers, and even credit quality across sectors and geographies. When paired with the hyperscaler warning line (capex/leases straining near-term credit metrics), it implies bond investors may reprice not just a few mega-cap issuers, but the broader credit “plumbing” that finances the AI build-out.
Goldman Sachs's "private markets platform" shows the real AI threat: distribution, not models
Goldman Sachs is formalizing a private-markets/alternatives platform for wealthy clients and creating a dedicated team structure to source direct private-company stakes. That matters to public asset managers because the easiest way to monetize AI in wealth is to ship allocations and portfolio access as software, shifting economics away from fees-on-AUM and toward product-led, account-sticky distribution.

Haleon’s H1 “US slip / Oral Health win” reframes the staples trade into a category bet
Haleon reaffirmed full-year guidance, but H1’s internal split matters: Oral Health delivered mid-single-digit growth while North America slowed versus stronger Emerging Markets. For investors running “premium staples” pair trades, the earnings print shifts the question from “staples resilience” to “which category compounds when the US consumer softens.”
ICE’s $5.7B MarketAxess bid can’t be modeled as “more liquidity”—it’s a fixed-income toll booth shift that squeezes execution and data economics
The paper-thin wedge regulators will focus on is not total bond liquidity—it’s who gets to charge for the electronic plumbing after ICE and MarketAxess consolidate fixed-income trading. If the $5.7B bid is approved on the stated economics, electronic credit and corporate-bond ETF “pick-up” spreads become a pricing battleground between the new duopoly’s toll booth and the ETF/dealer demand chain.
Intel’s foundry playbook shifts from “process sales” to “warm pipeline” as Intel technology routes through Lip-Bu Tan’s co-investor startup
A Reuters-exclusive arrangement described as Intel shipping proprietary 14A/18A-related chip technology to RosaicLabs—linked to a Lip-Bu Tan co-investor—looks like the first time Tan’s private venture network has become a foundry customer funnel. For investors, the key signal isn’t just another “customer”—it’s a new go-to-market mechanism that could compress the time from PDK/tool readiness to design-win commitments.
Johnson & Johnson's FY2026 EPS guide drops ~5% on deal/integration costs—proof the pharma M&A cycle is now a P&L story
After beating in Q2, Johnson & Johnson still cut FY2026 adjusted EPS guidance to $10.96–$11.11, attributing the reset to integration/transaction costs. The signal is broader than one quarter: the 2026–2027 healthcare earnings template is shifting from “pipeline-shaped upside” to “M&A-shaped near-term earnings pressure,” with investors needing to separate one-time deal costs from underlying franchise health.
JPM: The first sell-side vote of confidence that makes “hawkish hold” the base case—December hike, not March-2027
J.P. Morgan Global Research moved its next Fed hike call to a quarter-point in December after the July hold, aligning with the hawkish-hold interpretation that Warsh signaled. For US banks, that timing shift matters most for NII sensitivity to the September path—and it changes how much “duration risk” the market is forced to price before year-end.
The “double-print” (PCE + Q2 GDP) is a single Fed test—because both prices and growth hit at 8:30 a.m.
Today’s BEA calendar stacks Personal Income and Outlays (June PCE) and GDP (Advance Estimate) (Q2) on the same 8:30 a.m. window, turning the usual macro routine into one all-in policy-input read. The market should treat the next 24 hours as a fork: core PCE cooling is what lets the Fed plausibly look through hot growth, while both running hot is what feeds a 30-year auction-driven duration selloff.
L3Harris LHX Turns Weapons Demand Into Throughput Economics—Backlog Is Now the Unit of Measure
L3Harris LHX's Q2 results tie weapons-demand strength to production volume rather than one-off contract wins, which is exactly what “restock cycle” believers need to see. The market should now judge defense primes less by backlog headlines and more by how fast backlog converts into revenue, cash, and operating margin under constrained industrial capacity.
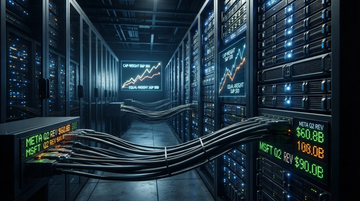
Mag-7 earnings are the first real “broadening” stress test—and the cap-weight is already doing the heavy lifting
The equal-weight S&P 500’s YTD lead suggests investors have been paying for “the average stock,” not just the largest tech complex. The first Mag-7 prints of the cycle (Meta and Microsoft) show why the divergence can flip: when leaders’ AI capex starts to pressure earnings quality, the cap-weight doesn’t just move with growth—it moves with expectations.
Meta’s capex jump buys AI time—but it risks starving FCF while Microsoft turns spend into service-margin growth
Meta and Microsoft printed a near-simultaneous capex signal, but the market’s read-through is likely less about AI demand and more about how each firm funds it. Meta’s latest reported cash flows show a large capex drain versus free cash flow, while Microsoft’s cash engine supports an even heavier buildout, implying power/cooling & connectivity vendors get paid sooner than advertising/consumer-internet margin holders.
Magnum's cost-cuts can lift profits without breaking Ben & Jerry’s—if the “brand engine” keeps pulling volume
Magnum MICC is showing a classic split: restructuring-style cost takeout supports earnings optics while its largest ice-cream brands still grow. The key investor question is whether Magnum’s margins can expand without relying on further one-off cost actions—especially after the Unilever separation that restructured the business model.
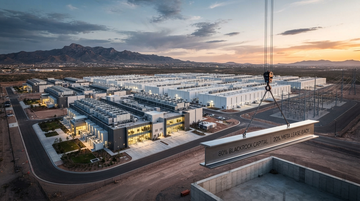
Meta's El Paso JV with BlackRock turns AI real-estate into pension-backed yield—without making Meta the bank
Meta will move the El Paso campus into a JV where BlackRock-managed funds hold 80% and Meta holds 20%, while Meta becomes the sole tenant via a long lease-back. The deal explicitly shifts AI infrastructure from a pure “capex deficit” debate to a “how cheaply can we finance long-lived boxes” debate—because part of BlackRock’s investment is funded with $12.5B of debt.
![Meta Platforms's Q2 FCF crater happens because capex rose faster than cash generation—and it flips the debate from 'earnings' to 'funding discipline'] insight cover](https://images-1379091077.cos.na-ashburn.myqcloud.com/insights/covers/20260730_meta_q2_2026_fcf_craters_ai_capex_double_down_2026_07_360px.png)
Meta Platforms's Q2 FCF crater happens because capex rose faster than cash generation—and it flips the debate from 'earnings' to 'funding discipline']
Meta’s Q2 cash flow shows free cash flow fell to about $1.7B while capex jumped to $30.1B, confirming the “AI capex first” regime with hard numbers. The immediate investor question shifts from whether AI monetizes soon to whether hyperscalers can sustain buybacks/credit ratings while front-loading capex.
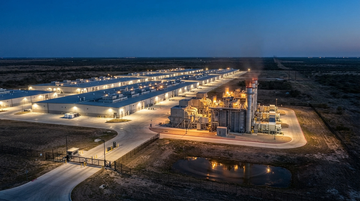
Google's $15B Nexus Loan Is Sovereign Finance in Disguise — and Alphabet's Capex Math Just Got Worse
Alphabet is guaranteeing the Morgan Stanley-led $14B bridge loan on Nexus Data Centers' 1.6 GW Texas gas-powered AI campus for Anthropic, taking ~20% equity in return — the third leg of a $35B+ backstop program that moves frontier compute off Google's balance sheet while keeping it on the hook. With Q2 capex already at $44.9B and free cash flow turning negative, the structure reveals the real constraint: not capital, but the gap between Google Cloud growth and depreciation absorption. Lenders win fees; Broadcom, AMD, and gas-turbine suppliers win volume; the question is what triggers Google's cash calls.
Nscale's $1.65B Anyscale Grab Hands Microsoft a Vertical-Stack Rival It Just Helped Build
London-based neocloud Nscale is buying Ray-creator Anyscale for a reported $1.65B, absorbing the open-source distributed-compute substrate that Microsoft co-engineered as a first-party Azure service just nine months ago. The deal converts a cloud-agnostic Ray ecosystem into Nscale's proprietary full-stack offering, tightening pressure on CoreWeave, Nebius and Lambda Labs while putting Microsoft's $23B Nscale compute commitment on a collision course with the same company's software roadmap.
The Aug 1 “voluntary” 30-day review makes OpenAI and Anthropic buy a government timeline—or lose it
A White House executive order (June 2, 2026) sets up a voluntary pre-release federal review framework for “covered frontier models,” with key agency deliverables feeding into an August 1 implementation milestone. If OpenAI MSFT and Anthropic (unlisted) are inside the first wave, they effectively turn a short window into a durable release-preemption advantage—while everyone else faces a longer, more political customer-acquisition and deployment lag.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.