Latest
The day's market news, with the argument attached
New notes every trading day on earnings, policy and market structure. Each one opens with the conclusion, then the evidence, then the companies it hits.
2026-08-04

Clorox Just Got a Real-Staples “Re-Rate” Test—Purell Is Doing the Work
Clorox’s GOJO/Purell bolt-on did not just add scale—it changed the company’s 2026 outlook math, with guidance explicitly tracking margin headwinds and transaction costs tied to the deal. For investors, the question shifts from “does hygiene sell volumes?” to “can margin-mix from higher-quality hygiene assets defend earnings through the AI-era spend normalization?”
Electronic Arts‘ $55B PIF Take-Private Just Met a Bookings Miss—So the Console Live-Services Pipeline Is the Only Deal Math That Matters
EA’s Saudi-PIF-backed $55B go-private deal is set to close around Aug. 4, 2026, but the timing is now being judged against a Q1 bookings miss. The market’s “deal” framing is secondary: investors should focus on whether EA can sustain console/PC live-service monetization through its multi-year content cadence to make the cash ramp required by an LBO credible.
Gilead Sciences's HIV growth buys time—but only if its R&D spend translates into “next-legs” before Biktarvy peak cash turns into renewal risk
Gilead Sciences reported base business up 8% and raised full-year guidance to expect HIV sales growth of 8% in 2026. But the investable question is how long that HIV duration can keep funding pipeline bets: in FY2025, free cash flow was $9.46B while R&D is ~$5.80B—meaning the “duration” thesis hinges on near-term clinical conversions, not just franchise resilience.
Iron Ore at a 13-Month Low Turns Beijing’s Stimulus Into a Math Problem at ~$95, Not ~$115
A slide in iron ore forces investors to separate “China steel demand” from “headline price.” Using China’s iron-ore import/inventory signals, the real test for the whole bulk-materials chain is whether stimulus can lift steel throughput enough for benchmarks to stay above the economic clear price—otherwise high-cost supply is still punished while US/EU steel margins get a temporary cushion.
Eli Lilly's “Early-Access” Move Is a TAM Pre-Pricing Mechanism
Lilly’s “early access” to its next-gen obesity drug (retatrutide) is not charity—it is a controlled go-to-market rehearsal that can pre-price demand and steer where patients (and cash-pay channels) land once the broader launch hits. In this model, the value comes from learning-and-pricing ahead of approval, while the financials show Lilly can fund growth and scale investment despite periods of low free cash flow.
McDonald’s U.S. Value Push Didn’t Fail—But It May Be Losing Its “Traffic Engine” as Growth Shifts Toward Check
McDonald’s latest U.S. comparable sales growth has remained positive (3.9% in Q1 2026), but the company’s own disclosure framework—where comp sales can rise via average check even as guest traffic slows—makes “value” harder to underwrite purely as traffic recovery. For investors, the key question is whether value meals are still expanding guest counts, or increasingly only remixing purchases in ways that protect revenue while compressing franchise economics.
Merck's “Quarter Beat” Is a Patent-Reset Reality Check
Merck’s latest reported strength shows how much the Keytruda franchise can still carry, but it doesn’t answer the real question: whether Merck has built a durable replacement economics model before biosimilar pressure starts in December 2028. The company also guided FY2026 sales upward into a window that still precedes the hardest 2028–2029 exclusivity step-down.
AI diplomacy is repricing US chips: China’s Mythos anxiety turns the next frontier-model release into a Trump–Xi bargaining input
U.S. policy is building a voluntary, federally benchmarked “covered frontier model” review process for advanced AI with cyber risk, ahead of a Trump–Xi summit sequence. If China is truly focusing on Anthropic’s Mythos-class cyber capabilities as an “offensive weapon” concern, then the next frontier-model decision window is effectively being priced into the same trade corridor that governs advanced AI chip access—making NVIDIA, Broadcom, AMD, and Micron sensitive to diplomacy headlines.
onsemi's guided-up AI data-center demand is shifting the “power bottleneck” from GPUs to SiC and power-silicon
In its latest quarter and outlook, onsemi guided to faster AI data-center momentum, with silicon-carbide and power-silicon demand framed as scaling alongside broader power architectures. The practical investor read: when hyperscalers add AI racks, the spend doesn’t only show up in GPUs/HBM—it increasingly pulls forward discrete power devices, SiC, and server-power capacity, tightening the link between AI capex and onsemi’s growth.
Amazon’s “transaction-entry” defense just got court-tested—AI shopping agents may need a new payments-and-permissions layer
A U.S. judge granted Amazon a preliminary injunction blocking Perplexity’s Comet “agentic” shopping tool from accessing protected parts of Amazon on behalf of users. The ruling reframes AI-agent commerce as a permissions-and-integration problem (not just a scraping or UX problem), which changes who profits: the interface owner, the identity/payment rail, or the discovery layer.
Pfizer's $2.5B save is the easy part; the question is what it funds after the patent cliff
Pfizer has repeatedly expanded its “cost realignment” targets, with the program originally including at least $2.5B of additional net savings expected to be realized in 2024 and later culminating in ~$5.7B through 2026. The hard investor question is whether these savings are protecting (or crowding out) the cash needed for the post-patent-cliff commercial and pipeline reset.
Procter & Gamble's $3.8B Thorne bet shifts “wellness” from shelf risk to premium supply-chain leverage
Procter & Gamble is reportedly paying $3.8B in cash to acquire Thorne, a science-driven supplements brand, with closing expected later in 2026. The investor question is not “does supplements grow?”—it’s whether P&G can add a higher-growth, higher-trust revenue stream without sacrificing the margin discipline that supports its staple-like cash generation.
Prudential Financial's PGIM beat is real—but the deeper signal is whether the business is shifting toward less capital-heavy earnings
In Q1 2026, Prudential Financial reported PGIM adjusted operating income of $190m (+22% YoY), while its insurance-side profitability weakened in the same quarter. The implication for investors: if fee-based growth keeps pacing (and insurance capital intensity keeps easing), PRU may deserve a valuation framework closer to asset managers than traditional insurers.
TikTok’s three pre-trial teen settlements just pushed Meta/Snap/Alphabet into the “Section 230 reserve mark-up” era
TikTok agreed to settle a landmark teen social-media addiction case just before the trial began, after Snap also settled and while Meta and YouTube (Alphabet) faced the bellwether. The result is less about payout size and more about litigation pricing: once one “architected-for-addiction” case resolves early, it increases the probability-weighted loss exposure and forces platforms to carry higher legal reserves—re-anchoring the ad-market’s Section 230 liability discount.
Toyota’s weak-yen “profit” story is increasingly a China-write-off + FX-translation trade, not a demand rebound
Toyota is guiding higher operating profit even as it warns China weakness is persisting, turning the weak-yen tailwind into an accounting translation effect rather than a volume recovery. For investors, that means the next catalyst is less about Japanese pricing power and more about whether FX tailwinds survive and whether China demand stabilizes.
America’s trade deficit shrank because imports fell—watch the supply-chain “pause” behind the headline
In June, the U.S. goods trade deficit narrowed to $101.5B largely because imports of goods fell $8.2B m/m. That looks GDP-friendly on the surface, but it can also signal a demand pause and inventory/freight timing effects—typically showing up first in logistics and in companies with high import exposure.
A Trump-family miner’s Q2 loss says the post-halving margin floor isn’t “policy-proof”
The listed, Trump-family-linked miner American Bitcoin Corp reported a Q2 net loss even while its Bitcoin holdings grew, underscoring that political narrative cannot replace the hard post-halving economics of mining. The result reframes the entire US-listed miner cohort: when hash-revenue and cost/opex structure don’t clear the “all-in” hurdle, Strategy Inc can amplify the upside—while still leaving the downstream balance-sheet reality unchanged.
Waters’ Forecast Raise Suggests Biopharma Labs Are Moving Past a One-Quarter “Freeze”
Waters’ 2026 guidance raise points to demand that’s not just cyclical—especially because it ties growth to diagnostics and lab equipment rather than a broad market normalization. The investor question is whether this becomes a durable replacement/utilization cycle that pulls through consumables and services, or whether it fades as budgets reset.
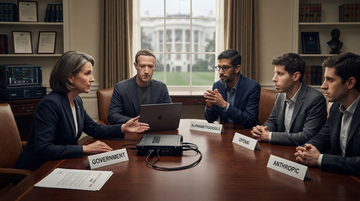
A White House “voluntary” AI safety test became a pre-regulatory negotiation—frontier labs now face a binary choice on access vs. disclosure
A Reuters report says the Trump White House invited Meta, Anthropic, Google, and OpenAI to a sit-down on voluntary government AI safety testing. Combined with the June 2, 2026 executive order’s up-to-30-day access framework, the meeting signals a shift from “standards talk” to controlled, government-mediated model access that can re-price who can move fastest without being forced to reveal too much.
Williams is paying up for a gas-volume thesis the market hasn’t priced in yet
Williams’ up-to-$5.5B all-cash-and-stock deal for Momentum Midstream is an explicit bet that AI-driven power demand plus LNG feedgas will tighten US gas gathering capacity—starting in the Haynesville-to-Gulf corridor. The key investor question is whether this creates a step-change in long-haul contracted volumes (and therefore cash flow durability) rather than just adding regulated/fee-like mileage.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.