Latest
The day's market news, with the argument attached
New notes every trading day on earnings, policy and market structure. Each one opens with the conclusion, then the evidence, then the companies it hits.
2026-07-22

The US–Saudi Nuclear Pact’s Real Risk Isn’t Reactors—It’s the Fuel-Cycle Loopholes Congress May Force Closed
As of July 2026, the US–Saudi civil nuclear pact is still being debated in Washington because the draft safeguards framework reportedly falls short of the IAEA “Additional Protocol” (and the “gold standard” approach) even as it tentatively permits Saudi enrichment and/or reprocessing. That mismatch creates a fuel-cycle risk that could delay or reshape US vendor participation and the supply-chain plans tied to Saudi nuclear industrialization, regardless of how fast reactor contracting moves.
Wistron's $761M Fort Worth AI-Server Factory Is a “Domestic Scale” Test—Here’s What Could Still Break in Mid-2026
Wistron is building two Fort Worth AI supercomputer manufacturing sites totaling $761M, with the facilities expected to be operational by early 2026 and ramping mass production over the following 12–15 months. The deal is heavily structured around delivery/performance triggers (including minimum investment, jobs, and salary floors), turning execution capacity—not just demand—into the primary risk. The operational bottlenecks to watch aren’t only factory construction; they’re supply of server components, quality ramp, and the ability to sustain output once “pilot” becomes “production.”
Wistron's $700M Texas AI-Server Factory Is the “Domestic Scaling” Test for NVIDIA’s Supercomputer Supply Chain
Wistron opened a $700M, 324,000-square-foot AI-server assembly-and-test facility in Fort Worth on July 21, 2026, built to support NVIDIA’s next wave of AI systems. The U.S. move matters less because it changes the chip source—and more because it stress-tests integration, yield, thermal/liquid-cooling readiness, and speed-to-ramp for high-volume Blackwell Ultra and Vera Rubin “system” production. For investors, the key question is whether domestic manufacturing reduces latency and risk enough to win sustained orders without permanently worsening Wistron’s working-capital and cash-flow profile.
Yen at 163+: Why Intervention-Pressure, Not Japan’s Rates Alone, Is the Carry-Trade Shock Point
As of July 22, 2026 the yen slid past 163 per US dollar, keeping markets on alert for another Japanese authorities intervention attempt. The key risk for carry trades is not simply that USD/JPY is high—it’s that repeated “intervention resolve” narratives can trigger fast, liquidity-driven unwinds when positioning is crowded. That turns a macro FX move into a cross-asset volatility event, with the intervention “mechanism” and speed mattering as much as the level.
Zhongji Innolight's $7B Hong Kong IPO Is a Real-Time Demand Test for AI Optical Interconnect
Zhongji Innolight’s Hong Kong listing approval (expected to raise about $7B) is more than a capital-markets milestone—it’s a market verdict on whether AI data-center buildouts will keep translating into high-margin optical transceiver demand. The company’s disclosed growth profile (Q1/3M 2026 revenue and gross margin acceleration) plus its supply-chain scaling plans are the core reason this IPO can be used as a near-term benchmark for AI optical infrastructure capex intensity.
2026-07-21
Anthropic’s $1.5B Copyright Settlement Is a Liability “Floor” for Frontier AI—Because the Court Split Fair Use for Training from Infringement for Retaining a Pirated Library
On July 20, 2026, a U.S. judge granted final approval to Anthropic’s $1.5B class-action copyright settlement, awarding $101M in attorney fees and confirming 91%+ participation. The case hinged on a sharp split: the court accepted that LLM training can be fair use, but found Anthropic liable for storing millions of pirated books in a “central library.” For investors, the investable takeaway is not that “training is illegal,” but that the liability boundary moves toward dataset acquisition/retention and can become a predictable cost of doing business across frontier model labs.
Head of US AI Safety Agency CAISI Resigns After Just 3 Months — What It Means for Frontier AI Oversight
On July 20, 2026, Reuters and CNBC confirmed that Chris Fall resigned as Director of the Center for AI Standards and Innovation (CAISI) — the federal AI testing institute under the Department of Commerce that replaced the prior AI Safety Institute — just three months after his appointment. The departure is the latest shakeup in the Trump administration's AI oversight team and comes amid intensifying negotiations with frontier-model developers (OpenAI, Anthropic, Google) over staged releases, government access, and how to test for national-security risks. It raises questions about the stability of US AI regulatory infrastructure as cheaper Chinese open-weight models accelerate.
CAISI’s Director Churn Signals US AI Standards Will Lag—Even as the White House’s Security-and-Testing Agenda Accelerates
Chris Fall’s resignation as director of the Center for AI Standards and Innovation (CAISI) on July 20, 2026 extends a CAISI leadership whiplash: three directors in ~five months, following David Sacks in March and Collin Burns in April. Because CAISI is explicitly tasked with translating the White House’s AI safety-and-standards agenda into model evaluations and security guidance, turnover threatens continuity at the exact moment compliance expectations are rising. For investors, this increases the value of vendors that can sell “standards-adjacent” testing, secure compute, and AI governance tooling—while raising near-term execution risk for any bet that waits on a stable federal test regime.
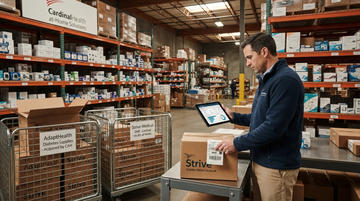
Cardinal Health Buys AdaptHealth Diabetes Unit + Strive Medical for $360M Cash — Home-Care Roll-Up Continues
On July 20, 2026, Cardinal Health announced definitive agreements to acquire AdaptHealth's Diabetes Health business (~$235M cash) and Strive Medical — a DME supplier serving 20,000+ patients — for a combined ~$360M in cash. The deals expand Cardinal Health's Cardinal at-Home Solutions segment, deepening its position in diabetes supplies and durable medical equipment. AdaptHealth framed the divestiture as sharpening focus on its core sleep, respiratory, and HME businesses.
GM’s Q2 2026 Margin Beat Looks Like a Tariff-Refund Bridge—But EV Losses Leave the Sustainability Question Wide Open
General Motors’ Q2 2026 print lands at the intersection of two margin drivers: tariff-related refund expectations on one side and continuing EV-related cost pressure on the other. With US sales down 4.2% Y/Y in Q2 and ongoing EV strategic realignment charges, the key investor question is whether tariff benefits persist long enough to offset EV profitability drag in 2026.
Google’s “Frozen v2” (Gemini-aware) chip targets 6–10× better tokens-per-watt by 2028—reshaping the AI inference hardware stack
Reuters/The Information reports Google is developing an internally named “Frozen v2” server chip that bakes Gemini model elements into hardware, targeted for as early as 2028 deployment. The chip is expected to deliver 6–10× more AI tokens per unit of power than Google’s latest custom silicon and is intended to complement (not replace) Google’s existing TPU roadmap—aiming to relieve compute bottlenecks as AI capex rises. For investors, the key question isn’t only whether the chip works, but whether Google can turn improved tokens-per-watt into measurable inference cost leverage versus competitors’ GPUs/accelerators, with TSMC likely central to the advanced packaging and manufacturing ramp.
Google Develops 'Frozen v2' Chip With Gemini Baked Into Silicon — A 6-10x Efficiency Play for 2028
Reuters reported on July 20, 2026 that Google is developing a new server chip codenamed 'Frozen v2' that embeds elements of its Gemini model directly into the hardware. The chip is projected to be 6–10x more efficient than current custom Google AI silicon (measured by tokens served per watt) and is targeted for deployment as early as 2028. The 'Frozen' program runs alongside but does not replace Google's existing TPU roadmap (TPU 8t/8i announced at Cloud Next '26) and signals an architectural shift toward model-silicon co-design, putting further pressure on the GPU-centric AI compute stack.
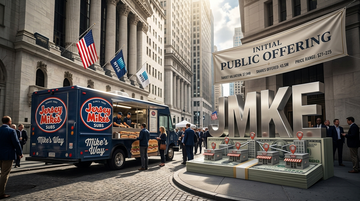
Jersey Mike’s IPO at up to $7.94B is a franchise-math bet: valuation hinges on sustaining high AUV while Blackstone sells into the public market
Jersey Mike’s disclosed IPO terms of 43.5 million shares in a $21–$25 range, targeting up to a $7.94B valuation and up to $1.09B of proceeds. The core investor story is not restaurant-level earnings—it’s franchise royalty economics backed by very high systemwide sales per unit ($4.217B systemwide in fiscal 2025) and an asset-light footprint (only 36 company-owned stores out of 3,300). For Blackstone, the deal is also a classic PE exit: a public listing that monetizes control while keeping upside tied to continued store growth (including an earn-out tied to reaching 4,000 global stores).

Brookfield+[CPP Investments] to Take LXP Industrial Private for $5.2B—Industrial REIT M&A Is Pricing Control, Not Just Rent
Brookfield Asset Management and CPP Investments agreed to buy LXP Industrial Trust in an all-cash deal valued at about $5.2B (including net debt) at $61.20/share, a double-digit premium with a 40-day go-shop window. Using LXP’s recent fundamentals, the offer implies a rich takeover multiple versus the last several years’ revenue and cash flow—suggesting buyers are paying for asset/tenancy control and a path to recapitalize rather than buying a cheap stream of rents. For investors, this deal is a real-time “private-market bid” read-through to where industrial REIT control premium (and execution risk) is heading in 2H 2026.
3M’s Q2 2026 Setup: A Small EPS/Revenue Miss Is Less Concerning Than the Tariff-Cost Test to Its Back-Half Organic Growth
3M (3M Company) delivered Q2 2026 results that were slightly below consensus on both adjusted EPS and revenue, while reiterating full-year guidance for ~3% organic sales growth. The market focus is whether the post-Solventum footprint can keep the organic-sales pace as tariff drag hits consumer-leaning SKUs and pricing/mix. With recent quarterly revenue running in a narrow band (~$6.0B–$6.5B), the “execution” question is not demand collapse—it’s margin bridge durability.
Oracle's $165B AI Megacampus Bet Hits Cost Overruns — BBB Rating, $55.7B FY26 Capex, New Debt/Equity Raise Looms
On July 20, 2026, multiple outlets reported Oracle is facing multibillion-dollar cost overruns across its $165B AI data-center buildout, including its flagship Wisconsin ($15B, ~1 GW) and El Paso/Texas (Project Jupiter) sites. FY2026 capex reached $55.7B — exceeding Oracle's own $50B guidance and up 162% YoY. The company has signaled further debt and equity issuance to fund expansion while its credit rating has slid to BBB, triggering a lawsuit with the Wisconsin Public Service Commission over $100M+ annual financial guarantees. Concerns include local power-grid constraints in New Mexico and broader questions about hyperscaler AI infrastructure returns.
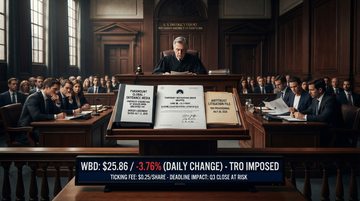
14-Day TRO Forces Paramount Skydance to Pause the $110B WBD Deal—The Mega-Media M&A Era’s First Real Court Litmus Test
On July 20, 2026, a U.S. district judge granted a 14-day TRO blocking Paramount Skydance’s $110B acquisition of Warner Bros. Discovery (through at least an Aug. 3 hearing). The order turns what had been “regulatory risk” into an economic squeeze: WBD shares dropped ~3.8% that day and the deal’s structure includes a $0.25-per-share ticking fee if the close slips past Sept. 30. For investors, the core question is whether this is a short delay—or the opening move in a longer antitrust fight over wide-release theatrical distribution and cable power.
Reformation’s IPO Terms Price a “Profitable DTC” Outfitter for Public Markets—But the Margin Story Still Hinges on Tariffs and Scale
Reformation’s ref S-1/A sets a $15.00–$17.00 range for a roughly $225M raise on $507.1M of 2025 revenue and $12.6M net income, with ~90% of sales from direct-to-consumer. The filing’s most investment-relevant detail isn’t the DTC mix—it’s how much reported gross margin and operating leverage swing around tariff-driven costs/refunds and store expansion discipline. If Reformation can convert store growth into steadier margins, the “profitable sustainable DTC” thesis looks investable; if not, the valuation can compress fast even with positive net income.
Scribe Therapeutics’ $100M IPO Is the First Public “Pure-Play CRISPR Risk Read” of 2H 2026—And It’s Valuing Epigenetic Gene Editing Like a Clinical-Stage Bet
Scribe Therapeutics (Scribe Therapeutics) set Nasdaq IPO terms for 7.15M shares at $13–$15, seeking about $100M at the low end and up to $107.2M at the top, with Sanofi participating in a concurrent purchase. The S-1 frames its core value creation around early, in-human data for its lead epigenetic CRISPR program (Scribe Therapeutics STX-1150]) and preclinical progress for two lipid-risk follow-ons funded partly by CIRM grants. For investors, the key question isn’t just CRISPR’s science—it’s whether public markets will underwrite early-stage execution risk after the post-2024/25 biotech window reopened.
Trump Slaps 50% Tariffs on $20B of Canadian Goods Under Section 338 — Markets Brace for New Trade Shock
On July 20, 2026, President Trump signed three proclamations under Section 338 of the Tariff Act of 1930, imposing a 50% tariff on approximately $20 billion of Canadian goods — including motor vehicles, wine, spirits, beer, dairy, cement, lumber, and even hockey sticks — to retaliate against Canadian trade discrimination. The tariffs take effect in 30 days and apply regardless of USMCA status. Energy, potash, fish, Section 232 products, and critical minerals are exempted. Cited drop data: Canadian imports of U.S. vehicles fell ~22% ($5.6B) from April 2025 to March 2026; U.S. alcohol imports to Canada fell ~81% ($582M) from March 2025 to February 2026.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.