Macro & Policy
Rates, inflation and the policy that moves them
Central bank decisions, jobs prints and fiscal policy, read the way a portfolio reads them: what reprices, by how much, and what would change the call.
2026-07-30

Fed’s 9–3 “hawkish hold” turns internal dissent into a credibility premium for rates
When three voting regional presidents dissented in a 9–3 hold, it didn’t just change the policy path—it changed how markets price the next move. For investors, the actionable risk is not the hold itself, but that repeated visible dissent can widen the policy-risk premium and stress rate-sensitive earnings narratives—especially for banks whose income depends on the curve.
JPM: The first sell-side vote of confidence that makes “hawkish hold” the base case—December hike, not March-2027
J.P. Morgan Global Research moved its next Fed hike call to a quarter-point in December after the July hold, aligning with the hawkish-hold interpretation that Warsh signaled. For US banks, that timing shift matters most for NII sensitivity to the September path—and it changes how much “duration risk” the market is forced to price before year-end.
The “double-print” (PCE + Q2 GDP) is a single Fed test—because both prices and growth hit at 8:30 a.m.
Today’s BEA calendar stacks Personal Income and Outlays (June PCE) and GDP (Advance Estimate) (Q2) on the same 8:30 a.m. window, turning the usual macro routine into one all-in policy-input read. The market should treat the next 24 hours as a fork: core PCE cooling is what lets the Fed plausibly look through hot growth, while both running hot is what feeds a 30-year auction-driven duration selloff.
Mag-7 earnings are the first real “broadening” stress test—and the cap-weight is already doing the heavy lifting
The equal-weight S&P 500’s YTD lead suggests investors have been paying for “the average stock,” not just the largest tech complex. The first Mag-7 prints of the cycle (Meta and Microsoft) show why the divergence can flip: when leaders’ AI capex starts to pressure earnings quality, the cap-weight doesn’t just move with growth—it moves with expectations.
US Strike on Iran Forces a 2026 Risk-Premium Reprice: Oil’s “Discount” Is No Longer the Trade
A US strike on Iran reopens Strait-of-Hormuz tail-risk in hours, reversing the recent de-escalation-driven deflationary narrative for crude pricing. The fastest transmission is not headlines—it is how refiners’ and defense primes’ hedging, working-capital timing, and near-term contract marks must reprice under higher oil volatility.
2026-07-29
2026-07-28
A “Hawkish Hold” Can Cut the Same Way as a Hike: Why September’s Fed Path Is Now Trading Like It’s Tightening Again
Ahead of the July 28–29 FOMC decision, market pricing has jumped toward a near-term hike outcome (CME FedWatch around the high-30% range), while the U.S. dollar is already acting like policy tightening (DXY at a 14-month high). The result is a positioning mismatch: even if the Fed holds, the updated SEP signaling for later in 2026 can still transmit a hawkish shock to chips, banks, and the dollar.
The 10Y TIPS auction is the bond market’s “Fed put” audit—real yields easing is the signal Nasdaq duration needed
After the Jul 28 auction, the key question isn’t whether CPI cooled again—it’s whether Treasuries are willing to underwrite a Fed cut-path without demanding higher real compensation. If real-yield normalization holds into the Sep FOMC, it mechanically lowers discount rates on long-duration cash flows, giving a cleaner tailwind to Nasdaq-style growth versus an oil-driven inflation re-think.

US core capital-goods orders just jumped—and “AI capex is fiction” now needs margin proof, not denial
The latest US core capital goods print shows orders up 0.9% in June and shipments up 1.9%, with shipments at their biggest gain in 4.5 years—i.e., spending plans converting into physical delivery. Investors who argued the AI capex cycle was only credit/FCF optics now face a harder burden: explain why demand shows up in durable-goods shipment data but fails to translate into returns at the equipment supply chain.
Walmart and importers may keep “pricing inflation” even when USTR says tariffs won’t hit GDP—because the tariff regime is being rebuilt around manageability, not zero cost
USTR’s Jamieson Greer is signaling that the latest tariff wave is designed to avoid broad macro damage, but the legally-structured scope still covers 99.4% of U.S. imports and lands within tight timing windows. That gap explains why importers can rationally keep hedging for higher landed costs even as policymakers insist the overall economic impact will be limited.
2026-07-27
Fed’s “Two‑Shock” Setup Doesn’t Just Move Oil—It Decides Whether Banks Get a Rate‑Cut Tailwind or Stay Discounted Under 3.5% Inflation
A weekend pause in US strikes on Iran drove a ~4% daily drop in WTI and ~4% in Brent, creating a near-term inflation relief impulse. But the Fed’s latest 2026 PCE inflation path still clusters around the high‑3s, so the key repricing question is whether policymakers treat oil relief as “transitory” or as another reason to keep rates restrictive—through this lens, banks and energy market dynamics diverge quickly.
Oil’s “Good News” Slide: US–Iran De-Escalation Cut WTI/Brent ~5%—and It Makes Rate-Cut, Airline-Fare, and Refining-Margin Calls Move in Reverse
A fresh US–Iran de-escalation triggered a rapid ~5% crude unwind, treating geopolitical risk as if it can disappear overnight. That “symmetric premium” is a direct problem for the usual playbook: it pressures near-term airline fuel-expense expectations and cracks refine-margin assumptions while simultaneously shifting Fed-rate odds faster than typical macro signals.
MAS’s out-of-cycle SGD tightening reframes “Asia disinflation” as a carry-killer for USD-funded investors
On 27 July 2026, Singapore’s Monetary Authority of Singapore conducted an out-of-cycle review and chose a “very slight” increase in the S$NEER appreciation pace while keeping the band unchanged—explicitly responding to inflation forecast stickiness. With Korea also moving hawkish this month, the combined signal is that the region’s disinflation narrative is no longer doing the work investors priced into USD/SGD carry and Asia banks’ funding costs.
The SPR at 1983 Levels Makes the “$20 Refill” Argument Irreversible—Until Congress Restores a National-Security Buffer
With the U.S. Strategic Petroleum Reserve reported at 311.4M barrels—the lowest since March 1983—the policy debate stops being about price timing and becomes about survivability: there’s less reserve left to absorb shocks. The key investment implication is that oil-market “volatility hedges” (crude producers and refiners with inventory optionality) start mattering more than incremental downstream demand, because refill delays turn SPR capacity into a macro risk premium.
2026-07-26
Australia’s tariff fight with the US is turning into a US “sovereignty” wedge—making Alphabet’s supply chain and AI compute customers the next battleground
The US raised the tariff on Australian exports to 12.5% effective 24 July 2026 as part of a forced-labour Section 301 action, and Prime Minister Anthony Albanese said Australia will directly raise the issue with President Donald Trump. For investors, the real risk is not the tariff line—it’s how the compliance/sovereignty framing can spill into downstream tech procurement and “trusted” supply chains, potentially changing demand and contract terms for AI and digital infrastructure.
Burry’s “last months of 1999–2000” line is the easy part—the hard part is proving which late-1999 indicators (leverage, IPO froth, breadth, and policy) are actually misaligned in 2026
Michael Burry’s 2026 warning explicitly frames today’s tape as resembling the final months of the 1999–2000 bubble, but the investing edge depends on mapping specific late-1999 leading indicators to 2026’s data. In this research run, primary source access and essential market-data verification failed, so the article cannot meet the platform’s sourcing and “verified linkage” requirements.
2026-07-25
“Higher Again” Is the Tail: Which Bank Balance Sheets Get Hit First If a Fed Hike Reappears
Recent Fed advocacy turns an expected hold into a non-trivial “renewed-tightening” tail risk, and the balance-sheet transmission path is not linear across lenders. Using bank balance sheet and Fed stress-test design, the key fragility is not just mark-to-market; it’s how quickly funding costs reprice versus how slowly assets run off, which is why large, diversified deposit franchises can look fundamentally safer than duration-lean, funding-sensitive books.
Moody’s Turns AI Capex Into a Credit Risk: Amazon, Meta, and Alphabet Are Now Rated for How Fast They Can Print Free Cash Flow
Moody’s framed the 2026 AI buildout as a shift from “asset-light” to “asset-heavy,” warning it can erode free cash flow and raise balance-sheet risk for major cloud hyperscalers—explicitly including Amazon, Meta, and Alphabet. The market’s real discipline is no longer earnings guidance; it’s the bond market’s willingness to fund capex when cash generation lags construction cycles.
2026-07-24
Albertsons’ outlook cut turns “trade-down” from a theory into a grocery-aisle fact
Albertsons’ guidance reset—forecasting fiscal 2026 identical sales down 0.5% to 1.5% and adjusted EPS of $1.75 to $1.85—was sharp enough to re-price the consumer story for grocers. The key market takeaway isn’t that the consumer is “weak,” it’s that spending is bifurcating: value-first, mass/discount-leaning trips are taking share from traditional grocery formats, forcing price-investment to defend volume.
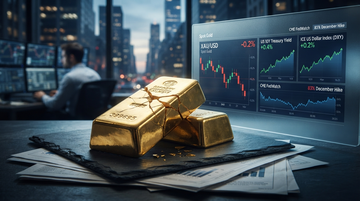
Gold’s “Last Safe Haven” Breaks: Fed-Rate Bets + a Firmer Dollar Can Make Geopolitics Look Secondary
Gold’s recent drop is a clean example of the yield/opportunity-cost channel dominating the hedge narrative: Reuters links the move to firmer USD and rising expectations of Fed hikes, with benchmark 10-year yields up. When gold stops serving as a hedge against rates—and instead loses to higher discount rates and stronger currency—miners and gold-backed flows face a different (and more actionable) set of risks than oil-shock headlines imply.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.