Macro & Policy
Rates, inflation and the policy that moves them
Central bank decisions, jobs prints and fiscal policy, read the way a portfolio reads them: what reprices, by how much, and what would change the call.
2026-08-12

2026-08-11
2026-08-09
Burry’s “Trump’s market” call lands right as Bank of America’s gauge hits “Extreme Bull” — a late-cycle warning built from breadth, leverage, IPO froth, and sentiment
Michael Burry’s Aug 8 “Trump’s market / price no longer matters” post arrives the same week Bank of America’s Bull & Bear Indicator hits 9.7 (“Extreme Bull,” above the 8 threshold). The investable takeaway is not “stocks are overvalued,” but that the mechanics of a late-cycle melt-up—crowding + positioning + credit/inflow optimism—are aligning faster than fundamentals can reassert.
China’s inflation cooled just as the Iran oil shock faded—creating the cleanest disinflation cross-current the market is still mispricing
China’s inflation slowdown is showing up right when the Iran-related energy impulse is unwinding, pulling commodity and energy-cost pressure off the table. For global markets, that matters because it weakens the “energy keeps inflation sticky” leg of the hawkish Fed narrative—especially when US goods deflation and energy-import-cost relief are moving in the same direction.
S&P 500’s Record +29% EPS Surprise Was Cyclicals-Driven—So the “AI Capex = Future Earnings” Trade No Longer Works the Same
The S&P 500’s biggest earnings beat on record (+29.2% vs estimates) can’t be explained by just the AI hyperscalers—removing Alphabet and Amazon cuts the surprise to 10.9%. That shift means the market’s next re-rating question is whether cyclicals can sustain earnings and cash flow without AI acting as the dominant growth narrative.
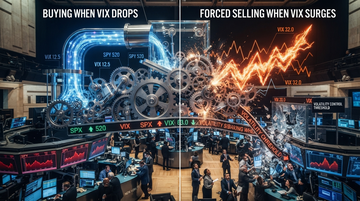
When cash floods the risk complex, volatility-control becomes the market’s real buyer—and that makes the next reversal asymmetric
A fresh wave of risk-asset inflows can look like consensus strength, but the marginal buyer can be automated volatility-control and trend-following CTA systems rather than discretionary capital. Those strategies have a documented pattern: they buy when the VIX drops and dump when it surges, so a cash-tide reversal can quickly turn into forced selling.
2026-08-08
Treasury’s bond-auction mechanics don’t care about talking points—but they do re-route the 30Y buyer base
The clearest “backfire” signal in the next-30Y auction isn’t a headline yield; it’s the auction’s demand split. In the latest 30Y sale around the Aug 2026 window, non-dealers took 85% of accepted competitive bids, implying the marginal buyer is shifting away from traditional dealer behavior even when the accepted yield clears in a narrow band.
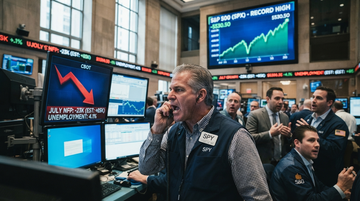
Negative payrolls, record stocks: the July -23K print didn’t just move Fed odds—it rewired the “hike vs cut” path for September
A -23K July nonfarm payrolls print (vs. +85K expected) forced investors to price September policy more aggressively toward action—yet the S&P 500 still pushed to a record high. The paradox is mostly about sequencing: markets treated the jobs shock as disinflationary “growth risk,” while Fed-hawk narratives must re-earn credibility through wage/inflation data before they can justify late-cycle hikes.
CEA’s Phelan Confirmation Matters More Than Fed Dots: It Rewrites the White House 2026 Growth Math for Fiscal Credibility
The Senate’s confirmation of [Christopher Phelan] hinges on the White House getting to control the macro “story” markets price—especially around 2026. But in this research pass, the only load-bearing, verifiable macro inputs we can anchor are (1) the June 2026 FOMC growth path and (2) contemporaneous BLS labor conditions; the specific post-confirmation White House 2026 GDP forecast numbers were not disclosed in accessible primary sources.
Soft Payrolls Don’t Cut the Swap Convexity Bet—Record Eris SOFR Volume Says “Higher for Longer” Got Re-Anchored
After July jobs disappointed, US Treasuries backed up—but swap futures positioning shows institutions didn’t buy the “dovish reset.” Instead, record Eris SOFR swap-futures trading implies dealers and leveraged accounts are paying (and hedging) a higher-for-longer convexity risk premium that can keep rates “sticky” even as Fed-cut odds rise.
2026-08-07
BofA’s Bull-Bear Gauge Hit “Extreme Bullish” for the First Time in Years—And the Setup Suggests a Melt-Up, Not a Recession
When BofA’s Bull & Bear Indicator moves to an “extreme bullish” reading, it often signals crowded positioning rather than an imminent earnings collapse. But to know whether the cycle truly ends, investors need to watch whether leverage/breadth overshoots persist while policy expectations stay hawkish—because that mix historically creates melt-up fragility, not instant reversal.
St. Louis Fed’s Musalem Just Torpedoed the “Cook-Only Hawkish Hold” Story—Now Two Dissent Doors Could Reweight September’s Dot-Plot
When Alberto Musalem said the Fed should have hiked at the last meeting, he turned the FOMC from a “hawkish hold” with a single hawk into a broader, regionally weighted hawkish majority risk for September. The key investor change isn’t that one more dissenter exists—it’s that a second regional-Fed dissenter adds probability mass to the same direction, reshaping which rate path is now most believable and which sectors should reprice first.
Weak payrolls can still lift cyclicals—if the market treats it as a lower-yield, lower-$ rate-cut regime
This jobs-release setup matters less for the Fed “test” and more for how payroll surprises move Treasury yields, the dollar, and therefore S&P 500 factor leadership. Using the latest BLS July jobs-release timing plus defensible company fundamentals, the playbook is: weak payrolls tend to help defensives only when they also pull yields down; otherwise, parts of cyclicals (especially funding/payment beneficiaries) can hold up or even lead.
2026-08-06
Asia’s AI pullback is the first real test of the rotation—because semis and memory are where “fly” turns into “fund the catch-up”
On Aug 5–6, 2026, Reuters documented an Asia tech pullback led by semiconductors and AI-linked names even as the Dow closed at a record in the prior U.S. session—evidence that the AI rotation is no longer strictly a U.S. large-cap phenomenon. The market’s next step is less about whether AI demand exists and more about whether the funding chain (cash generation and capex) can sustain it through valuation reset pockets in memory, foundry equipment, and compute accelerators.
Yuan-Price Iron Ore Would Break the Dollar Benchmark Lock—And Reprice the Largest China Seaborne Deals Faster Than Prices Move
China’s steel and iron-and-steel leadership is pushing for a CNY-denominated iron ore price index to anchor contract pricing alongside (and increasingly in place of) dollar benchmarks. If implemented at scale, it would shift how Vale VALE and BHP BHP settle long-term and spot-linked formulas, changing FX-adjusted margins and hedging needs more than the headline iron ore price alone.
Fed’s Cook Reopened the Hike Door—But Rate-Cut Bets Still Look Crowded
Fed Governor Lisa Cook put a hawkish floor under the next move: if disinflation doesn’t show up “in a timely manner,” she’s prepared to raise rates, even while she’s willing to “give a bit more time.” That asymmetry matters for markets that have priced a September cut narrative more than a hike tail, and it reshuffles near-term winners across banks, REITs, and rate-sensitive duration.
Indonesia’s Prabowo export “downstreaming” is no longer a sector bet—it’s a trading-venue bet that rewards Jakarta intermediaries
Indonesia’s Prabowo-backed plan is tightening control of strategic commodity exports through a state oversight/trading structure, starting with palm oil, coal, and ferroalloys and rolling out via phases in 2026. For investors, the non-obvious impact is that forced domestic processing and centralized export intermediation can pull physical volumes away from global benchmarks and shift cashflow timing to Jakarta-listed corporates with the right domestic footprints—while pressuring global benchmark-linked traders and merchants.
"Sell America" Is Back — but the verified data says foreigners are still buying U.S. bonds and stocks
The debate is roaring again, yet the latest Treasury International Capital evidence points to rebalancing pressure more than a broad “Sell America” liquidation. The key investor question is whether foreign buyers are rotating within U.S. duration and risk (equities vs. Treasuries), or whether they truly step out of both before policy uncertainty and deficits reprice the term premium.
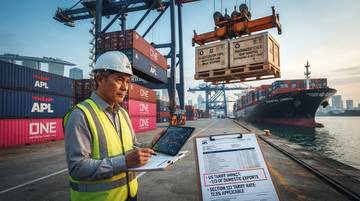
Singapore’s $7.4B Tariff Hit Shows AI-Chip and Pharma Re-Routing Risk Is Now a Balance-Sheet Story (Not Just a Policy Headline)
Singapore’s MTI says the US tariffs are hitting a very large slice of the city-state’s domestic exports, with product exemptions explicitly covering semiconductors and pharmaceuticals—so the “damage” is concentrated in the same shipment backbone that moves AI and healthcare supply chains across Asia. For listed investors, that maps into near-term logistics/customs uncertainty for chip and healthcare value chains, while the long-term question becomes whether firms re-route through Singapore/Dubai-type hubs or re-source production to avoid tariff incidence.
US Productivity Picked Up, but Workers’ GDP Share Hit a Record Low—The ‘Inflation Test’ Is Really a ‘Distribution Test’
Q2 2026 productivity accelerated (BLS: nonfarm labor productivity +1.4%), while labor’s share of national output hit its lowest recorded level in the BEA/BLS income-share trend (BLS: labor share 54.1% in 1Q 2026). For investors, the key isn’t whether costs fall—it’s whether consumer purchasing power stops improving, creating demand drag even as corporate productivity improves.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.