Macro & Policy
Rates, inflation and the policy that moves them
Central bank decisions, jobs prints and fiscal policy, read the way a portfolio reads them: what reprices, by how much, and what would change the call.
2026-07-16

Morgan Stanley's Record Wealth Flows Turn the IPO Boom Into a Fee Machine
Morgan Stanley's second quarter showed that the bank is no longer just trading a volatile tape. It is converting IPO and M&A activity into durable wealth assets, and the scale of those inflows says the fee cycle still has room to run.
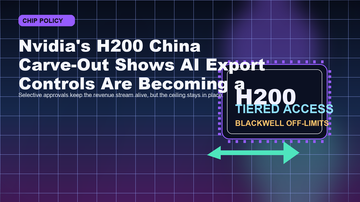
Nvidia's H200 China Carve-Out Shows AI Export Controls Are Becoming a Tiered Market
The latest H200 approvals do not reopen China. They make the AI chip war more granular: chip generation, named buyers, and compliance burden now define the market.
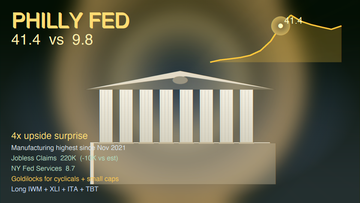
Philly Fed Manufacturing Surges to 41.4 vs. 9.8 Consensus - The 4x Upside Surprise Is the Goldilocks Confirmation for the 2026 Manufacturing + US-Exceptionalism Cycle
The Philadelphia Fed Manufacturing Index surged to 41.4 in July 2026, vs. consensus 9.8 (~4x upside surprise), the highest since November 2021. New orders, shipments, and employment all accelerated. Combined with jobless claims at 220K (-10K vs consensus) and a softer Retail Sales print (-0.2% MoM ex-autos), this is the cleanest goldilocks setup for the 2026 manufacturing + US-exceptionalism cycle. The read-through is for cyclicals + short duration + small caps.
June Retail Sales Rose 0.2%, but the Real Signal Is a Split Consumer and a Fed That Still Cannot Relax
U.S. retail sales increased 0.2% in June, while ex-gas sales rose 0.7% and the control group gained 0.5%. The soft headline looks like consumer cooling, but the details say something more useful: spending is shifting, gas is masking strength, and the Fed still has to decide whether resilient demand or softer inflation is the bigger risk.
South Korea's AI Chip Boom Hit a Leverage Wall as SK Hynix and Samsung Electronics Drag the KOSPI Into a Bear Market
The July 16 selloff did not break AI memory demand. It exposed how crowded the trade had become after months of leverage, retail momentum, and rate-sensitive positioning.
Truth API Turns Trump Media Into a Market-Data Toll Booth - and That Changes the Incentives for Anyone Trading on Truth Social
Trump Media said it will launch Truth API, a licensed real-time feed of top Truth Social accounts for financial institutions. The obvious read is monetization. The deeper read is that the company is trying to turn political attention into a data product, which creates a new market structure risk for traders who already rely on Truth Social as an information source.
2026-07-15
Australia's New AI Data-Center Rules Turn Power and Water Into the Next AI Capex Tax
Australia's July 15-16, 2026 policy shift says large AI data centers must secure their own power, cover their connection costs, manage peak-load behavior, and use water efficiently. The headline is about regulation, but the real message is capital discipline: AI infrastructure is no longer just a software or hardware spend, it is a grid, water, and permitting problem. That matters for Vertiv, Eaton, Equinix, Digital Realty, and every hyperscaler trying to scale demand without colliding with local utility politics.
BlackRock Crossing $15.3 Trillion AUM Turns Passive Flows Into the Real Market-Structure Trade
BlackRock reported Q2 2026 adjusted EPS of $13.91, revenue of $7.084 billion, and $15.3 trillion of assets under management after $192 billion of second-quarter net inflows and $321 billion in first-half inflows. The headline matters because it shows how equity beta, ETF dominance, and private-markets expansion are feeding the same fee engine. The stock's move was just the first-order reaction; the deeper read-through runs to State Street, Charles Schwab, KKR, Blackstone, and the active-vs-passive balance across the asset-management complex.
China's 4.3% Q2 GDP Reopened the Beijing Stimulus Trade — And the Nvidia H200 Path With It
China's Q2 2026 GDP printed 4.3% year-over-year, the weakest since Q4 2022 and below Beijing's 4.5%-5% full-year target. Real estate investment fell 18%, fixed-asset investment dropped 5.7% in H1, but industrial output rose 5.3% and retail sales rebounded to +1% from a -0.6% reading in May. The combination forced Beijing into a third-quarter policy-easing stance, which markets priced through China tech, the yuan, and a quiet re-rating of Nvidia on H200 export hopes. Alibaba, Tencent, PDD Holdings, BYD, and the China-exposed cyclicals all move with this trade.
Gemini Space Station Is Down ~88% From Its $37 IPO - And the Verified Fundamentals Define What the Crypto-IPO Cohort Actually Is
Gemini Space Station closed at $4.34 on July 14, 2026, down ~88% from its $37 IPO price, on light volume of 808,052 shares. The 52-week range is $3.83 to $45.89. Market cap is $548.01 million. TTM revenue is $194.522 million. Net margin is -278.90%. EPS is -$10.87. EBITDA is -$324.18 million. Debt-to-equity is 102.68%. CEO is Tyler Winklevoss; President is Cameron Winklevoss. The verified fact set says the crypto-IPO cohort is being repriced by fundamentals, not just sentiment. Coinbase, Circle, and the spot Bitcoin ETFs are the cleaner reads on the broader digital-asset complex.
Trump's 24-Hour Hormuz Toll Reversal Was the First Real Test of the Global Shipping Industry's Leverage
On July 14, 2026, U.S. forces struck Iranian targets and reinstated the naval blockade of Iranian ports. President Trump simultaneously announced a 20% toll on cargo transiting the Strait of Hormuz via Truth Social. Within 24 hours, the policy was reversed and replaced by 'Trade and Investment Deals' with Gulf states. The episode is the first public test of whether the global shipping industry, working through the International Maritime Organization, has enough leverage to reshape a unilateral U.S. policy in real time. The read-through matters for Maersk, Hapag-Lloyd, ZIM Integrated Shipping, Diana Shipping, Frontline, and the broader tanker and dry-bulk complex.

IBM's 25% Crash Made the Enterprise Software Tape Stop Trusting Guidance
IBM closed down 25.21% at $217.07 on July 14, 2026 on 8.6x normal volume, its worst single-session decline on record. The drop did not come with an official earnings warning; what changed is that the market stopped trusting the multi-year software-and-consulting bridge that large-cap enterprise vendors have been selling since the AI capex story began. The contagion test is now in Accenture, Cognizant, Capgemini, Palo Alto Networks, CrowdStrike, ServiceNow, and Salesforce.
JPMorgan Quietly Made AI Job Cuts a Reported Number — And the Labor Market Can No Longer Ignore It
On July 14, 2026, JPMorgan disclosed that it has roughly 1,000 active AI use cases and that 'discrete areas' saw headcount reduced 30%-40%, with most affected employees redeployed rather than terminated. Headcount held at 320,560 employees, almost flat quarter-over-quarter, while net income jumped 41% year-over-year to $21.2 billion and adjusted EPS beat by 5% at $6.14. The tape ignored the EPS beat and focused on the labor story because a 30%-40% headcount cut inside the largest US bank is no longer an HR footnote — it is a labor-market datapoint the Fed cannot avoid.
June 2026 CPI at 3.5% YoY Is the Print That Just Reset the Social Security COLA Estimate - And the Fed Cut Path
The BLS June 2026 CPI report came in at 3.5% YoY, lower than expectations, driven primarily by a decline in energy prices, according to CNBC's reporting on July 14, 2026. The Senior Citizens League immediately trimmed its 2027 Social Security COLA estimate to 3.8% (unchanged from last month), while independent analyst Mary Johnson dropped her 2027 COLA estimate to 3.7% from 4.7% - a full percentage point cut in a single print. The disinflation reading is the first clean macro green-light of the cycle, and the rate-sensitive sectors (housing, regional banks, REITs, small caps) now have a real reason to lead.
Oracle's 63% Slide From Its 52-Week High Is the First AI-Infrastructure 'Fallen-Angel Watch' the Bond Market Has to Price
Oracle is down roughly 13% over the last 10 sessions and ~63% from its 52-week high of $345.72, with the 52-week low of $127.60 set on July 14, 2026. After the June 11, 2026 8% tumble on a $20 billion capital-raise disclosure and the June 23, 2026 disclosure that Oracle shed ~21,000 roles over the past year, the equity is now pricing the risk that AI-infrastructure capex commitments are pushing the balance sheet toward fallen-angel territory. With debt-to-equity at 322.86%, the question for the bond market is no longer whether Oracle can fund the AI build, but whether the cost of capital will move before the next earnings print on September 7.
June PPI's 0.3% Drop Gives the Fed Breathing Room, but It Does Not End the Inflation Trade
The U.S. Producer Price Index fell 0.3% in June, goods prices dropped 1.4%, services rose 0.2%, and year-over-year final-demand PPI still ran 5.5%. Markets immediately read the print as lower odds of further tightening, with the 2-year yield slipping and Fed pause odds rising, but the deeper message is that goods disinflation does not erase service inflation or energy volatility. The result still matters for BlackRock, JPMorgan, UnitedHealth, housing, utilities, and every rate-sensitive part of the market that lives off the next 25 basis points.
Alibaba and Apple Just Made Qwen the First Chinese AI Model Inside the iPhone Stack
Alibaba's U.S.-listed shares rose 4% in pre-market trading on July 16, 2026 after confirming its Qwen AI model will be integrated into Apple Intelligence across iOS, iPadOS, macOS, and visionOS for users in China. The Cyberspace Administration of China included Apple AI services on its approved-providers list alongside Huawei. The deal is the first time a Chinese AI model is inside the iPhone stack, and the read-through is direct for Apple, Alibaba, Huawei, Tencent, Baidu, and the entire cross-border AI-supply-chain complex.
Amazon Just Lost a 19-Year AWS S-Team Veteran Right When the AI Capex Cycle Is at Its Peak
Dave Brown, an Amazon Web Services SVP who helped assemble the original EC2 service in South Africa in the 2000s and oversaw AWS's compute and machine learning units including Bedrock and SageMaker, plans to leave the company at the end of July 2026 after nearly 19 years. He will be replaced by Dave Treadwell from the e-commerce division. Brown's exit from Jassy's 28-person S-team comes as AWS recorded 28% revenue growth in Q1 2026 and as Amazon raised at least $25B in a bond sale to fund its AI capex - the worst possible timing for a leadership transition.
Anthropic Is Now the Cleanest Test of Whether a $965B Private AI Can Survive Wall Street's Discipline
CNBC reported on July 15, 2026 that Anthropic is scheduling investor meetings with Goldman Sachs, Morgan Stanley, and JPMorgan Chase ahead of a potential IPO as soon as October, with a confidential SEC filing already in place. The company closed a $65B funding round at a $965B valuation in May, putting it above OpenAI's $852B private mark. The Anthropic listing would be the first mega-private-AI IPO test, and the read-through is direct for the entire cap-markets fee pool that the Street has been modeling higher - and for the AI multiple that the public tape has been paying for every other mega-cap.
The Bank of Korea's First Hike in Three Years Is the First Asian Central Bank to Admit the Won Crisis Is Over
The Bank of Korea hiked rates 25bp to 2.75% on July 16, 2026 - the first hike since January 2023 - against June CPI at a three-year high of 3.2% and a won that had touched a 17-year low of 1,561.5 on June 5. The move is the first Asian central-bank admission that the regional currency-defense regime is ending, and the read-through is direct for Samsung Electronics, SK Hynix, Hyundai Motor, Kia, POSCO, KB Financial, and Shinhan Financial. The won at 1,484.86 is still 5% weaker than the 1,400 cycle-supportive level, and the BoK is buying time before any further tightening.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.