Macro & Policy
Rates, inflation and the policy that moves them
Central bank decisions, jobs prints and fiscal policy, read the way a portfolio reads them: what reprices, by how much, and what would change the call.
2026-07-15

BNY Mellon Q2 2026 Beat - Raises 2026 Revenue Outlook Above Consensus - The Cleanest Single Read on the Financial-Infrastructure Cycle
BNY Corporation reported a Q2 2026 earnings beat and raised its full-year 2026 revenue-growth forecast above Wall Street expectations on July 15, 2026. The beat was driven by stronger activity across investment-services fees, asset-management fees, market-sensitive custody and administration revenue, and higher client assets supported by rising equity markets. The BNY beat is the cleanest single read on the financial-infrastructure cycle - the fee-based capital-markets plumbing that operates beneath asset managers, pension funds, ETFs, and institutional portfolios. The read-through is direct for BlackRock (BLK), State Street (STT), and the broader fee-based asset-management + custody + administration cohort that benefits from rising equity markets and higher institutional trading volumes.
Buffett Just Told CNBC He Personally Initiated Alphabet - And 'It's Tough to Find Values When Everybody Is Preferring Gambling'
CNBC reported on July 15, 2026 that Berkshire Hathaway Chairman Warren Buffett, in an interview with Becky Quick, said he personally initiated Berkshire's Alphabet position - not incoming CEO Greg Abel - and warned that 'it's tough to find values when everybody is preferring gambling.' Buffett's first public confirmation of his direct role in the Alphabet investment is the cleanest single signal yet that Berkshire is treating Alphabet as a long-term core holding, not a tactical trade. The read-through is direct for Alphabet, Microsoft, Apple, Meta, Amazon, Nvidia, the entire Big Tech cohort, and the value-vs-growth rotation thesis.
Europe Just Put $40B+ Into Drones and the Read-Through Is Helsing at $18B Not Lockheed Martin
CNBC reported on July 15, 2026 that NATO Secretary General Mark Rutte unveiled a 'drone-ready' alliance plan with $40B+ in counter-drone capability investments over five years, the U.K. committed £5B ($6.7B) to a 'UK drone transformation' program, Germany placed a 90M-euro order for 50,000 drones equipped with Auterion's operating system, and German defense-tech startup Helsing secured an $18B valuation. The drone sector is now receiving more institutional capital than the legacy defense primes, and the read-through is direct for Lockheed Martin, RTX, Northrop Grumman, General Dynamics, and every defense-tech startup trying to scale on the new European procurement.
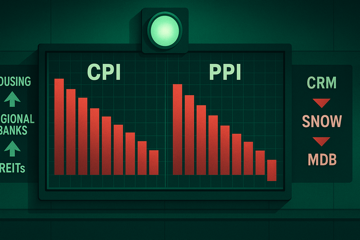
June 2026's -0.4% CPI and -0.3% PPI in the Same Week Are the First Real Disinflation Trade of the Cycle
The BLS June 2026 CPI fell 0.4% MoM (biggest drop since April 2020) and PPI fell 0.3% MoM (consensus was unchanged) on July 14-15, with goods prices dropping 1.4% (biggest since July 2022) on a 12% gasoline plunge. Core CPI slipped to 2.6% YoY and core PPI rose just 0.2%. The market read-through is direct: rate-sensitive sectors (housing, regional banks, REITs, small caps, dividend growth) now have a real green light, and the rate-cut pricing has collapsed from a near-certain hike to a 50-50 September bet. The cleanest expression is to be long the rate-sensitive rotation and short the high-multiple AI-application cohort that was the trade when the Fed was tightening.
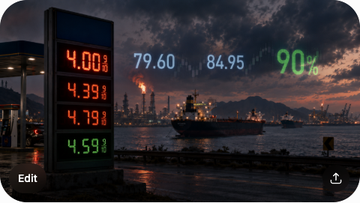
Kalshi Traders Now Put 90% Odds on Gas Crossing $4 This Month - And the Prediction Market Just Became the Cleanest Real-Time Tape on Hormuz Risk
CNBC reported on July 15, 2026 that prediction market Kalshi traders had priced a 90% probability that U.S. gas prices cross $4 per gallon by end of July - up from 56% just two days ago - with a 93% chance of crossing $4 and a 63% chance of exceeding $4.10, following the U.S. ending its Iran ceasefire and relaunching strikes. With WTI at $79.60 and Brent at $84.95, the prediction market is now the cleanest real-time tape on Hormuz risk - faster than futures, faster than retail gas data, faster than analyst notes. The read-through is direct for ExxonMobil, Chevron, ConocoPhillips, Valero, Marathon Petroleum, Phillips 66, United Airlines, Delta Air Lines, American Airlines, and the entire energy + transport complex.
Liquid Cooling Deep Dive: How Vertiv, Boyd, Rittal, CoolIT Systems, and Asetek Built the Most Concentrated AI Data Center Thermal Stack of the Cycle
Liquid cooling is the binding AI data center thermal stack of the cycle - air cooling is no longer sufficient for AI accelerators >700W TDP, and the 2026-2028 liquid cooling demand is the cleanest single read on the AI capex cycle's thermal leg. Vertiv leads with ~30% liquid cooling share, Boyd at ~10%, Rittal at ~10%, CoolIT Systems (the cleanest pure-play, recently acquired by Eaton) at ~8%, and Asetek at ~5%. This is a full-stack deep-dive into liquid cooling: cold plate (DLC) vs immersion (single-phase + two-phase) vs rear-door heat exchanger (RDHx), the coolant chemistry (PG-25, dielectric fluids), the customer base (Microsoft, Alphabet, Amazon, Meta), the top experts, the capex, the 2026-2028 supply-demand, and the read-through for the AI capex stack.
LNG Deep Dive: How Cheniere Energy, Shell, TotalEnergies, QatarEnergy, and Woodside Run the $400B Global LNG Trade - and Why the 2026-2030 Supply-Demand Is the Binding Read on the Energy Transition
LNG (Liquefied Natural Gas) is a $400B/year global trade that has become the binding flexible-supply leg of the global energy transition. The 5 largest LNG suppliers are QatarEnergy (~25% global LNG export share), Cheniere Energy (~15%, the largest US LNG exporter), Shell (~10%, the largest IOC LNG portfolio), TotalEnergies (~8%), and Woodside (~5%, the largest Australian LNG exporter). This is a full-stack deep-dive into LNG: liquefaction technology (ConocoPhillips Optimized Cascade, Air Products AP-C3MR, Black & Black & Veatch PRICO), the FLNG revolution (Shell Prelude + Petronas PFLNG), the customer base (China, Japan, Korea, Europe), the top experts, the capex ($80-100B/year industry), the 2026-2030 supply-demand, and the read-through for the energy transition.
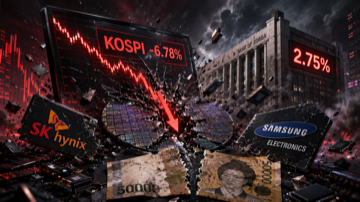
SK Hynix's 10% Single-Day Crash Made Korea the First Asia Tape to Reprice the Micron Memory Sell-Off
SK Hynix shares plunged over 9% in Seoul on July 16, 2026, reversing the prior session's 8% rally, as the Micron -8% sell-off in the U.S. overnight spilled into Asia. The Kospi dropped 6.78% to 6,790.23, with Samsung Electronics -7%, Seoul Semiconductor -5%, and Tokyo Electron -5%. The Bank of Korea simultaneously hiked rates 25bp to 2.75% - the first hike since January 2023 - against a backdrop of June CPI at a three-year high of 3.2% and a won near 1,484. The combined tape is the cleanest stress test of the AI-memory trade outside the U.S. since the 2024 cycle peak.
SpaceX Just Closed Below Its $135 IPO Price for the First Time - And the Private-to-Public Trade Is Now the Binding Test for Every Late-Stage Name in the Pipeline
CNBC reported on July 15, 2026 that SpaceX closed at $135.27 on its fourth consecutive losing session - the first close below the record $86B June 2026 IPO price of $135 - days after the Nasdaq-100 inclusion brought passive buyers in and ahead of the 13th Starship test flight on Thursday July 16. The break-under is the cleanest single read on whether the late-2025 / early-2026 private-mark pricing holds when $400B+ of cumulative private-tech paper tries to clear the public market. The read-through is direct for Anthropic, OpenAI, Stripe, Shein, Databricks, Canva, and the entire late-stage private cohort now queuing for 2026-2028 IPO windows.
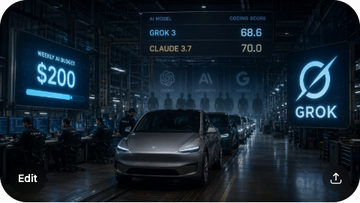
Tesla Just Capped Engineers' AI Spending at $200/Week - And Then Musk Mandated They Use His Own Grok Model That Ranks 9th
Electrek reported on July 10, 2026 that Tesla implemented a $200 weekly cap on third-party AI spending - notably exempting xAI's Grok - and Elon Musk then sent a memo instructing Tesla employees to switch to Grok, the AI model from his xAI company (now merged into SpaceX). Grok 4.5 ranks 9th on multi-domain leaderboards with a coding score of 68.6 (the lowest among compared models), trailing OpenAI (GPT-5.6 Sol/5.5/5.6 Terra/5.4), Anthropic (Claude Fable 5, 4.8 Opus, 4.7 Opus), and Google (Gemini 3.1 Pro). Tesla engineers reportedly prefer Anthropic's Claude for daily development work. The read-through is direct for Tesla, Anthropic, OpenAI, Alphabet, Meta, and the entire enterprise AI cohort now navigating self-dealing concerns.

Trump vs Hochul's NY Data-Center Moratorium Is the First Real Test of Whether AI Capex Has a Political Ceiling
President Trump publicly slammed New York Governor Kathy Hochul's new executive order barring for up to a year the construction of data centers that use 50+ MW of power, the first state-level moratorium of its kind in the U.S. Trump wrote on Truth Social that New York 'has made a terrible decision' and urged the state to change policy 'IMMEDIATELY.' The moratorium is the first concrete political constraint on the AI capex stack from a U.S. state, and the read-through is direct for Microsoft, Alphabet, Amazon, Meta, Nvidia, Equinix, Digital Realty, and every AI-infrastructure issuer with a NY exposure.
Warsh Just Turned the Fed From a Single-Mandate Inflation Fighter Into a Multi-Task Force Monetary Experiment
CNBC reported on July 15, 2026 that Fed Chair Kevin Warsh used two days of congressional testimony to launch a multi-pronged review of how the Fed measures inflation, restore money-supply reporting, and convene an all-bullish AI task force - all while CPI and PPI both printed unexpected declines. Fed Governor Lisa Cook pointed to AI spending as a potential inflation driver and warned 'inflation risks now outweighing employment risks.' The Fed meets in two weeks and markets are split on whether rates rise, hold, or fall - and the read-through is direct for every rate-sensitive sector, every AI capex issuer, and the bond market that is now repricing the Fed governance premium.
2026-07-14
Hundreds of Economists Are Telling the Market What the AI Trade Does Not Want to Hear
AP reported on July 13 that hundreds of economists signed a joint letter calling for immediate action on AI's economic impact and job-displacement risks. The market is still pricing AI as a productivity story. The economists are forcing a parallel conversation about labor-market disruption, antitrust, and AI-specific regulation that can change the political risk premium on the entire AI trade.
Nvidia's Asia Buyer Crackdown Turns Export Compliance Into a Moat
Nvidia is halving its list of authorized Asian buyers and tightening checks across Singapore, Malaysia, and Japan. The immediate effect is less channel freedom, but the deeper read is that compliance is becoming part of Nvidia's pricing power and its geopolitical firewall.
Private Credit Is No Longer Quietly Carrying the Risk - It Is the Risk
Private credit is being stress-tested in public for the first time since the asset class scaled, with AP reporting that higher rates are squeezing borrowers and forcing the industry to defend NAV marks. The exposure matters far beyond Apollo, KKR, Blackstone, Blue Owl, and Ares; it now sits inside the loan books of regional banks, BDC ETFs, and the AI capex financing pipeline.
Valero, Marathon Petroleum, and Phillips 66 Are Trading the Product Shortage, Not Just the Oil Shock
Valero, Marathon Petroleum, and Phillips 66 simultaneously printed fresh 52-week highs on July 14 as crude and refined-product risk premia rose. The deeper signal is that investors are paying for conversion scarcity—the ability to turn crude into the right gasoline, diesel, and jet fuel in the right region—while political scrutiny and a potential demand response make the trade increasingly asymmetric.
Wall Street's Super Tuesday Puts the Big Banks in a Trading Test
Five of the largest U.S. banks are reporting on the same morning, and the market is not just checking earnings. It is checking whether trading, investment banking, and fee income can keep outrunning deposit competition, higher funding costs, and a noisy geopolitical backdrop.
Warsh's First Testimony Meets an Oil Shock and a 4.6% Treasury Yield
The market is heading into Kevin Warsh's first congressional testimony with oil prices higher, Treasury yields repricing, and traders already leaning hawkish. The question is no longer whether inflation is cooling in a straight line; it is whether the Fed's communication reset makes the market tolerate less forward guidance and more volatility.
Wells Fargo Reports Q2 2026 as the First Real Test of Whether It Can Climb Out of the Penalty Box
Wells Fargo enters its July 14, 2026 print having bounced off 52-week lows, with the market still treating the bank as a regulatory-recovery story rather than an earnings-growth story. The Q2 release has to prove that fee income, capital return, and an asset-cap conversation can move together, or the stock will keep trading like a fallen leader waiting for permission to fully re-rate.
Lucid Group's 16% Single-Day Crash on a Chapter 11 Rumor Is the First Real Stress Test of the Sovereign-Backed EV Model
Lucid Group closed down 16.15% at $4.62 on July 14, 2026 on volume of 152.27 million shares - more than 35x its 10-day average - after an EV-blog report claimed restructuring adviser AlixPartners was weighing Chapter 11 or a take-private path for the Saudi-backed automaker. Lucid's IR lead Nick Twork called the report 'completely false' and pointed to the $800 million loan draw from a Saudi affiliate on July 6 as proof of liquidity into 2027. The crash is the first public stress test of whether the sovereign-backed EV model can survive a liquidity scare, and the read-through matters for every loss-making EV OEM still burning cash.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.