Macro & Policy
Rates, inflation and the policy that moves them
Central bank decisions, jobs prints and fiscal policy, read the way a portfolio reads them: what reprices, by how much, and what would change the call.
2026-09-04

NBIM’s proposed cut to U.S. Treasuries turns “ally demand” into a term-premium risk
Norges Bank Investment Management (NBIM) has proposed reducing the government-bond weighting inside its benchmark and cutting its U.S. Treasury exposure materially. Even if the move is gradual, it reframes official-sector demand for duration as a portfolio-design variable—one that can pressure term premium, auction dynamics, and the dollar when U.S. supply rises.
Trump ties tariff retaliation to the Fed: a September risk where rate cuts become the “payment” the White House demands
A reported White House threat—cut rates or the U.S. will stop trading with certain deficit countries—fuses trade retaliation with Fed independence into one coercion channel. If markets treat it as credible, the Sept. 17 FOMC decision shifts from a pure monetary debate to a compound tariff-and-stagflation shock that can keep duration yields and the dollar pressured while growth expectations roll over.
A $600M Turkish bank just got SDN-listed — that's a bull signal for JPM, Citi and BofA, not a crude headline
OFAC on September 4, 2026 put Golden Global Bank, Turkey's 35th-largest lender, on the SDN list under E.O. 13902 for laundering tens of millions for the IRGC-Qods Force. The small target is the point: by SDN-listing a niche correspondent-banking node, Treasury forces every larger Turkish and EM bank — and every US money-center that clears their dollars — to police Iran's residual reach or risk losing US account access. The trade is the correspondent gatekeepers (JPMorgan Chase, Citigroup, Bank of America) and short Turkish lira funding, not crude oil.
Warsh’s “quieter Fed” makes the NFP print a protocol change—not a rate forecast. Here’s what survives
Kevin Warsh’s push to reduce forward guidance and rely on a more explicit reaction function shifts what traders do on jobs-report day. With the market already leaning toward a September hike, today’s NFP becomes the first test of the new playbook—rewarding cross-asset “surprise” interpretation and punishing any strategy built on prior-message pre-positioning.
2026-09-03
2026-09-02
Automatic Data Processing (ADP)'s 38K print contradicts steady JOLTS—this is the signal that decides whether September is really a “two-hike” month
ADP’s Private Sector Employment rose only 38,000 in August—an unmistakably weak labor-demand datapoint—while BLS JOLTS for July showed job openings and hiring staying roughly flat. The gap matters because it changes the likelihood that Friday’s BLS payrolls will confirm further tightening; markets can keep “calm” longer than the data, but only until the payrolls number forces the next repricing.
Sep. 2 broke the “resilience” script: 10-year yields hit 2026’s top zone while earnings-season support ended and oil surged
On Sep. 2, the US reignited direct hostilities with Iran as the 10-year Treasury yield pushed to its highest level since Nov. 2023, while crude prices firmed after the conflict flare-up. With the Q2 earnings window effectively done and buyback blackouts typically starting, investors lose two key sources of dip-buying support just as the market’s discount-rate sensitivity returns.
July JOLTS just steadied the labor-demand backdrop—but it doesn’t fully rescue the two-hike path into September payrolls
BLS’s July JOLTS kept the labor market’s “hiring engine” roughly intact: job openings and hires held near June levels, while quits stayed around a steady 1.9% rate. That mix supports “some cooling without a collapse,” which can slow the hawkish repricing—yet it also gives policymakers less reason to expect an abrupt demand unwind ahead of Friday’s payrolls.
2026-09-01
August ISM Manufacturing has one job: prove whether price-growth is slowing enough to dodge the next hike
The Fed’s September decision will hinge on whether the August ISM Manufacturing print keeps the “prices-paid” impulse consistent with cooling inflation—or re-ignites a hike-risk tape. July’s ISM already showed decelerating price pressures (Prices Index falling to 71.1), so the market is likely to focus less on the headline PMI and more on how broad the “higher prices” diffusion stays.
Senegal’s IMF-led debt rework and Uruguay’s de-dollarization sprint expose which frontier sovereigns break first at ~4.8% U.S. 10-year yields
Senegal’s decision to rework debt as part of a renewed IMF program creates the first visible template for how frontier-EM sovereigns adapt when funding conditions tighten. Uruguay’s accelerated move away from dollar reliance functions as a defensive hedge that targets the same vulnerability—dollar-denominated liquidity and funding stress—before the market forces it.
Eurozone inflation at 3.3% forces a real test for the ECB hawkish repricing—here’s why US duration is likely to reprice faster than USD cuts
Eurostat’s August flash HICP jumped to 3.3% (from 2.9% in July), with energy still accelerating—data that arrives just before the ECB’s Sept. 9–10 Governing Council. If the ECB leans hawkish, US rate expectations and duration risk can reprice through the transatlantic “relative rates” channel—favoring higher yields and tighter financing conditions before the Fed can fully price cuts.
When September goes from “maybe” to “base case,” the first losses show up in duration, not in jobs
FedWatch-style probability pricing has moved the September hike debate from two-way uncertainty to a high-confidence base case—changing how investors discount every subsequent data point. The cross-asset hit pattern is straightforward: long-duration equity multiples compress first, dollar-funded carry tightens second, and only later do housing and credit spread stress become the dominant story.
India’s 7.8% exports-led GDP beat arrives right on the “crowding” test for EM carry
India’s Q1 FY2027 growth printed at 7.8%, with exports and gross fixed capital formation both double-digit in real terms—an unusually clean macro impulse for risk assets. The investor question is timing: when the US long end tightens and EM carry funding costs rise, will India’s growth narrative pull in steadier demand, or will it become the trade’s next crowding casualty?
The carry trade gets squeezed twice: Japan’s 30-year JGB yield at 4.19% collides with joint yen intervention funded via Fed backstop
Japan’s long-end borrowing cost is now pressing at fresh highs, with the 30-year JGB yield at 4.19% on Sep 1, 2026. At the same time, the U.S. and Japan moved to buy yen (July 31) and Bessent urged that the Fed’s FIMA backstop be upsized, tightening the funding leg of global yen carry from both duration and FX angles.
Oil back above $90 and September hike odds repriced—so why are stocks acting like fear is over?
When crude rips higher but equities barely flinch, it usually means the market is pricing “no recession” rather than “no inflation.” The real test is the jobs/ISM data and Broadcom guidance: if the labor/earnings binary breaks, the same calm that looks like “peak fear” can quickly turn into the next risk premium repricing.
Bessent’s Treasury buybacks aim to stop the bond market from turning into credit damage
On Aug. 19, 2026, the U.S. Treasury expanded its longer-dated nominal buybacks—raising the per-operation maximum to at least $4 billion effective Sept. 9, 2026—explicitly to add liquidity during a rates selloff. The investable takeaway is that when the Treasury curve starts behaving disorderly, the first transmission is not always “rates,” but funding stress that widens credit spreads and reprices duration across IG issuance and equity valuations—well before any clear policy win shows up.
2026-08-31
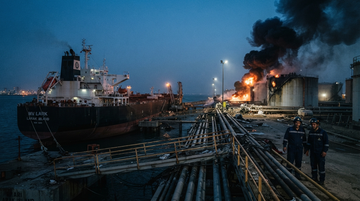
Oil back above $90 after a fresh strike on Iran—yet stocks barely blink: the market is pricing “duration,” not direction
A U.S. strike on Iran’s Larak Island helped lift Brent crude back above $90, but equity risk gauges stayed subdued and traders leaned toward a September hike odds shifting rather than a full-blown recession shock. The key difference is that the market appears to be treating the latest escalation as a near-term supply “headline” while assuming the Fed’s path (and risk appetite) won’t reprice materially unless disruption looks prolonged.
France’s near-2008 OAT stress is testing the eurozone duration channel—and the US rate pass-through is the risk investors can quantify
France’s borrowing pressure in OATs—driven by auction/term-structure supply mechanics—has moved closer to crisis-era yield territory, and that matters because eurozone duration repricing can spill into global rates. The spill-through is not “headline contagion”; it is the market repricing of long-dated funding and collateral, which can steepen US curves into late-year Fed decisions—while hurting European banks and supporting institutions with trading/hedging capacity.
Shelter re-accelerated: the rent CPI input that can turn September from a jobs story into an inflation test
A fresh shelter/rent read can re-ignite the “sticky disinflation” debate because rents flow into CPI with a built-in lag. When that lag turns back upward, the market’s September-rate path that was leaning on labor-only evidence gets stress-tested by a second inflation channel.
2026-08-30
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.