Macro & Policy
Rates, inflation and the policy that moves them
Central bank decisions, jobs prints and fiscal policy, read the way a portfolio reads them: what reprices, by how much, and what would change the call.
2026-08-25

2026-08-24
Japan’s long-end auction jitters are tightening the “foreign supply” screw on U.S. Treasuries
A weak pocket in Japan’s long-end bond supply is showing up as a funding-demand headline at the same time the U.S. Treasury is trying to cushion the long-end with larger buybacks. The key question for investors: whether Bessent’s 10- to 30-year containment can offset JGB spillover into global duration risk—without relying on a market that keeps repricing term premium upward.
Mexico’s “14% Q2” GDP surge is real—but the story is tariff-bloc math, not pure nearshoring momentum
Mexico’s Q2 output rebound is strong enough to validate parts of the nearshoring thesis for North American supply chains, but the magnitude is likely inflated by how tariff blocs (and trade-policy uncertainty) re-route demand. Investors should treat the headline as a signal of re-pricing and production reallocation first, and as a durable growth engine only if USMCA certainty improves.
UBS’s 8,100 S&P 500 target only stays “tape-consistent” if buyback math and long-end yields don’t break
UBS lifted its S&P 500 year-end target to 8,100 alongside higher 2026/2027 EPS forecasts. That bullish tape depends on two fragile links: duration-sensitive discount rates staying stable and buyback credibility keeping equity duration bid. The near-term risk is a regime where higher long-end yields and fading buyback impulse force EPS estimates to do the heavy lifting.
2026-08-23
Aug. 22’s semi-led selloff sets up Nvidia’s Aug. 26 call: the tape is repricing “duration,” while Canada tariff retaliation tightens risk appetite
Aug. 22 was not just another chip wobble: the Nasdaq’s weekly slide aligned with a macro mix of higher bond-yield sensitivity and escalating cross-border trade risk from Canada’s planned “dollar-for-dollar” tariffs. With Nvidia scheduled to report fiscal Q2 results on Aug. 26, the near-term question for investors is whether guidance can overpower duration-driven multiple compression—and how semiconductor buyers plan budgets under a more punitive policy backdrop.
EM carry’s longest run since 2008 flags crowding—and a US long-end shock is the unwind switch
Emerging-markets carry has been extending a winning streak that is now at its longest since 2008, with US-dollar funding still pricing the “risk” cheaply. The same week, Treasury and Fed leadership dynamics are pushing back on long-end yield guidance—raising the odds that a long-end repricing triggers a fast unwind rather than a slow re-rate.
2026-08-22
Dalio’s “sell bonds, buy gold + bitcoin” trade is colliding with official-sector gold demand and a long-end liquidity push
Ray Dalio’s latest debt-crisis-style reallocation—underweight bonds, add gold (10%–15%) and a “bit” of bitcoin—lands amid record-high gold pricing and a U.S. Treasury plan to enlarge long-end buyback operations. For investors, the key question isn’t whether gold and bitcoin are “hedges,” but whether the hedge mechanics hold when real yields, the dollar, and official-sector bullion buying move together.
Bessent’s “long-end target” signal matters only if it survives Trump’s credibility test
On Aug. 21, Treasury Secretary Scott Bessent used a public Monday presser to tee up explicit steps aimed at pushing down long-dated yields—via an upsized long-end buyback framework. But Trump’s denial that he directed any bond-market intervention becomes the key credibility test: markets will trade the yield-control “regime” only if it’s repeatable, not one-off messaging.
2026-08-21
ECB’s hike repricing to ~3% by late-2027 could “break” the USD-funded AI carry trade—starting with US duration and dollar funding costs
Traders are repricing the ECB deposit rate toward 3% by late-2027 while the Fed eases, widening the global rates split that typically supports USD-funded risk-taking. For US-linked AI capex, the key transmission is not just FX; it is the feedback loop into USD funding costs and the valuation of long-duration cash flows.
Jackson Hole’s missing link: one Fed speech now has to reconcile $94 oil, a 4.69% 10-year, and a retail-slowdown signal for September
Ahead of the Jackson Hole Economic Policy Symposium (Aug. 27–29, 2026) and amid a sharp weekly equity drawdown, markets are trying to map one Fed narrative onto three conflicting price signals: oil holding near $94, the 10-year around 4.69%, and U.S. retail sales falling 0.6% in July. The paper-for-paper risk for policy makers is that the oil shock can keep inflation expectations anchored while still lifting longer-end rates, so “cuts later” can be incompatible with a weakening consumer.
US services flashed back to acceleration—turning the September Fed-cut bet into a growth-versus-inflation tug-of-war
S&P Global’s August flash PMI shows US services business activity re-accelerating to a 20-month high, while manufacturing stays in “soft” territory. That mix matters for Fed timing: it supports growth momentum, but it also raises the odds that services inflation stays sticky enough to delay rate-cut confidence even if the headline inflation trend continues to cool.
2026-08-20
Brent clearing $94 snaps the “oil fade” setup—and makes September rate math run through the P&L, not the dot plot
Brent pushed above $94 on Aug. 20, ending a multi-session run that had kept traders leaning on the idea of an $85 “fade.” The oil regime break matters for Fed odds because it quickly tightens near-term inflation and risk-premium assumptions, while also feeding directly into fuel-sensitive earnings.
China’s Bond Market Is Refusing to Diversify—Until It Might Suddenly Do the Job for Global Investors
When global yields rise on inflation and fiscal pressure, China’s bond market has been moving in the opposite direction, widening the China–U.S. 10-year yield gap again. That divergence matters because it determines whether foreign allocators keep treating long-duration U.S. Treasuries as the default “safety” trade—or start paying for China duration as the actual diversifier.

Citi’s dollar call is really an equity-flow warning: buyback policy can switch off USD demand
Citi’s Aug. 20 structural downgrade to the dollar ties the next leg of FX risk to a policy-controlled US buyback channel rather than a pure Fed timing story. If Washington tightens or constrains corporate buybacks, the biggest immediate transmission line runs through US equities—changing how global investors fund USD exposure and hedging demand.
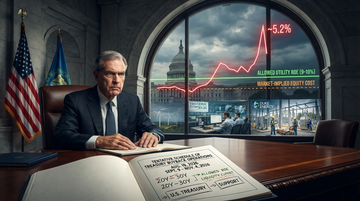
Regulated utilities at ~5.2% 30-year: why “allowed ROEs” don’t protect equity investors when the cost of capital moves faster
On Aug. 19, 2026, the U.S. Treasury increased the size of long-end liquidity-support buybacks to rein in the 20–30 year funding window, after the 30-year yield pushed higher. Even with that intervention, a ~5.2% 30-year reference rate implies a duration-sensitive equity math problem for regulated utilities: allowed returns (often ~9–10%) sit well below market-implied equity costs that rise when long yields stay elevated, forcing rate-case timing, issuance, or dividend trade-offs.
2026-08-19
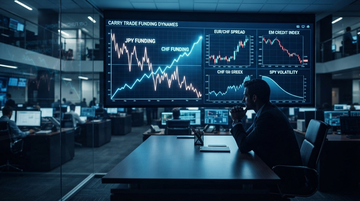
CHF Funding Quietly Replaces JPY in Carry—And That’s a Direct EUR/CHF + EM Credit Shock Channel
After yen volatility spiked, investors have been rotating carry funding away from the yen and toward the Swiss franc, citing the euro and CHF as alternative “funders of choice.” That shift matters because a CHF rally can force leveraged EUR/CHF and CHF-funded emerging-market carry positions to de-risk at the same time, turning FX funding stress into immediate risk-asset drawdowns and margin pressure for Swiss exporters.
Lagarde’s “order” warning reframes EURUSD: the risk isn’t just currency—it’s Europe’s supply-chain competitiveness lagging the US
ECB President Christine Lagarde says the weakening of a rules-based global order—specifically tied to America’s pullback from Western security leadership—is eroding the conditions behind Europe’s post-war growth model. The bigger market risk may be the second-order transmission: slower European investment and scaling under geoeconomic fragmentation, which can pressure both competitiveness and the euro’s role in trade, not merely EURUSD spot levels.
Fed minutes lean hawkish while the Treasury scales buybacks—September becomes a tug-of-war between inflation control and fiscal support
The latest FOMC minutes underscore a conditional path to rate firming if inflation stays elevated, with policymakers explicitly linking “some policy firming” to inflation scenarios. At the same time, the Treasury announced a doubled scale for certain debt buyback operations, supporting market liquidity and pushing yields lower—so September is set to be decided by which transmission mechanism dominates first.
Treasury’s doubled debt buybacks look like quasi-QE—but the mechanism is closer to plumbing support than term-premium math
The U.S. Treasury’s Aug 18–19 decision to double its debt buyback program is a direct liquidity backstop for specific off-the-run Treasury issues, not a broad-based asset purchase like 2020’s QE. For rates investors, the key question is whether tighter bid/offer spreads and fewer dealer balance-sheet constraints can suppress term-premium moves—or merely redistribute trading flows across the auction calendar while yields reprice.
Crossing $40T Turns Treasury Buybacks Into an Accounting Puzzle at ~4.65% 10-Year Yields
When U.S. debt tops $40 trillion while the 10-year sits near 4.65%, interest-cost arithmetic starts working against any “stabilize liquidity” debt buyback plan. The key contradiction isn’t that buybacks are useless—it’s that at today’s term yields, even modest net issuance can compound into a much faster rise in annual net interest, forcing a larger share of future fiscal space to be auctioned back to investors.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.