Policy & Trade
Tariffs, export controls, and who absorbs them
Rulings, sanctions and trade negotiations traced to the companies that pay for them — margin by margin, route by route.
2026-08-05

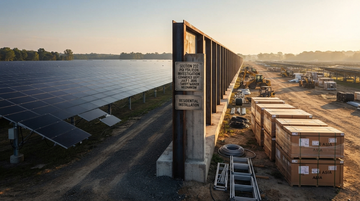
Polysilicon tariffs aren’t a module story—they’re a waiver-and-margin story that decides whether IRA solar builds keep running
The US Commerce Department’s polysilicon Section 232 process is upstream policy leverage, and it can still ripple to module prices even before any “15% tariff” becomes official. The investor impact is a bifurcation: First Solar is structurally insulated because it sells cadmium-telluride modules that don’t rely on polysilicon waifers, while Enphase and residential installers face demand risk if tariffs raise installed system costs faster than incentives can offset.
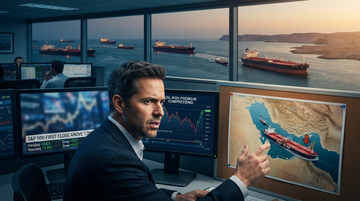
S&P 500’s first 7,700 close rewards cyclicals, not AI—because Hormuz de-escalation reprices the “oil risk premium”
The Aug. 4 move looks like a pure tech-led rally, but the Dow’s +907 point surge vs the Nasdaq’s +2.6% pop signals investors are rotating into cyclicals that benefit directly when Hormuz-risk compresses oil and shipping insurance. With oil trading below ~$80 amid de-escalation chatter, the first 7,700 print becomes a sector composition signal—not just a momentum milestone.
A “quiet” U.S. import ban on Chinese AI data-center components turns optical interconnect into the next choke point
A Reuters report says the FCC is drafting a U.S. ban on imports of new Chinese data-center components—specifically Chinese optical transceivers—targeting the fiber links that move AI traffic inside server parks. That shifts the AI-hardware investment question from compute chips to networking optics, and it changes which listed suppliers can actually capture replacement-system spend as the policy timetable moves through “draft → publish → effective.”
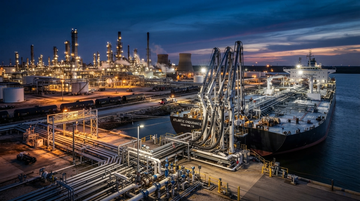
US distillate exports hitting record levels are turning the refining margin trade into an Atlantic-basin diesel shortage bet
The EIA shows U.S. distillate exports surged to a weekly record of 1,861 thousand barrels/day (week ending May 1, 2026), and those barrels are finding their way into a tight Atlantic-basin middle-distillate market. When diesel cracks stay historically high while inventories stay constrained, the refiner story becomes less about oil supply and more about conversion capacity plus logistics—an edge held by refiners like Valero, Marathon Petroleum, and Phillips 66 that can consistently monetize distillate exports.
2026-08-04
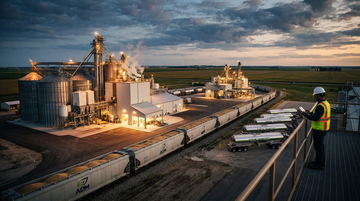
ADM’s Raised 2026 Biofuels-Driven Outlook Suggests a Margin Cycle That May Be More Policy-Structured Than Cyclical
ADM lifted its 2026 adjusted EPS outlook to $4.15–$4.70, explicitly tying the upgrade to “constructive” post–U.S. biofuel policy clarity and expected earnings improvement across its crushing and ethanol businesses. The key shift isn’t just higher margins—it’s that renewed regulatory demand visibility is changing how feedstock economics flow through crushers, refiners/ethanol plants, and ultimately to farmers.
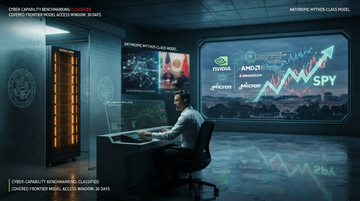
AI diplomacy is repricing US chips: China’s Mythos anxiety turns the next frontier-model release into a Trump–Xi bargaining input
U.S. policy is building a voluntary, federally benchmarked “covered frontier model” review process for advanced AI with cyber risk, ahead of a Trump–Xi summit sequence. If China is truly focusing on Anthropic’s Mythos-class cyber capabilities as an “offensive weapon” concern, then the next frontier-model decision window is effectively being priced into the same trade corridor that governs advanced AI chip access—making NVIDIA, Broadcom, AMD, and Micron sensitive to diplomacy headlines.
TikTok’s three pre-trial teen settlements just pushed Meta/Snap/Alphabet into the “Section 230 reserve mark-up” era
TikTok agreed to settle a landmark teen social-media addiction case just before the trial began, after Snap also settled and while Meta and YouTube (Alphabet) faced the bellwether. The result is less about payout size and more about litigation pricing: once one “architected-for-addiction” case resolves early, it increases the probability-weighted loss exposure and forces platforms to carry higher legal reserves—re-anchoring the ad-market’s Section 230 liability discount.
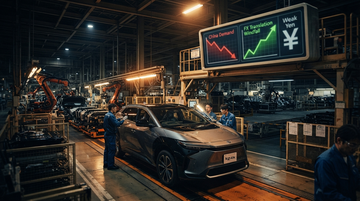
Toyota’s weak-yen “profit” story is increasingly a China-write-off + FX-translation trade, not a demand rebound
Toyota is guiding higher operating profit even as it warns China weakness is persisting, turning the weak-yen tailwind into an accounting translation effect rather than a volume recovery. For investors, that means the next catalyst is less about Japanese pricing power and more about whether FX tailwinds survive and whether China demand stabilizes.
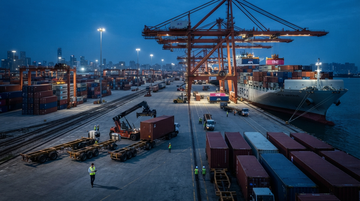
America’s trade deficit shrank because imports fell—watch the supply-chain “pause” behind the headline
In June, the U.S. goods trade deficit narrowed to $101.5B largely because imports of goods fell $8.2B m/m. That looks GDP-friendly on the surface, but it can also signal a demand pause and inventory/freight timing effects—typically showing up first in logistics and in companies with high import exposure.
A Trump-family miner’s Q2 loss says the post-halving margin floor isn’t “policy-proof”
The listed, Trump-family-linked miner American Bitcoin Corp reported a Q2 net loss even while its Bitcoin holdings grew, underscoring that political narrative cannot replace the hard post-halving economics of mining. The result reframes the entire US-listed miner cohort: when hash-revenue and cost/opex structure don’t clear the “all-in” hurdle, Strategy Inc can amplify the upside—while still leaving the downstream balance-sheet reality unchanged.
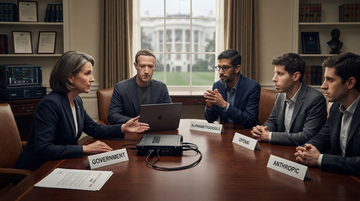
A White House “voluntary” AI safety test became a pre-regulatory negotiation—frontier labs now face a binary choice on access vs. disclosure
A Reuters report says the Trump White House invited Meta, Anthropic, Google, and OpenAI to a sit-down on voluntary government AI safety testing. Combined with the June 2, 2026 executive order’s up-to-30-day access framework, the meeting signals a shift from “standards talk” to controlled, government-mediated model access that can re-price who can move fastest without being forced to reveal too much.
2026-08-03
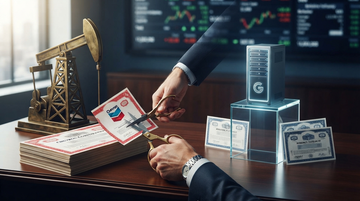
Berkshire’s Abel week is a value-rotation tell: cutting Chevron yet elevating Alphabet into a “virtual monopoly” position
In Greg Abel’s first-week-era moves, Berkshire reduced Chevron exposure while pushing Alphabet into a new top-5 “virtual monopoly” role—using concentration to express a new conviction stack rather than pure cash-and-yield defensiveness. For active managers, the investable takeaway is that Berkshire’s re-rating map is shifting from “dividend insulation” toward “moat + compounding” inside the public-equity sleeve, even when it means exiting parts of the energy/cash yield complex.
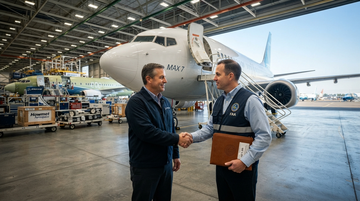
Boeing's 737 MAX 7 gets FAA type-certificate clearance—so airline delivery conversion can finally stop being a “regulatory option” and start being cashflow
The FAA issued an amended type certificate and updated the Production Limitation Record for the Boeing 737 MAX-7 on Aug 3, 2026—clearing the last big certification overhang that kept 737 MAX 7 deliveries from being a straightforward sales-and-delivery story for carriers. For investors, the key shift is that the remaining uncertainty moves from “will it be certified?” to “how fast will Boeing and the supply chain convert order book into aircraft + acceptance slots,” which should reprice near-term delivery timing risk for Alaska Air Group and Southwest Airlines and flow through to suppliers like Howmet Aerospace.
Brussels Raises the Cost of AI Distribution—But Big Tech Can Absorb What Frontier Labs Cannot
The EU AI Act’s transparency rules began applying on 2 August 2026, forcing providers and deployers to disclose AI interaction and label synthetic content. The immediate burden is operational rather than a guaranteed 7% revenue hit: Article 50-related violations fall under a ceiling of €15 million or 3% of worldwide turnover, while the larger 7% ceiling applies to prohibited practices. That asymmetry favors diversified platforms such as Microsoft, Alphabet, and Amazon over private frontier labs whose Europe-specific revenue is not disclosed.
Marriott.'s Middle East RevPAR hit confirms Iran-war hotel damage—now guidance risk spreads across the hotel value chain
In its Q2 report, Marriott showed Middle East & Africa RevPAR fell sharply and said the conflict impact is continuing into the third quarter—turning the Iran/Hormuz shock into a measurable earnings drag, not just a narrative risk. The key investor takeaway is that RevPAR declines in a specific geopolitical corridor can quickly propagate from corporate travel cuts to regional profitability, then to group/OTA booking behavior—making “Middle East exposure” a portfolio-level question for hotel operators and online travel channels.
US regulators aren’t just policing fair lending—they’re forcing banks to prove where “community development” grant money actually goes
The OCC/FDIC proposal ties CRA-adjacent fair-lending scrutiny to a concrete “credit-allocation” proof: banks must demonstrate that most community development grant funds are spent in the relevant communities—and that grant recipients don’t run high overhead. The economic effect is simple: this rule shifts cost and compliance burden toward relationship banks that rely on mission spending, compressing the returns on “CRA-style” balance-sheet and programmatic allocations.
Palantir’s guide raise is the market’s first “AI budgets are real” signal—because it’s coming through the U.S. commercial line
Palantir’s latest guidance raise is most investable when you treat it as evidence that AI deployments are moving from one-off pilots into contracts that show up in forward revenue. The clearest through-line is the uplift in Palantir’s U.S. commercial revenue guide, which makes the AI/defense thesis a budget-and-execution story—not just a demo-market story for software vendors.
Tom Lee’s 2027 “best year” only works if mega-caps keep leading while SpaceX-or-Fed shocks don’t reprice risk—here’s the trade book
Tom Lee’s bullish 2027 setup is best understood as a conditions trade: mega-caps must keep capturing AI earnings momentum while the market digests massive tech IPO supply and avoids a Fed-led tail unwind. The concrete test is whether leadership stays narrow (NVDA/META/GOOGL/AXP/CVX) or spreads into the small-cap bridge—because if it doesn’t, “best year” becomes a liquidity/valuation story rather than an earnings story.
Trump turns supermajor capital return into a “gasoline-price” hostage—Exxon and Chevron can’t buyback their way out
On Aug 3, 2026, Trump told ExxonMobil and Chevron to “stop making too much money” and to “cut the retail price, the consumer price,” explicitly tying Big Oil’s high profits to gasoline affordability. The core investor risk is not that buybacks stop tomorrow; it’s that politicized price pressure forces Integrated majors to re-optimize cash allocation between returns, capex, and supply—raising second-order risk to Permian/Midcontinent-capex and refining feedstock plans.
2026-08-02
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.