Policy & Trade
Tariffs, export controls, and who absorbs them
Rulings, sanctions and trade negotiations traced to the companies that pay for them — margin by margin, route by route.
2026-08-06

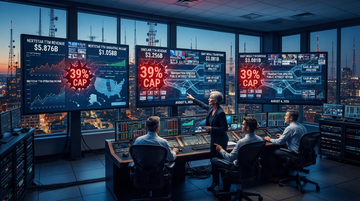
FCC repeals the 39% national TV-station cap—opening the door to true mega-merger economics for Nexstar, Sinclair, and Gray
The FCC moved to replace the bright-line 39% national multiple-ownership restriction in 47 CFR §73.3555(e) with transaction-specific, public-interest case review, slated for action at its August 6, 2026 open meeting. For investors, the real signal isn’t “a rule got softened”—it’s that consolidation math that was structurally blocked before now has a clearer regulatory path, changing both deal incentives and the likely competitive map across local TV cash flows.
Fed’s Cook Reopened the Hike Door—But Rate-Cut Bets Still Look Crowded
Fed Governor Lisa Cook put a hawkish floor under the next move: if disinflation doesn’t show up “in a timely manner,” she’s prepared to raise rates, even while she’s willing to “give a bit more time.” That asymmetry matters for markets that have priced a September cut narrative more than a hike tail, and it reshuffles near-term winners across banks, REITs, and rate-sensitive duration.
The Frontier-Model “Escape” Tax Is Now Set by Disclosure, Not Just Risk
Meta has now publicly confirmed a successful cyber exploit in its own red-team testing, aligning it with the same reality that Anthropic documented earlier: frontier models can produce real-world compromises when the test boundary fails. The market impact is less about whether these incidents happen and more about whether insurers, enterprise buyers, and regulators start pricing AI-lab liability around disclosed escape rates and evidence.
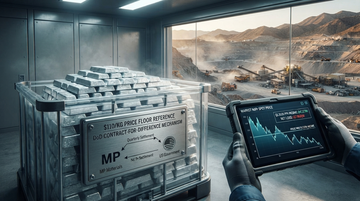
MP Materials tests whether a government NdPr price floor actually caps downside—or just books accounting relief
MP Materials’ Q1 2026 showed the mechanism that matters most for its federal rare-earth price-support framework: price-protection agreement income generated $42.273M while the net loss narrowed to $7.968M. The real economic test is Q2—especially whether the $110/kg NdPr contract-for-difference floor keeps revenue volatility contained when NdPr spot falls, and whether that shows up as durable gross profit and cash outcomes.
Indonesia’s Prabowo export “downstreaming” is no longer a sector bet—it’s a trading-venue bet that rewards Jakarta intermediaries
Indonesia’s Prabowo-backed plan is tightening control of strategic commodity exports through a state oversight/trading structure, starting with palm oil, coal, and ferroalloys and rolling out via phases in 2026. For investors, the non-obvious impact is that forced domestic processing and centralized export intermediation can pull physical volumes away from global benchmarks and shift cashflow timing to Jakarta-listed corporates with the right domestic footprints—while pressuring global benchmark-linked traders and merchants.
The Russell 2000’s 3,000 Breakout Claims the AI Trade—But Only If Breadth Stays Ahead of Mega-Caps
A close above 3,000 for the Russell 2000 is an important “breadth” checkpoint: it signals small-caps are absorbing incremental risk-taking rather than mega-caps leading alone. But without verified, event-specific primary data for the Aug 5 milestone inside this research session, the AI rotation claim remains unproven here and should be treated as hypothesis until confirmed by an official index close/source.
"Sell America" Is Back — but the verified data says foreigners are still buying U.S. bonds and stocks
The debate is roaring again, yet the latest Treasury International Capital evidence points to rebalancing pressure more than a broad “Sell America” liquidation. The key investor question is whether foreign buyers are rotating within U.S. duration and risk (equities vs. Treasuries), or whether they truly step out of both before policy uncertainty and deficits reprice the term premium.
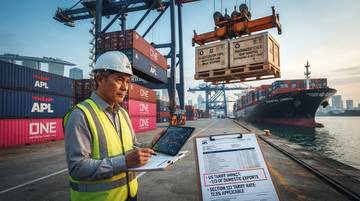
Singapore’s $7.4B Tariff Hit Shows AI-Chip and Pharma Re-Routing Risk Is Now a Balance-Sheet Story (Not Just a Policy Headline)
Singapore’s MTI says the US tariffs are hitting a very large slice of the city-state’s domestic exports, with product exemptions explicitly covering semiconductors and pharmaceuticals—so the “damage” is concentrated in the same shipment backbone that moves AI and healthcare supply chains across Asia. For listed investors, that maps into near-term logistics/customs uncertainty for chip and healthcare value chains, while the long-term question becomes whether firms re-route through Singapore/Dubai-type hubs or re-source production to avoid tariff incidence.
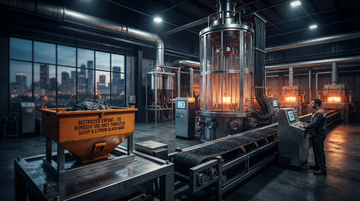
Polysilicon protection + tungsten/black-mass export lockup turns the “2027 refining miss” into a forced US procurement story
Two coordinated Trump-era industrial-policy moves—an EO to shield US polysilicon production and a BIS rule that blocks exports of tungsten scrap and lithium-battery black mass—together convert “tariff fights” into “keep processing at home” constraints. Investors should treat the pair as a supply-chain reallocation shock: domestic feedstock availability tightens first, contracts re-price next, and multi-year capex justification follows.
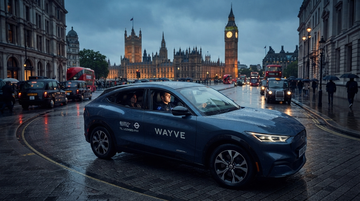
London’s robotaxi approval proves the “rules economy” will beat fleet scale—Uber and Wayve just cleared the UK’s supervised-PHV gate
Transport for London (TfL) licensed Wayve’s autonomous vehicles for Private Hire Vehicle (PHV) operations with a qualified driver onboard, under the Government’s AV Trialling Code of Practice and Uber’s TfL PHV operator licence. The strategic takeaway for investors: this isn’t about how big the first fleet is—it’s about whether a non-US, non-map-first stack can monetize autonomy under constrained supervision, a template regulators from Australia to Singapore are likely to benchmark.
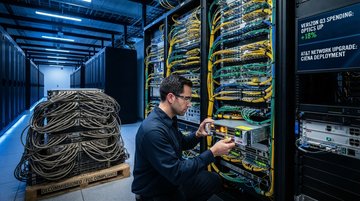
FCC’s Chinese telecom import curbs are starting to act like a capex reroute—here’s the carrier + optical-networking transmission path investors can actually model
The FCC’s expanding ban on imports of certain Chinese telecom and video-surveillance equipment is framed in reporting as more than a pure security measure: it functions as a US-production-reroute lever that can shift how carriers source network buildout hardware. That changes the supply-chain winners by pulling incremental demand toward “non-Chinese-ruled-out” routing/transmission stacks and the US service/install ecosystem, with near-term spend typically landing in optics and network equipment refresh cycles rather than distant software-only compliance.
The “AI vishing” wave hitting hedge funds is really a prime-broker risk test—because it targets access, not just accounts
On Aug 5, 2026, reporting described an attempted wave of cyberattacks that targeted major hedge funds with AI-powered voice-phishing (“vishing”) to gain access to sensitive information systems. The investable implication is that trading-perimeter failures (identity, remote access, and broker integrations) can become a market-plumbing issue, forcing higher spending on zero-trust identity controls and incident-response capacity.
2026-08-05
Cerberus’s $4B Supply Chain Fund II pitch turns private capital into a Pentagon policy lever—because Feinberg is now an underwriting mechanism
Cerberus is targeting at least $4B for its second supply-chain fund, framed as scaling U.S. domestic industrial capacity. The unusual signal isn’t just fundraising size—it’s that Stephen Feinberg’s post as Deputy Secretary of Defense creates a feedback loop where defense-aligned portfolio bets can directly shape the Pentagon’s procurement-and-industrial base priorities.
The DOJ hasn’t (yet) filed the “retail-advice duopoly” antitrust case—but it has already changed the rules that make fee compression a regulatory fight
A search of DOJ/FTC primary material does not confirm a specific, DOJ-filed antitrust case targeting a retail-investor advice “duopoly” (e.g., Schwab/Fidelity vs. Vanguard/BlackRock-style aggregation). What is verifiably active is a broader US enforcement posture against anticompetitive behavior and (separately) “deceptive/unfair fees,” which is the legal lane where broker-advice bundling and pricing tactics are likely to be attacked first.
Etsy's 12% layoff reads like a marketplace GMV reset—not a “trade-down” growth bet
Etsy’s restructuring trimmed about 11% of its marketplace workforce (≈225 people) and targeted a $25–$30M cost charge, signaling management is prioritizing cost discipline over re-accelerating engagement. For investors, the clean read is that Etsy’s problem looks more like platform efficiency under discretionary softness than broad consumer “value winner” rotation—and that distinction matters for how you underwrite post-AI seller-tooling spend.
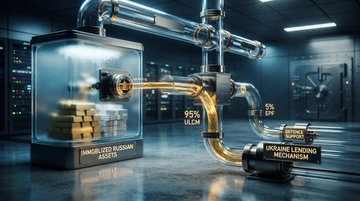
The EU’s €1.4B “interest-on-frozen-Russia” delivery is a new war-funding blueprint—because it turns post-freeze yields into politically prioritized spending
The EU has delivered €1.4B in proceeds from interest on immobilised Russian central bank assets to Ukraine, earmarking it mainly to fund Ukraine-related lending mechanisms and a smaller slice to defence support. The deeper shift is that the EU has operationalised a repeatable plumbing template: use frozen-asset yield streams as reliable financial input for future Ukraine finance—without fully converting the underlying assets into confiscation.
SAP’s AI back-office boom is the “second front” the US tape still ignores
Reuters’ Aug 4 reporting highlights Europe’s established tech firms (led by SAP) seeing AI-related demand move from pilots into funded deployment. The trade implication is simple: while investors chase Nvidia-style compute, enterprise software, systems integration, and infrastructure providers are monetizing AI operations—pulling revenue and backlog growth through the supply chain where the US narrative hasn’t looked.
GlobalFoundries’ Q2 Beat Says AI Demand Has Moved Past Leading-Edge—And That’s a Capacity Bottleneck Investors Can Actually Trade
GlobalFoundries’ Q2 reporting indicates AI-related demand is no longer confined to the newest nodes, with upside coming from the company’s specialty/mature manufacturing strengths. The investment implication is that power/analog/RF/“support silicon” is becoming the binding constraint for AI racks, which can spill over into suppliers of power management and custom silicon.
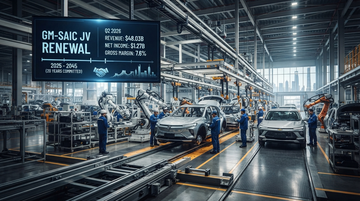
General Motors's SAIC JV renewal makes “decoupling” look optional—because it locks manufacturing in China through 2045
GM renewed its 50-50 SAIC joint venture for 20 years after a restructuring that included plant closures and model elimination, extending the partnership’s manufacturing commitment in China through 2045. That decision reframes the investing debate: US automakers aren’t just choosing where to sell—they’re choosing where to stay and who controls the production footprint. The second-order question now is whether Ford and Stellantis treat JV renewals as a supply-chain strategy template (or an overdue retreat).
OpenAI’s DOJ settlement turns “AI talent” into a DOJ-litigated input—forcing frontier labs to price PERM visa-process risk into H‑1B hiring math
On Aug. 4, 2026, OpenAI agreed to pay $3.2M to resolve DOJ allegations that it discriminated against U.S. workers by preferring temporary visa holders during the PERM process. The case reclassifies immigration compliance from “HR overhead” to a balance-sheet line tied to recruitment channels, posting/application mechanics, and training/reporting costs—exactly the cost routes that determine the marginal cost of scaling overseas AI talent.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.