Policy & Trade
Tariffs, export controls, and who absorbs them
Rulings, sanctions and trade negotiations traced to the companies that pay for them — margin by margin, route by route.
2026-07-26

PDD's peers can’t “price” away tariff math: the SHEIN IPO valuation is now a profitability stress test
Shein’s pre-IPO disclosures link a quarterly net loss to the U.S. shift away from de minimis duty-free treatment, making tariff mechanics a live input-cost and demand driver rather than a distant regulatory risk. For listed fast-fashion bellwethers like PDD, Inditex, and H&M Hennes & Mauritz, the investable question isn’t “will tariffs exist,” but whether gross profit can absorb tariff-driven cost resets faster than sales slow.
Small businesses just sued over “forced labor” tariffs—turning tariff power into a refund-and-injunction fight at the importer level
Two U.S. small businesses challenged the Trump administration’s Section 301 “forced labor” tariffs in the Court of International Trade, arguing the program preserved the invalidated emergency-tariff architecture rather than providing a reasoned, practice-specific remedy. The demand-side wedge matters for investors because it shifts outcomes from “policy backlash” to “case-by-case duty collection, injunction risk, and refund exposure,” with immediate pressure on downstream importers and sellers and longer-run uncertainty for cross-border supply-chain pricing.
Alphabet Is Becoming the Proxy Target in a New US–EU Digital-Sovereignty Trade Fight
The EU’s July 16 DMA actions force changes to Alphabet control points like Android access and search data, while President Trump says the US will retaliate with a Section 301 probe over the EU’s €890m Google fine. For investors, the key risk is not the fine itself—it’s that reciprocal enforcement turns compliance into a repeating headline discount on Alphabet’s next earnings cycle and cloud margins.
U.S. tariff “emergencies” are becoming a permanent import tax—and the pass-through floor is now an earnings risk
The new tariff layers announced around the July 24 expiry window are built on authorities that cover nearly all U.S. imports and can be extended, turning tariff cost into a recurring P&L input rather than a one-off shock. The sectors most exposed are the ones that (1) rely on contract pricing, (2) face long receivables cycles, and (3) have limited leverage to reprice without demand destruction—so pass-through eventually breaks, not instantly.
USMCA’s Steel Tariff “Mirror” Push Turns North America into a Tariff Bloc—And It’s the Working-Capital Story for Nucor, Cleveland-Cliffs, and Ternium
A key USMCA dynamic is shifting: the US is using the 2026 USMCA review as leverage over metals and market access, not just arguing about “free trade” rules. For steelmakers, the investable angle is not only pricing power—it’s whether tariff volatility forces contract repricing, reroutes scrap/inputs, and changes working-capital turns inside the North American steel supply chain.
2026-07-25
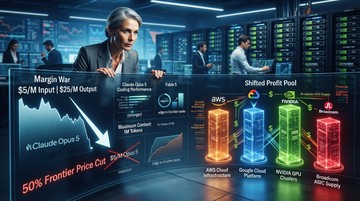
Open-Weight AI’s Next Fight Isn’t About Chips—It’s About Model Vetting as Regulation
At a U.S.-China summit, NVIDIA, Microsoft, and Meta publicly pushed back on “premature restrictions” on open-weight models, arguing that broad limits will push innovation overseas rather than reduce risk. The policy battleground is moving from regulating access to regulating who can run, inspect, and verify weights—because “closed-only” safety claims don’t hold up when models can still be breached or misused.
UAE gets license-free access to “advanced computing” under EAR—potentially repricing the compliance premium across chip and server supply chains
The U.S. reclassified the UAE under the EAR to Country Group A:5 and expanded license-free/STA eligibility for “advanced computing items,” including AI chips and servers, effective July 10, 2026. For investors, the key question isn’t whether demand rises—it’s whether compliance friction drops fast enough to shorten lead times, shift inventory risk, and compress the “safe routing” discount that sellers used to price into contracts.
2026-07-24
Albertsons’ outlook cut turns “trade-down” from a theory into a grocery-aisle fact
Albertsons’ guidance reset—forecasting fiscal 2026 identical sales down 0.5% to 1.5% and adjusted EPS of $1.75 to $1.85—was sharp enough to re-price the consumer story for grocers. The key market takeaway isn’t that the consumer is “weak,” it’s that spending is bifurcating: value-first, mass/discount-leaning trips are taking share from traditional grocery formats, forcing price-investment to defend volume.
Europe’s “buy-local” procurement shifts Lockheed, RTX, and Northrop from premium programs to margin-managed components—while Rheinmetall/BAE/Leonardo take the production leverage
Verified reporting shows the EU’s procurement push is turning “access to platforms” into “access to local sustainment and co-production capacity,” starting with missiles and air-defense spares. For US primes, the margin risk is not losing the customer—it’s winning fewer high-margin builds and more tightly specified work that requires licenses, local partners, and sustainment-heavy economics.
Geely’s “No-Brand-Print” Play in Spain: China EVs First Enter Europe by Taking Over Ford’s Idle Capacity—Not Buying a Publisher-Brand
Geely’s agreement to use Ford’s Almussafes plant in Valencia to produce Geely EVs creates an EU-manufacturing “origin story” that Reuters links directly to avoiding EU tariffs on Chinese EV imports. The real supply-chain message is capacity arbitrage: idle European lines get monetized by China volume, shifting battery/material demand toward whatever can qualify for the JV’s EV ramp instead of whichever OEM owns the logo.
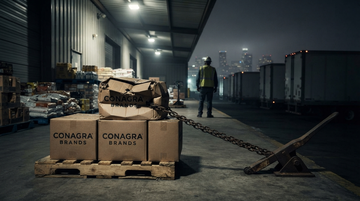
Nestlé and the 'Trojan Horse' Lobby: Why Big Food Is Now Treating the Label as a Balance-Sheet Item
Nestlé, PepsiCo, Coca-Cola and the rest of the AFIT coalition are spending 17x more on Washington lobbying than a year ago — not to fight regulation, but to redefine the federal label itself. The play turns ingredient disclosure from a compliance cost into a margin lever, and Conagra's 50% dividend cut nine days ago is the first hard signal of how exposed the holdouts are.
Oracle’s $7B Pentagon software consolidation win reframes its defense business from “AI megacampus drain” to durable on-prem cashflow
The Pentagon’s nearly $7B, up-to-10-year contract with Oracle is less about frontier AI and more about consolidating sprawling on‑prem enterprise software—plus maintenance and consulting—into a single procurement path. That changes how investors should think about Oracle’s defense exposure: from “spend-heavy AI buildout risk” to a repeatable, subscription-and-license-style government revenue stream tied to IT standardization.
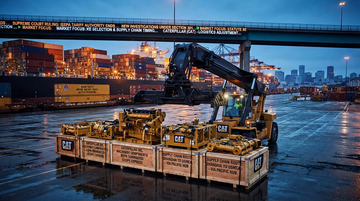
The Supreme Court Quietly Shrinks Tariff Power—So Markets Now Trade the “Surviving Statute” Not the Tariff Headline
The Supreme Court’s February 2026 ruling that IEEPA cannot authorize tariffs forces the administration to pivot to other statutory authorities, changing both how fast new duties can be imposed and how easily importers can challenge them. The July 2026 tariff wave that follows is therefore a “statute selection” story—investor impact concentrates in firms’ cost pass-through, legal exposure, and inventory timing rather than in any single rate.
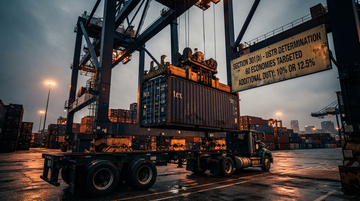
The “60 Partners” Tariff Move Turns a Timed Emergency Into a Structural Import Cost
U.S. Trade Representative action under Section 301 targets imports from 60 economies with proposed additional duties of 10% or 12.5% tied to forced-labor enforcement failures. Because the policy is being built as a Section 301 regime (not a one-off deadline rollover), the replacement is likely to behave like a persistent “cost-of-capital” shock for U.S. importers—raising the bar for future reversals even after temporary authorities expire.
The Vietnam Tariff Shock Is a Margin Bet: Brands Can’t Just “Pay Duty”—They Have to Re-write Contract Math
Vietnam is the apparel exporter that looks most exposed when the U.S. moves from a temporary, broad 10% tariff regime into a higher, country-sliced structure. For the most Vietnam-heavy shippers—like Nike—the spread between Vietnam and alternative sourcing hubs can become a gross-margin event, unless contract pricing and reroute timing are designed to absorb the duty differential.
2026-07-23
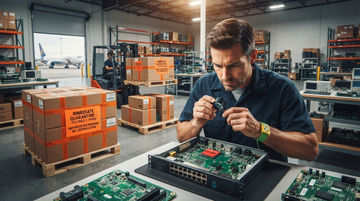
FCC’s “Chinese parts” device ban turns into a replacement-lead-time tax: here’s the compliance checklist for who re-certifies, who loses supply, and who pays delays
The FCC’s move to bar sales of devices containing components from “blacklisted” Chinese firms is best modeled as an equipment-authorization and certification disruption—not just a geopolitical headline. Using FCC’s Covered List mechanics and the communications equipment authorization rules, you can map a practical timeline: upstream testing/authorization constraints force redesigns; downstream buyers then face re-certification and possible sales/importation limits that can translate into margin and delivery shocks.
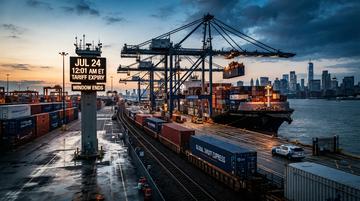
The July 24 Global Tariff Expiration Is a Policy Binary—Markets Won’t Get a “Soft-Landing” Confirmation Unless It Actually Rolls Over
The U.S. “temporary import surcharge” imposed via Section 122 is scheduled to run through 12:01 a.m. ET on July 24, 2026, after which Congress would need to extend it (absent other action). If replacement tariffs meaningfully replace the expiring 10% global duties, the market’s soft-landing/rate-cut trade is at risk—while the cleanest hedge is the dollar/currency complex rather than purely equity beta.
GM’s “Resilient Demand” Margin Lift Implies a Very Specific EV Loss Cessation Path—And Tariffs Remain a Live Variable
GM’s July 21 update frames margin durability around resilient consumer demand and pricing discipline, while simultaneously publishing a 2026 GMNA EBIT-adjusted margin target of 8.0%–10.0% and a 2026 EBIT-adjusted tariff swing of roughly $2.5B–$3.5B. The underlying risk is that EV losses and EV-related charges have recently been material (e.g., multi‑billion dollar realignment charges in 2025), so “resilient demand” only holds if EV mix and incentive intensity don’t force GM back into similar loss dilutions.
Treasury’s Iran sanctions repricing is a term-premium shock in disguise—watch how oil risk leaks into rates, dollar funding, and credit hedges before CPI
The July 2026 Iran sanctions cycle is not just an oil story: market pricing implies a higher embedded “energy risk premium,” which then spills into Treasury term premium and the macro risk register. The investable implication is hedge selection—duration and curve hedges may outperform purely commodity hedges early, while FX and credit hedges are likely to require faster, more conditional trigger rules.
Sanctions Are Coming for “Distilled” AI — and It’s a Policy Shift from Chips to Model Weights
The US is treating large-scale distillation of a US model (Anthropic’s “Fable”) as potential “IP theft” with sanctions and Entity List designations “on the table,” per Treasury Secretary Scott Bessent. The key market implication is that US-China AI investment risk now depends not just on access to chips, but also on whether a frontier model’s outputs are being converted into deployable weights in ways the US deems covert.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.