Policy & Trade
Tariffs, export controls, and who absorbs them
Rulings, sanctions and trade negotiations traced to the companies that pay for them — margin by margin, route by route.
2026-08-16

Nevada’s geofencing fine targets the real prediction-market bottleneck: state regulators—not the CFTC
Kalshi’s dispute with Nevada’s Gaming Control Board over an alleged geofencing failure has moved from a licensing argument into an operational compliance fight with a $120,000-per-day price tag. If state gambling regulators keep winning on “in-state access,” prediction-market growth will hinge less on federal exchange status and more on whether each state’s licensing rules can be translated into enforceable geofencing.
NVIDIA’s Aug. 26 print is the AI trade’s “guide-bar” moment—can it outgrow the capex-and-allocation scare?
After a week of semiconductor repricing, the Aug. 26 NVIDIA report becomes the highest-stakes single catalyst because investors are no longer only buying growth—they’re buying confirmation that the next platform ramp (Vera Rubin) is not being choked by supply constraints or capex confusion. The last confirmed NVIDIA quarter shows extreme profitability and strong cash conversion, but the forward-risk is now whether the next guide keeps gross margin and operating expense discipline intact while revenue accelerates into the Vera Rubin deployment window.
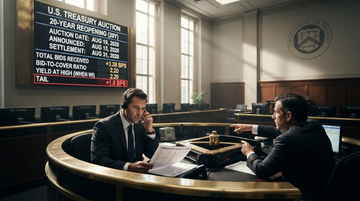
The 20-year Treasury auction is the steepening trade’s real stress test—because it prices the duration “bid” before AI capex gets discounted
The next US Treasury 20-year auction (auction date Aug 19, 2026) sits at the weakest point of a steepening narrative: the least-liquid tenor where weak demand shows up fastest via a larger “tail.” If the auction clears with a meaningfully weaker demand signal, long-duration equities and high-quality IG funding used to finance AI buildouts tend to reprice higher on yields—before issuers see the relief.
Native-born unemployment is rising while wages stall: the “America-first” labor contradiction investors still haven’t priced
New labor-market reporting highlights a split outcome: U.S.-born unemployment is moving higher while wage growth is no longer keeping pace with inflation. That mismatch matters for the Fed and for consumer-cyclical earnings because it signals pressure on household labor income without a clean unemployment-relief path.
2026-08-15
Early giving now beats year-end: the new 2026 charitable deduction floor rewires DAF timing—and financial-services cash flows
Congress’s change effective in 2026 adds a new “first 0.5% of AGI” floor for itemizers’ charitable deductions, turning the traditional year-end rush into an earlier-year optimization problem. That shifts donor cash into donor-advised funds (DAFs) sooner, changing the timing of advisor work, client tax-planning pipelines, and the seasonality of DAF asset growth.
The $1T crypto rout isn’t mainly an “ETF outflow” story — it’s the leverage unwind that punishes day-trader-style funding
A fast, large crypto drawdown tends to hit the same part of the market every time: leveraged positioning and the short-duration cash funding behind it. That matters for fund complexes that monetize “active” crypto exposure through carry/yield-style mechanics, because redemption pressure and margin-liquidation losses can force deleveraging before ETF-style flow data shows anything.
Central banks bought a record 288.9 tonnes in Q2—gold’s August rally is now an official-sector story, not a Fed-timing trade
World Gold Council data shows central banks and other official institutions added a record 288.9 tonnes in Q2 2026 (+62% year over year), alongside a 2026 survey where 45% of reserve managers still plan to add gold over the next 12 months. That shifts the rally’s durability math: the bid is decoupling gold from “Fed-cut hopes fade” narratives, improving the risk/reward for miners and bullion-linked vehicles.
Jane Street’s alleged $15B July loss turns the “AI crowded trade” into a balance-sheet contagion risk
Reporting tied to a private AI hedge fund’s forced unwind has put a $15B monthly hit on Jane Street, reframing July’s AI volatility as more than a sentiment reset. The key issue for investors: when highly correlated AI positions unwind through leverage and prime-broker financing, the market-making layer can absorb correlated shocks and transmit stress upstream and downstream through liquidity and pricing.
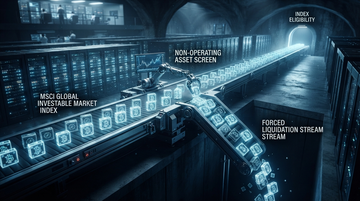
MSCI plants a “non-operating” eligibility trap that makes Strategy’s bitcoin treasury structure a forced-sale risk
MSCI has launched a consultation to screen “non-operating” companies out of its MSCI Global Investable Market Indexes, using operating-asset intensity and cash-flow style ratios. If rules are implemented for index changes effective at the close of Aug. 31, 2026, Strategy is exposed because its balance sheet is dominated by investment assets rather than operating assets, and the market impact can cascade through passive flows and forced crypto rebalancing by similarly structured issuers.
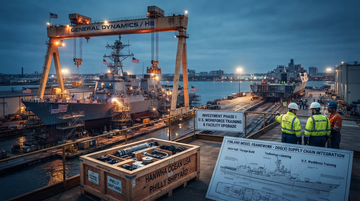
Trump’s “Finland Model” opens a limited route for foreign-built U.S. Navy hulls—Hanwha Ocean and Fincantieri gain optionality while GD/HII lose their “U.S.-only yard” pricing power
A White House memorandum signed Aug. 13, 2026 lets qualifying foreign shipbuilders build initial Navy hulls abroad while requiring major U.S. yard investment, U.S. workforce training, U.S. supply-chain sourcing, and technology licensing. The near-term demand signal is most supportive for Hanwha Ocean and Fincantieri, because they already have large U.S. shipyard footprints, while the traditional U.S. prime shipyard duopoly faces a structurally wider builder base and more competitive capacity.
SEC’s $74M “boiler room” case puts retail cash economics behind private-share liquidity—and shows why hidden fees are now the center of the fraud story
The SEC charged Andrew Spaventa and three related entities with defrauding more than 800 mostly retail investors—including many retirees—through unregistered pre-IPO private fund offerings tied to companies including SpaceX, Anduril, and Anthropic. In the SEC’s allegations, investors were paid “hidden fees” created by large markups—turning private-company liquidity into a fee-heavy distribution channel the SEC says reached Main Street on cold calls.
2026-08-14
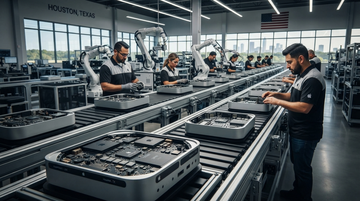
Apple's Mac mini Texas shift turns “Made in USA” into a COGS experiment — and it flows through EMS more than patriotism
Apple opened its Houston Advanced Manufacturing Center on Aug. 13, 2026 and tied it to starting Mac mini production “later this year” in Texas, marking the first time the Mac mini is made in the U.S. for sale. The investment matters to margins only if the higher-cost U.S. assembly footprint can be neutralized via supplier localization, logistics control, and tariff-avoidance—an outcome the first steady-state volume run will test.
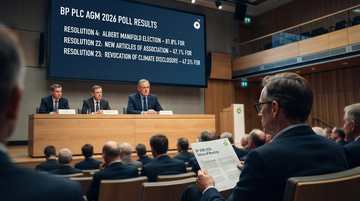
BP’s AGM vote didn’t just reject resolutions—it pressured the company to defend its climate governance and capital discipline trade-off in front of the market
At BP’s AGM on 23 April 2026, shareholders rejected three key contested items (resolutions 22, 23, and 24), including moves tied to climate disclosure and project-level reporting. The pattern matters for investors because it tests whether BP can keep funding shareholder returns while simplifying governance—without losing the institutional consensus that supports supermajor capital-return frameworks.
The COMEX–LME copper spread is pricing tariff odds months before policy headlines—here’s who reprices first
A niche trade—using the COMEX–LME copper spread to infer U.S. refined-copper tariff expectations—has become a leading “policy gauge” rather than a pure commodity signal. When the spread widens, it compresses arbitrage between U.S.-delivered and London-priced copper, pulling forward capital-market and physical-trade decisions first for copper producers with U.S. exposure and for import-sensitive buyers.
GLM-5.3’s “leak” likely proves one thing: China’s open-weight speed collides with Washington’s frontier-model pre-review window
A wave of early GLM-5.3 chatter is surfacing ahead of an Aug. 9–25 window, but Zhipu has not publicly confirmed a GLM-5.3 release or open-weight artifact. The strategic crux is policy timing: the U.S. executive order on frontier AI introduces a federal pre-release access concept described as up to a 30-day window, which would reward labs that can ship and distribute open weights faster than review can be completed.
The market just priced the Iran oil-shock “fade.” The US plan due next week re-prices the term premium—and shipping risk—before crude ever fully turns
A White House “economic isolation” approach for Iran—paired with continued pressure at Hormuz—reintroduces an anxiety channel the market already tried to dismiss: higher risk premia in rates and energy transportation costs. The immediate trade is less about another WTI headline and more about whether financial isolation again makes future barrels costlier to move and insure.
Flat July PPI + the first 7,800 S&P close reset September: the “hawkish-hold” trade dies, but only because AI/tech keeps leading
July CPI held at a 3.4% pace and July PPI was flat, removing the inflation “re-acceleration” trigger markets had been pricing for September. With the S&P 500 closing above 7,800 for the first time, the market’s disinflation rotation reasserted itself—yet the leadership is still concentrated in AI/semiconductor beta, not cyclicals.
Morgan Stanley's gold-to-silver shift reframes the safe-haven trade into an industrial bet
Morgan Stanley says gold is increasingly behaving like a risk asset rather than a portfolio diversifier, while pointing to silver as the metal with “real reasons to rally.” For miners and investors, the implication is a supply-chain rotation: gold hedges face a more saturated macro setup, while silver’s tight multi-year balances and industrial demand (notably solar) can re-price both upstream (silver miners’ cash flows) and downstream hedging demand.
Steam- and hydraulic-driven catapult changes could flip aircraft-carrier electronics content—rewarding legacy electromechanical supply chains while pressuring modern shipboard-electronics primes
A new White House directive orders the Navy to replace EMALS and advanced weapons elevators with steam and hydraulic systems for future CVN-81. That reverses the shipboard electronics content mix: it shifts value from modern electromechanical-and-software-heavy launch/recovery subsystems toward legacy electromechanical/hydraulic supply chains, while also introducing schedule and cost risk for carrier programs near industrial capacity limits.
Tapestry's FY27 outlook makes the “affordable-luxury re-rating” a numbers test: Coach is accelerating, but tariffs and terminated Capri costs can still cap the multiple
In its fiscal-Q4 results released Aug. 13, 2026, Tapestry showed Coach delivering double-digit growth (Q4 net sales +15% reported) while explicitly acknowledging a negative tariff and duty impact that partially offset margin gains. The same print also tallies material Capri-related termination/divestiture impacts (notably $268.4M of pre-tax expenses in FY25 tied to the terminated Capri deal), setting up a clean investor question: does Coach momentum outweigh cost/tariff noise in the next few quarters?
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.