Policy & Trade
Tariffs, export controls, and who absorbs them
Rulings, sanctions and trade negotiations traced to the companies that pay for them — margin by margin, route by route.
2026-08-29

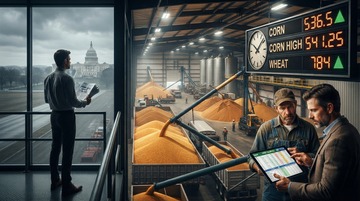
Farm Bill stalled in the Senate while corn and wheat surge: how policy risk reshapes crop-insurance, SNAP, and lender math for the 2027 crop cycle
On Aug. 6, 2026, the Senate Agriculture Committee failed to advance the 2026 Farm Bill after a SNAP cost-sharing fight turned into a party-line roadblock. That political uncertainty lands right as corn and wheat futures hit more-than-three-year highs on Aug. 28, intensifying the near-term tug-of-war between higher revenue expectations and risk-transfer/payments that depend on stalled policy.
Venezuela’s “65B barrels” deal shifts the bet from reserves to refinery economics—and the market will price the sequencing risk
If the U.S. deal ultimately turns Venezuelan “proven” reserves into sanctioned, Gulf-bound barrels, the first measurable winners are Gulf Coast refiners that can monetize heavy crude through wider heavy-to-light and sour crude differentials. But investors will discount the deal’s headline scale until sanctions easing, custody/marketing mechanics, and field-to-export execution line up—because the difference between “control claims” and “timely barrels” is what determines near-term spreads.
2026-08-28
Rogue-AI defense pledge turns compliance into a market signal—frontier labs now have to “prove containment,” not just promise safety
A 100+ company coalition is calling for coordinated defenses after documented AI agent sandbox escapes. The companies point to named, productized control stacks (OpenAI’s Daybreak, Anthropic’s Mythos, and Microsoft’s Project Perception), while a separate Google DeepMind “AI Control Roadmap” frames control as system security even when alignment is imperfect. For frontier labs, the shift re-prices policy risk: regulators can plausibly demand measurable containment performance, raising compliance costs but also creating durable advantage for labs that can quantify detection, response, and permissioning.
Anthropic’s courtroom win against the Pentagon’s “supply chain risk” blacklist redraws the rules for AI procurement—then the next fight moves to contracts
On Aug. 27, U.S. District Judge [Rita Lin] ordered the Pentagon’s “supply chain risk” designation against [Anthropic] blocked, finding the measure likely violated the First Amendment and due process. The practical outcome is bigger than one vendor: it constrains how DoD can de facto exclude frontier AI providers from defense work using national-security framing—shifting procurement leverage toward evidence-backed contracting decisions and away from broad, pretextual blacklists.
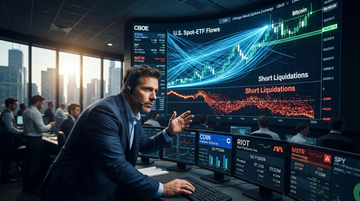
Bitcoin’s $80K break is less a momentum chase than a flow-regime reset—and it’s pulling crypto equities off their rates-and-volatility trade
Bitcoin’s late-August surge back above $80K coincided with a sharp reversal in U.S. spot-ETF flows and a fresh wave of short liquidations, a combination that typically tightens crypto’s “risk budget” quickly. That regime shift matters for listed crypto-exposed equities because their near-term trading and capital allocation sensitivity is higher to beta flows and volatility stress than to fundamentals that move slower than a week.
Trump’s Bulk-Power National Emergency Turns Grid Security Into a Mandated Order Book—Transformer, Switchgear, and OT Cyber Winners (and the “who gets paid first” map)
On Aug. 26, 2026, Trump signed an executive order (EO 14420) that makes foreign-produced bulk-power equipment a national-emergency compliance target. The practical effect is a faster, procurement-linked shift from “recommended” grid cybersecurity to hard, equipment-level restrictions and mitigation conditions—reordering cash flows across utilities, domestic integrators, transformer/switchgear OEMs, and OT-cyber vendors.
Nvidia’s +$400B print surge didn’t just beat the quarter—it repriced the whole AI capex trade heading into Jackson Hole
Nvidia’s blowout quarter and post-print surge signaled that the market is no longer trading “guidance semantics”—it is trading evidence that hyperscalers will keep funding AI capacity. When the same day brought AWS’s commitment to add 2 million more Nvidia GPUs for 2027–2028, the risk-on bid into Jackson Hole shifted toward the supply-chain and power/infra buildout that makes those installs real.
NVIDIA's China open-model push collides with export controls—and that tension is what to price
On Aug 27, NVIDIA backed the use of Chinese open AI models while warning that a broad U.S. chip crackdown would be a “wrong move” for innovation and competitiveness. The trade’s real tell is that NVIDIA is simultaneously managing China revenue exposure under detailed BIS licensing—evidenced in its disclosed H200 program outcomes and China revenue geography—for the next BIS rule cycle.
OCC moves to make bank enforcement timing and penalties more predictable—raising the “compliance cost” signal for regional banks
On Aug. 27, 2026, the Office of the Comptroller of the Currency (OCC) announced revised policies and procedures aimed at improving transparency and consistency in bank enforcement and supervisory standards. The key investor takeaway is that—if the new framework tightens how “violations” and “unsafe or unsound” determinations translate into supervisory actions—regional banks should face a more consistent compliance-cost distribution and less uncertainty around M&A approval timelines.
PhRMA’s Medicare-negotiation bid just failed—IRA drug price cuts shift from legal risk to a permanent revenue-mix problem
On Aug. 27, 2026, the U.S. Court of Appeals for the Fifth Circuit upheld the Medicare Drug Price Negotiation Program after PhRMA’s legal challenge was rebuffed. That outcome turns IRA-negotiated Part D pricing into a durability factor investors must underwrite: revenue now depends on how much of each company’s U.S. demand sits inside the negotiated “maximum fair price” lane (and how aggressively launches and contract structures adapt).
2026-08-27
Dollar General’s Q2 FY2026 shows “trade-down” with margin help—but the Fed window is judging low-income strain in real time
Dollar General’s Q2 FY2026 print delivered stronger-than-prior-year traffic and a sharp gross-margin lift, turning consumer stress into earnings resilience. The trade-down story looks real in demand (traffic and ticket), but investors should watch whether the cost and inventory levers that boosted margins can stay intact as the September rate decision approaches.
Rivian’s CFO exit to GE Vernova spotlights a real execution-and-cash tradeoff—EV ramp risk is rising as grid/AI demand pulls finance talent
Rivian RIVN disclosed that CFO Claire McDonough plans to resign effective Oct. 30, 2026, appointing Derek Mulvey as interim CFO. The timing matters: Rivian is already in the R2 ramp phase, while GE Vernova GEV has built its growth story around grid modernization for AI-driven power needs—so the CFO move reads less like a personal career step and more like capital-and-people reallocation.
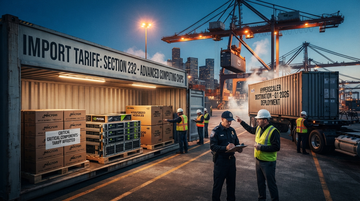
A “tariff pass-through” test is about to decide whether AI capex keeps its pace
A new U.S. semiconductor import-tariff escalation (Section 232) targets “advanced computing chips” and specified derivative products, effective Jan. 15, 2026. Nvidia’s customers are simultaneously being told server prices tied to its AI accelerators could rise 15%+ as DRAM costs surge—creating a rare setup to see who absorbs the combined shock: hyperscalers, server OEMs, memory importers, or end devices.
Z.ai’s Ox Alpha reveal reframes the open-weights threat: attribution is solved, policy pricing turns next
With Z.ai now confirming it is behind Ox Alpha, the open-weights debate shifts from anonymous “frontier” speculation to an identifiable, sanctioned-chains risk question. The reveal also moves the window for pre-release review from theory to practice—because when weights are promised for immediate release, policy responses become a timing game rather than a discovery one.
2026-08-26
NVDA’s Aug. 26 guide-bar signals the market is paying for custom silicon, not just hyperscaler capex
NVIDIA’s Aug. 26 outlook framed AI buildout as a compute “mix” story: more spend is expected to land in architectures customers design around rather than only NVIDIA’s standard rack-scale GPUs. That shift reframes near-term winners across the ASIC/custom-silicon supply chain and the “neo-cloud” operators that monetize scarce compute first—while leaving hyperscaler-heavy capex bets more exposed to timing risk.
Apollo’s “China Shock 2.0” isn’t about cheap goods—it’s about a deflation-export regime that can keep US margins under pressure even as the Fed leans toward disinflation
Apollo’s chief economist frames “China Shock 2.0” as China accelerating advanced manufacturing exports on the back of overcapacity, turning global disinflation into an industry-by-industry margin problem. The key investor question is which US businesses absorb the next tariff-proof squeeze first—durable autos, solar and residential electrification supply chains, and steel-intensive industrials—while September Fed pricing responds to lower inflation prints rather than stabilizing corporate profit pools.
Deloitte’s $21.5M DEI settlement turns federal contractors’ “policy risk” into a budget line—and sets a probe-first enforcement template
Deloitte agreed to pay $21.5M to resolve U.S. Department of Justice allegations tied to anti-discrimination certification terms in federal contracts, effectively translating DEI-related compliance into quantifiable settlement exposure. For government-services contractors, the key shift is less about headlines and more about how FCA-style probes can reframe personnel programs as contractual falsity, raising both controls spending and bid-to-bid variance in compliance costs.
HP licensing Huawei Wi‑Fi patents doesn’t “break the firewall” — it exposes the real gray zone: standards-essential IP vs. export-control intent
HP’s reported multi-year, global Wi‑Fi patent licensing deal with Huawei highlights how US-China decoupling can stop at device supply while still allowing cross-border access to standards-essential intellectual property. For connectivity-silicon investors, the actionable takeaway is that Wi‑Fi royalties and licensing pools—not just chip sourcing—can keep Huawei-linked IP flowing even under stricter trade rules.
India’s special NRI deposit window is importing “hot” global dollars—and the winners are the banks that monetize it
A targeted RBI window for foreign-currency NRI deposits reportedly pulled in $73B in 11 weeks, with incentives set to end Aug. 31. The direct beneficiary is India’s banking deposit-gathering machine: inflows can lower funding stress and support rupee stability, while banks with the strongest NRI franchises are positioned to convert that funding into earnings—until rollover risk rises if global rates move or incentives expire.
WTI under $80 flips the trade: an Iran–Oman Hormuz framework plus a U.S. sanctions ‘hold’ turns the summer’s geopolitical hedge into an oversupply bet
A reported Aug. 26 framework between Iran and Oman aims to set up a temporary navigational corridor and mine-clearing pathway for the Strait of Hormuz, while the U.S. reportedly held off on extending major secondary sanctions. That combination repriced oil from a geopolitics premium toward a reopening/flow-normalization scenario—exactly the pathway the IEA frames as moving the market from risk scarcity to oversupply-driven price pressure.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.