Policy & Trade
Tariffs, export controls, and who absorbs them
Rulings, sanctions and trade negotiations traced to the companies that pay for them — margin by margin, route by route.
2026-09-01

The carry trade gets squeezed twice: Japan’s 30-year JGB yield at 4.19% collides with joint yen intervention funded via Fed backstop
Japan’s long-end borrowing cost is now pressing at fresh highs, with the 30-year JGB yield at 4.19% on Sep 1, 2026. At the same time, the U.S. and Japan moved to buy yen (July 31) and Bessent urged that the Fed’s FIMA backstop be upsized, tightening the funding leg of global yen carry from both duration and FX angles.
EU antitrust pressure on Oracle’s licensing mechanics turns AI capex into a regulatory cash-flow bet
Oracle’s EU antitrust overhang targets licensing practices that underpin its recurring revenue model—exactly the revenue stream investors rely on to fund aggressive AI data-center buildout. With Oracle reporting $55.7B in capex for fiscal 2026 and expecting the build to continue, the key investor question is whether regulatory remedies can slow the cash conversion that the capex plan requires.
India’s “Urals stop-buy” risk: when a 100% secondary-tariff threat forces discount crude to reprice—tankers, refiners, and the diesel balance sheet
Washington’s 100% secondary-tariff threat on buyers of Russian oil turns energy sourcing into a live diplomatic lever for India. The shift matters because Urals discounts don’t just move barrel economics; they change the whole logistics stack and the regional product balance, where refinery runs, product spreads, and vessel earnings can move in the same quarters.
Texas freezes AI data-center “ghost demand” — and the scarcity-rent power trade just lost its clean story
Texas regulators moved to pause new ERCOT data-center grid connections pending an audit of large-load requests, challenging load forecasts built on speculative interconnection queues. That forces a re-check of the “AI power scarcity” thesis: the scarcity rent may still exist, but its timing and magnitude now hinge on how many of those requests actually energize and how quickly generators and wires can follow.
Bessent’s Treasury buybacks aim to stop the bond market from turning into credit damage
On Aug. 19, 2026, the U.S. Treasury expanded its longer-dated nominal buybacks—raising the per-operation maximum to at least $4 billion effective Sept. 9, 2026—explicitly to add liquidity during a rates selloff. The investable takeaway is that when the Treasury curve starts behaving disorderly, the first transmission is not always “rates,” but funding stress that widens credit spreads and reprices duration across IG issuance and equity valuations—well before any clear policy win shows up.
DHS’s no-bid crypto tracing contract turns “regulated rails” into a political relitigation—who wins the custody/settlement race
A Department of Homeland Security award for crypto-tracing analytics—reported as a no-competitive-bidding deal to TRM Labs—has triggered a bid protest, making government “regulated-rails” vendors a near-term political battleground. The market-structure implication is simple: if custody/settlement permissions move under the CLARITY 2026 timeline, contract-award uncertainty can reprice which listed platforms are best positioned to scale the compliant stack.
2026-08-31
How an “ad auction” remedy could squeeze Amazon’s retail-media profit engine—and tilt ad budgets to rivals
The FTC and 22 states sued Amazon over allegations that it secretly inflated prices in its online advertising auctions for years, seeking injunctions and monetary relief. The economic risk for Amazon isn’t just refunds: a court-ordered change to disclosure and auction mechanics would directly attack the “toll” it charges sellers and brands—and could shift retail-media spend toward ad networks and retail-media platforms that can credibly offer cleaner, more verifiable pricing.
Trump’s bulk-power emergency turns Tesla’s energy stack into the “grid-flexibility” policy floor—Megapack deployments and VPP dispatch rules matter more than Solar Roof tiles
Executive Order 14420 targets national-security risk in U.S. bulk-power equipment (including backup generators) and directs the Department of Energy to implement rules to secure reliability and cyber resilience. Combined with Tesla’s Solar Roof exit from new tile sales, the policy shift increases the market relevance of Tesla’s Megapack and dispatchable flexibility—especially where virtual power plant (VPP) programs convert reliability needs into contracted, dispatch-triggered value.
Trump’s Teva and Astellas “most-favored-nation” deals shift drug-price risk toward manufacturers—and toward PBMs’ net-price math
Trump’s administration announced a new round of bilateral “most-favored-nation” style pricing agreements that include Teva and Astellas Pharma, tied to state Medicaid access and foreign-price parity. Unlike the IRA negotiation framework, this voluntary approach can change net-price expectations across generics and branded portfolios—and force PBMs and manufacturers to re-cut incentives around list-to-net spreads.
Washington turns sanctions into state shareholding: a 35% equity stake and 20% offtake rights in Venezuela could rewrite Chevron’s barrel math
The U.S. is moving from restrictions to direct economic ownership in Venezuela, seeking a 35% stake in North American Blue Energy Partners alongside preferential rights to buy 20% of production under a 25-year framework targeting more than 1.5 million bpd. If the deal’s throughput materializes, it strengthens the U.S. margin capture link from upstream barrels to Gulf Coast refiners—while forcing investors to reassess how quickly Venezuelan supply can be “made bankable” for U.S. counterparties.
2026-08-30
Marvell is down ~6% because the market treats custom silicon as a trade-off, but earnings show hyperscalers are funding both
Marvell’s Aug 2026 earnings-week narrative looked like a zero-sum fight between Nvidia GPUs and hyperscaler custom silicon. But Marvell also disclosed a Google custom-silicon framework that explicitly attaches to the TPU ecosystem, while Nvidia’s earnings reinforced that hyperscaler demand isn’t stalling. The lesson: custom silicon is additive capacity for the AI stack, not a replacement cycle—so the tape is likely mispricing who grows faster as budgets expand.

US–Canada tariff walls are turning magnesium, gallium and germanium into a hidden factory-cost fight—autos, chips and aerospace are the transmission lanes
Canada’s retaliatory tariff schedule effective Sep 8, 2026 creates a direct cost wedge on U.S.-origin tariff lines tied to critical minerals—including magnesium content at the “99.8% by weight” threshold. The bigger market risk is not headline metals—it’s which U.S. industries consume those mineral inputs through alloys, optical/semiconductor processing and defense/aerospace components, and whether North American resourcing can replace China-linked supply quickly enough.
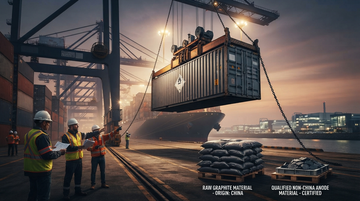
Graphite anodes just became the EV-and-storage bottleneck—because the U.S. tariff/export-control regime targets the active-anode link
The binding constraint in the lithium-ion supply chain is shifting from headlines about lithium to the graphite anode value chain—where China’s processing dominance collides with U.S. trade enforcement. A February 17, 2026 Commerce dumping determination for “active anode material from China” sets estimated weighted-average dumping margins at 93.50% (and 102.72% for the China-wide rate), making non-China qualification and contracting the near-term scramble for EV and grid-storage developers.
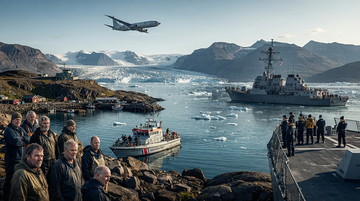
Iceland’s EU “no” breaks the only slow-moving anchor—Arctic policy now tilts toward power, patrol capacity, and extractive leverage
Iceland rejected restarting EU accession talks by 52.8% to 47.2% in a late-August referendum that opponents framed around sovereignty risks. With the US pressing Greenland through “national security” arguments and NATO simultaneously tightening Arctic posture, the Arctic is shifting from diplomacy-by-institutions toward competition by presence—raising the premium on surveillance, ice-capable lift, and defense supply chains.
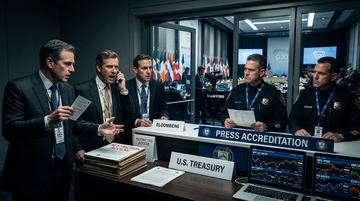
Treasury’s credential blackout for NYT, WSJ, and Bloomberg risks a wider FX-and-bonds uncertainty premium
The U.S. Treasury has denied credentials to specific reporters from The New York Times, The Wall Street Journal, and Bloomberg for the upcoming G20 finance coverage window, even as it pushes bond-market intervention messaging and raises the stakes of tariff-driven policy uncertainty. When policymakers restrict the most trusted institutional reporting channel during active market interventions, investors typically demand a higher risk premium because verification and narrative-checking slow down—raising near-term volatility and widening the gap between what markets price and what they can confirm.
Cheese-name fights are now a live USMCA timing test: why “Parmesan-type” labels can slow the Mexico track and reshape dairy-flow economics
A new U.S.–Mexico friction point over protected cheese names is colliding with the first 2026 USMCA review window. Because cheese labels act like market-access rails for bulk and branded supply chains, the dispute can change what clears customs and how fast exporters redeploy volume—before tariffs and quotas even become the headline.
2026-08-29
Burlington's “tariff-refund beat” flips the margin-quality question: can lower prices keep earning without the refund cash?
Burlington reported strong EPS momentum in Q2 FY26 and raised FY26 adjusted EPS guidance, but the quarter’s sales/margin setup included a $55.5M tariff-refund benefit recognized in cost of sales. That creates a direct test: whether Burlington can reinvest refund dollars into sharper prices and still sustain earnings power after the one-time tailwind fades.
CFTC turns “Trump trade” into enforceable insider trading: $172,539 penalty for betting on advance speech wording
The CFTC fined former White House teleprompter operator Gabriel Perez $172,539 for trading Kalshi “mention market” contracts using advance access to nonpublic Trump speech text. The case matters to markets because it treats political communications as tradeable “information,” collapsing the line between political insiders and prediction-market traders—and raising compliance risk for any firm that lets employees monetize what they know.
CXMT’s 1260H lawsuit turns a policy label into a DRAM pricing question
CXMT’s suit challenges the Pentagon’s “Chinese military company” designation that can trigger U.S. procurement restrictions under Section 1260H. The key investor takeaway is whether courts keep narrowing designation power—making it harder to wall off capital from China’s DRAM buildout—and therefore shifting the balance of risk across Micron, SK hynix, and Samsung Electronics.
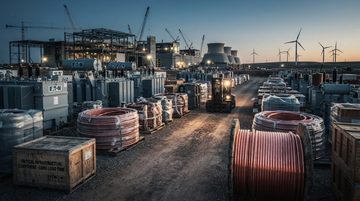
The grid emergency isn’t a power-policy problem—it’s a materials bottleneck upstream of the turbine
The U.S. has framed a national emergency around the foreign supply of bulk-power electric equipment, because reliability can’t wait for long lead-time replacements. At the same time, data-center electrification faces a copper chain strain, while the wind-and-grid buildout still depends on rare-earth magnets. Investors should watch which listed suppliers can convert constrained input availability into backlog, pricing power, and margin support.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.