Aerospace, Defense & Space
Defense budgets and the contractors behind them
Procurement rounds, backlogs, launch cadence and rearmament programmes, read as multi-year revenue with the primes and suppliers named.
2026-07-28

2026-07-27
Amazon turns a 5,105-satellite direct-to-device plan into a spectrum + handset + carrier-power contest
Amazon’s proposed 5,105-satellite LEO direct-to-device (D2D) system reframes satellite connectivity from an emergency add-on into a carrier-grade service layer. The economic battleground shifts toward which operator controls (1) the right spectrum to reach unmodified phones, (2) launch-and-capacity cadence, and (3) device/carrier distribution—making launch partners and MSS spectrum owners strategically closer to the handset profit pool.
Nasdaq’s 15% Revenue Jump Looks Like Mix Shift, Not Just More Trading Volume
In Nasdaq’s latest quarter, total net revenue rose 15%, while Market Services's segment net revenue rose 11%—a smaller step than the consolidated growth. The implication for investors: upside is leaning on recurring index/data/workflow economics, but the stock still inherits cyclical sensitivity through trading-activity and listing-driven flows.

Pentagon’s “years behind Ukraine” drone admission turns into a stock-picker’s map: who gets the bridge contracts (and who gets stuck with legacy scale)
The Pentagon has publicly acknowledged that U.S. industry is still years away from matching Ukraine’s wartime drone output, reframing the U.S. drone push as an industrial-capacity gap problem—not just software or tactics. For investors, the immediate read-through is a procurement bridge: winners should be the firms that can scale production and backlog conversions fast under DoD funding momentum, while legacy primes face slower ramp and execution risk even if their total defense budgets benefit.
2026-07-26
FAA’s $2.2B Airline Retrofit Rebate Quietly Turns the Altimeter Upgrade into a 2027 Supply-Chain Price War
The FAA is tying part of the C-band wireless proceeds to a radio-altimeter upgrade schedule by offering up to $2.2B in rebates to eligible airlines that retrofit to withstand 5G interference. That converts what looked like an aviation-safety compliance cost into a structured, time-bounded industrial-policy transfer—creating a near-2027 decision fight between airlines’ fleet replacement plans and avionics upgrade timing, while boosting demand visibility for airframe OEM and avionics suppliers.
Embraer's record backlog only matters if suppliers and engines stop slowing the delivery clock
Embraer reported a US$34.5B backlog in 2Q26, up 16% YoY, but the market’s real question is conversion: how much of that backlog becomes near-term deliveries and working-capital cash flows.Backlog can stay “high” while cash timing slips when delivery slots are constrained by engines and upstream components; the supply-chain risk shows up in the gap between backlog growth and liquidity/FCF generation.
Nasdaq’s Pre‑Earnings “Capex Confession” Sell Signal Hits Semis First—Because Hyperscaler Guidance Can Break the Math
On the tape, the Nasdaq can reprice AI exposure before hyperscalers even print, when investors treat guidance tone as a proxy for whether $300B+ of planned infrastructure spend stays intact. For semiconductors, the key risk isn’t “AI demand exists or not”—it’s whether hyperscaler capex cadence and margin narratives soften fast enough to pull forward a downgrade cycle through the supply chain.
2026-07-25
Anduril’s ~$100B talk is a software-multiple bet—but only if it can manufacture like a defense prime
A reported round in which Anduril could be valued at about $100B would test whether investors will underwrite defense autonomy on “growth + speed” instead of traditional procurement denominator math. The value hinges on proving repeatable production ramp, durable backlog conversion, and system-level sustainment economics—otherwise the Pentagon’s old guard can defend share by slowing adoption and raising integration friction.
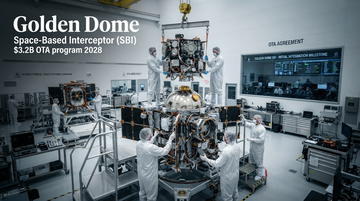
U.S. “Golden Dome” shifts from program hype to a 2028 capacity-and-integration test—timing becomes the real risk
The U.S. Space Force’s Space-Based Interceptor (SBI) awards for Golden Dome lock in a multi-vendor prototype sprint aimed at demonstrating initial capability by 2028. For investors, the key isn’t just who won—it's whether primes and subsystem suppliers can convert those OTA-funded prototypes into integrated, production-relevant capacity as budgets move from planning to deployment.
Embraer’s backlog can’t be a “capacity moat” if suppliers control the delivery clock
Embraer’s backlog hit record levels (total backlog of $32.1B in 1Q26), but the investable question is whether orders convert into near-term deliveries and operating cash. Embraer's cash flow and working-capital profile suggests conversion is possible—but supplier-constrained build slots can still push cash timing out faster than revenue recognition.
Starship’s “pause-to-prove” moment reframes the US launch complex’s next-3-year valuation math around cadence, not just cost
Starship’s latest “market-watching” step isn’t a new performance claim—it’s a test of whether the US launch complex can sustain sub-monthly tempo without hidden reliability drag. For listed suppliers of launch hardware and mission assurance, the investment question shifts from theoretical reusability to whether launch providers can win contracts that require repeatable schedules and liability/insurance confidence.
2026-07-24
Europe’s “buy-local” procurement shifts Lockheed, RTX, and Northrop from premium programs to margin-managed components—while Rheinmetall/BAE/Leonardo take the production leverage
Verified reporting shows the EU’s procurement push is turning “access to platforms” into “access to local sustainment and co-production capacity,” starting with missiles and air-defense spares. For US primes, the margin risk is not losing the customer—it’s winning fewer high-margin builds and more tightly specified work that requires licenses, local partners, and sustainment-heavy economics.
Lockheed Martin’s Missile Ramping Isn’t a One-Off: The 2026 Guidance Lift Implies the Restock Cycle Is Turning Into a Multi-Quarter Revenue Engine
When Lockheed Martin and RTX raised 2026 targets on missile restocking momentum, it marked the first earnings-confirmed “build more, faster” signal for U.S. primes. The key investor question is whether 2026 is pull-forward—or the start of a durable production-and-delivery cadence where the primes become the steepest part of the defense curve.
Oracle’s $7B Pentagon software consolidation win reframes its defense business from “AI megacampus drain” to durable on-prem cashflow
The Pentagon’s nearly $7B, up-to-10-year contract with Oracle is less about frontier AI and more about consolidating sprawling on‑prem enterprise software—plus maintenance and consulting—into a single procurement path. That changes how investors should think about Oracle’s defense exposure: from “spend-heavy AI buildout risk” to a repeatable, subscription-and-license-style government revenue stream tied to IT standardization.
2026-07-23
Atoms’ $1.7B round is the robotics world’s bet on “robot-as-a-service,” not robot-as-a product—at least in how it will be financed
Travis Kalanick’s private robotics venture Atoms raised a $1.7B round led by Uber‑adjacent capital and Bain Capital‑style growth/venture investors, positioning its “digitize the physical world” stack around specialized robots with productive jobs. The financing size and the company’s “software-like” orchestration language point to a shift: customers may increasingly buy outcomes and deployment capacity, while investors fund fleet-like rollouts before unit economics are proven.
Tesla’s “SpaceX merger” narrative is really a margin map: who captures value first is inferable from Tesla’s capex mix—and SMCI’s order-driven margin guidance
The Tesla–SpaceX merger chatter sounds like a corporate-finance story, but the investable question is operational: which link in the shared stack monetizes first—launch cadence, defense compute, compute/data-center builds, or vehicle manufacturing spillovers. In public data, Tesla is signaling multi-billion AI+manufacturing capex intensity, while SMCI—positioned upstream in AI server supply—reported a >$60B new-orders quarter and simultaneously guided margins materially up to a 15%–17% range (via its disclosed update after the SpaceX-linked announcement), turning the “valuation” debate into a supply-chain throughput bet.
Tesla’s “SpaceX merger” is a capex-and-margin value-capture map—2026 capex guidance shows where integration would likely re-anchor multiples
If Tesla–SpaceX integration ever becomes “real,” the value will likely shift based on capex timing: Tesla is already guiding to $20B+ of 2026 capex tied to AI compute and manufacturing/R&D ramps, while its Automotive and Energy segments show materially different gross-margin profiles (17.8% vs. 29.8% in FY2025). The merger narrative therefore matters less for probability and more for what it changes in Tesla’s capex mix and the resulting Automotive-vs-Energy margin pathway.
2026-07-22
2026-07-19

SpaceX's Pentagon AI Deal Turns Defense Compute Into a New Cloud Test
The Pentagon is reportedly considering a multibillion-dollar compute deal with SpaceX, which means defense AI is no longer just about models and chips. It is about who can deliver cheap, secure, and scalable data-center capacity without depending only on the usual cloud giants.
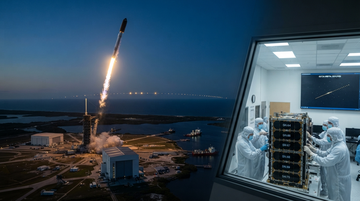
SpaceX's 21-Satellite Military Launch Shows Cadence Is the Real Space Moat
A successful Falcon 9 launch of 21 military satellites is less about the one rocket and more about cadence. Once the constellation reaches 63 of 126 planned satellites, launch reliability starts to matter as a recurring cash-flow engine for SpaceX, Lockheed Martin, Northrop Grumman, and the rest of the defense stack.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.