Aerospace, Defense & Space
Defense budgets and the contractors behind them
Procurement rounds, backlogs, launch cadence and rearmament programmes, read as multi-year revenue with the primes and suppliers named.
2026-08-14

Steam- and hydraulic-driven catapult changes could flip aircraft-carrier electronics content—rewarding legacy electromechanical supply chains while pressuring modern shipboard-electronics primes
A new White House directive orders the Navy to replace EMALS and advanced weapons elevators with steam and hydraulic systems for future CVN-81. That reverses the shipboard electronics content mix: it shifts value from modern electromechanical-and-software-heavy launch/recovery subsystems toward legacy electromechanical/hydraulic supply chains, while also introducing schedule and cost risk for carrier programs near industrial capacity limits.
Pentagon’s SM-3 “restock” plan is now a factory-capacity bet (Boeing & RTX)
Framework agreements signed by the U.S. Pentagon with Boeing and RTX aim to scale the production of specific SM-3 interceptor components—not place a simple new missile order—shifting the restock story to a bottleneck question. The near-term market takeaway: component-output ramp capability at primes and propulsion/rocket-supply partners matters as much as the headline procurement numbers.
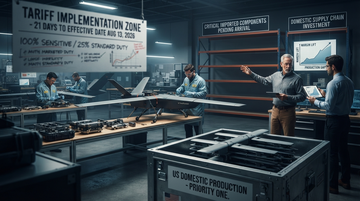
Drone tariffs can lift U.S. drone margins fast—but they cannot replace the Pentagon’s missing production capacity
Trump’s Aug. 13, 2026 drone-tariff package raises duties on imported drones (including 100% on “particularly sensitive” platforms, 25% on smaller drones, and 15% on covered allied countries) starting 21 days after signing. The immediate market read-through for UMAC, RCAT, ONDS, AVAV, and KTOS is a short-cycle pricing and sourcing repricing, not a volume solution. The Pentagon’s own assessment of a years-long U.S. industrial-output gap means tariffs are a margin catalyst, while capacity still depends on procurement programs and industrial base investment.
2026-08-13
2026-08-12
Astronics proved the defense restock can run through aerospace-electrical suppliers—Q2 backlog math now backs a higher FY26 revenue runway
In Q2 FY2026, Astronics reported record sales of $260.0M (+27.0% y/y) and lifted FY2026 revenue guidance to $1.02B–$1.04B (midpoint ~$1.03B). The key tell isn’t just the beat; it’s that bookings (book-to-bill 1.18) and segment backlog expansion are already concentrated in its Aerospace and Test Systems businesses, implying demand is reaching the supply tier—not stopping at the primes.
Joby's $500M defense acquisition reframes eVTOL economics: air-taxi won’t pay yet, but defense cargo might fund the next version
Joby is paying about $500M to acquire Resonant Sciences, a defense-technology business, positioning its eVTOL platform for military-relevant payload and manufacturing pathways. The key investor question becomes whether defense revenue is scalable enough to offset years of air-taxi dilution and losses—something the deal terms and Joby’s cash burn make measurable.
United States Antimony just reset antimony pricing—and the stock is telling you who still gets paid at policy-linked levels
In its Q2 2026 reporting, United States Antimony disclosed a ~52% drop in average antimony selling prices to $13.70/lb and linked the reset directly to weaker spot pricing, cutting its full-year 2026 gross revenue guidance range. The key investor takeaway is not the commodity headline—it’s that the US mineral “policy premium” for the retail trade can vanish overnight when the embedded pricing formula reverts, creating a buyer/dislocation risk across the downstream defense/flame-retardant demand chain.
2026-08-11
Hanwha’s $1.05B–$1.2B bid for Austal’s U.S. shipbuilding arm turns allied capital into a capacity lever
Hanwha Defense USA has made a preliminary, non-binding offer for Austal’s U.S. entities and operations valued at $1.05B–$1.2B (cash- and debt-free), and the next test is whether Korean execution can lift U.S. naval shipbuilding throughput without slowing qualification. For investors, the deal is less about “who builds ships” and more about whether allied ownership can compress the schedule-and-supply bottlenecks that have historically capped output.
IonQ and ARLIS Are Building the DoD’s First Networked “Blind” Quantum System—Turning Quantum From Demos Into Deployable Mission Capability
IonQ’s newly awarded ARLIS contract is a meaningful step from “quantum access” toward a deployable, multi-node “blind quantum computing” system for national-security research. The investor implication is not just a government check—it’s whether quantum vendors can operationalize networked quantum with the security, control, and integration stack the Pentagon will repeatedly fund.
The SEC is finally policing the private secondary market — and its first big “compliance date” is attached to SpaceX and Klarna
A new SEC litigation release shows the agency is treating certain pre-IPO secondary trading intermediations as securities-fraud and investment-adviser compliance failures, citing misconduct tied to both Space Exploration Technologies Corp. (SpaceX) and Klarna Group plc. For investors and platforms that rely on “private-market access,” the key shift is that enforcement risk is moving upstream—from after-IPO disclosures to the mechanics of how pre-IPO shares are sourced, priced, and moved.
2026-08-10
Archer just bought Boeing’s autonomous-air-taxi stack for ~19.75% equity—turning eVTOL consolidation into a flight-certification supply story
Archer Aviation’s planned all-equity purchase of Boeing’s [Wisk Aero], [SkyGrid], and [Insitu] subsidiaries gives Boeing an ~19.75% stake plus $200M of option-like warrants—effectively bundling a certification-and-operations pathway into Archer’s capital plan. The deal reframes “autonomous air taxi” from a software thesis into an integrated, Boeing-adjacent supplier of flight, sensing, and airspace integration assets.
Fisher’s AI-Infrastructure Crowding Trade Is Real—But It’s the “Grid-to-Aircraft-to-Network” Link That Should Matter for Investors
Fisher Asset Management’s latest 13F (quarter ended June 30, 2026) shows aggressive positioning across AI’s “real economy” buildout—power and electrification via GE Vernova, aerospace platforms via GE Aerospace, and enterprise/data-center connectivity via Cisco Systems, alongside the usual AI compute core. The investable takeaway is not that AI exists—it’s that Fisher is paying up for the bottlenecks and replacement cycles that sit between AI demand and the supply chain that fulfills it.
Rocket Lab's margin signal is a satellite-mix test: Q2 gross margin rose to 36.1% even as space-systems revenue shifted
In Rocket Lab's latest quarterly filing, Space Systems delivered most revenue ( $189.5M of $234.1M total) while Launch Services shrank, yet consolidated gross margin still rose to 36.1% from 32.1% a year earlier. The investment question isn’t whether satellite sales are growing—it’s whether Rocket Lab can keep space-service unit economics from resetting margins downward when lower-profit satellite-heavy revenue mix shows up in quarterly results.
SpaceX’s First Retail Sell Turns the Mega‑IPO Regime Signal: When Mom‑and‑Pop Becomes a Source, Liquidity Stops Being One‑Way
SpaceX saw its first net retail selling in the post‑IPO era when mom‑and‑pop traders sold a net $4.5M of shares on Aug. 7, 2026 (first negative reading since the June IPO). That matters because the next wave of tradable supply is already scheduled via lockup expiries—starting with a major tranche eligible around Aug. 20—so sentiment can now amplify supply rather than absorb it.
2026-08-09

Sila’s $1.4B OSC conditional loan turns silicon-anode industrial policy into a direct, materials-led Pentagon procurement lever
On Aug 7, 2026 the U.S. Office of Strategic Capital (OSC) announced a $1.4B conditional loan commitment to Sila Nanotechnologies tied to expanding silicon‑carbon (Si/C) anode production and building lithium‑ion cell capacity. The strategic signal is that DoD/OSC is funding the next energy-storage stack at the materials bottleneck—before cells and primes—so investors should map winners to silicon-anode scaling, electrolyte/lithium refining, and US cell manufacturing.
The DFC’s $3B minerals push is less about “materials” and more about buying 2027–2028 capacity blocks—MP Materials, USA Rare Earth, Energy Fuels, and Lithium Americas are the clearest US order-book fits
A verified Aug 7, 2026 package around critical minerals financing links to defense supply-chain bottlenecks, but the publicly accessible primary materials we can confirm name only a partial set of project participants. Using that confirmed deal/map plus listed-company capacity economics, the clearest “funding-to-offtake” winners are the US incumbents that can plausibly monetize demand under a 2027–2028 commissioning window—MP Materials, USA Rare Earth, Energy Fuels, and Lithium Americas—while the defense OEM names (e.g., Lockheed Martin and RTX) mainly matter as anchor buyers of qualifying downstream output.
Ukraine’s drone strike on Russian refineries shifts the diesel story from “Iran/Hormuz risk” to hard supply destruction
By hitting two Russian refineries in a coordinated drone attack, Ukraine has targeted the part of the system that converts crude into diesel—tightening product availability and strengthening diesel crack spreads through lost runs. For refiners with product-heavy exposure, the investment implication is not just “war risk premium,” but whether incremental outages persist long enough to translate into sustained margins.
2026-08-08
Hadrian’s $1.37B at a ~$7.87B valuation signals defense manufacturing is the new capital magnet—and it pressures software-multiple investors that can’t show factory throughput
Hadrian (private) raised $1.37B at a $7.87B valuation to scale “factories-as-a-service,” with explicit capacity moves for munitions, shipbuilding, and submarine-component production. For listed defense primes, the real test is whether new factory capacity can convert into deliverable, margin-protecting production schedules—while “autonomy-only” winners face longer cash-conversion paths.
DFC’s $3B minerals bet turns “China decoupling” into a processing-margin race—and the winners are the firms that can monetize working capital first
The U.S. Development Finance Corporation (DFC) has outlined a $3B set of domestic critical-minerals deployments, including a prominently cited $58M-financed component, aimed at strengthening defense-adjacent supply chains. For investors, the key shift is not “more mining,” but which listed processors can pull forward separation/refining timelines—because DFC-style financing changes capex sequencing and who captures the processing margin.

Judge Halts DoD’s WuXi “Chinese Military Company” Label—But BIOSECURE’s Clock Can Re-Start Differently
A U.S. judge preliminarily enjoined the Pentagon from enforcing its June 2026 Section 1260H “Chinese military company” designation for WuXi AppTec, blocking the immediate BIOSECURE reactivation path tied to that label. For investors, the key question is not whether the BIOSECURE restriction exists, but how CROs and US biotechs must re-route procurement after the compliance trigger is legally paused.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.