Aerospace, Defense & Space
Defense budgets and the contractors behind them
Procurement rounds, backlogs, launch cadence and rearmament programmes, read as multi-year revenue with the primes and suppliers named.
2026-09-02

SiriusXM’s “overlooked” pivot isn’t about dying satellite—it's about rebuilding distribution through ad-tier in-car access
Deutsche Bank’s bull case argument (as it’s been described publicly) hinges on SiriusXM’s transition from a largely closed, satellite-driven subscriber base toward an ad-tier, in-car-first listening model. The risk to that transition is timing: in-car audio can be disrupted quickly by connectivity and app-native listening, and SiriusXM’s own filings show that connected-vehicle services are tracked separately from its satellite subscriber math.
Grok 4.7’s SpaceX-data bet creates a rare “physical-engineering” moat—if it survives ITAR and deployment
Reporting on Elon Musk’s internal rollout points to xAI training Grok 4.7 on SpaceX engineering and employee information, positioning the next frontier run around proprietary “real-world build” knowledge rather than only web-scale text. For investors in AI infrastructure and accelerators, the key question is whether that data advantage can translate into durable model behavior and paid demand—before competitors close the gap.
2026-09-01
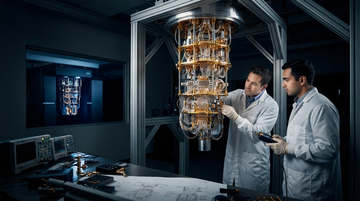
IBM’s Aug 26 close of HRL Laboratories turns “defense-relevant” quantum sensing into an owned capability—not just a partnership
IBM closed its acquisition of HRL Laboratories on Aug. 26, 2026, taking control of a private R&D lab jointly owned by Boeing and General Motors and focused on quantum computing and quantum sensing. The deal matters to investors because it bundles quantum hardware stack elements (including cryogenics, control electronics, packaging) that are prerequisites for turning lab-grade sensors into scalable, sovereign-capable defense-adjacent systems.
The Pentagon is productizing sovereign frontier AI—its own GenAI.mil rollout now lets soldiers chat with ChatGPT and Grok, and the winners may be the platforms that control access more than the labs that invent models
GenAI.mil is moving from pilots to a standardized enterprise portal that grants U.S. personnel access to frontier models, including OpenAI’s ChatGPT and xAI’s Grok, within defined impact-level controls. The decisive constraint is not model quality alone; it’s the Pentagon’s 30-day “public release” deployment cadence and the data-release governance that can either widen or lock down which providers get integrated fastest.
2026-08-31
Offerpad’s Nasdaq relisting is a “housing bottom” test for iBuyers: Q2 liquidity economics show Cash Offer can scale—but still needs a rate-friendly resale window
Offerpad’s OPAD transfer to Nasdaq on Aug. 31, 2026 is not an iBuyer comeback by itself, but it gives the market a fresh price discovery moment for whether instant-cash offers can sustain margins in a still-stiff mortgage-rate environment. In its latest reported quarter, Cash Offer generated most of revenue while the company’s overall gross profit stayed thin and operating cash flow swung negative—so the iBuyer model’s next phase depends more on resale velocity than on the “cash” headline.
SAIC’s pre-market print can’t yet prove “federal AI” is cashing into margin—its latest filings still show a services-heavy earnings engine
SAIC is set to report its next pre-market quarter on Aug. 31, 2026, but the core investor question—whether federal-AI/software budgets are converting into backlog and higher-margin billable capacity—cannot be validated from the sources available so far. What the latest publicly accessible financials do support is that SAIC’s earnings engine remains consistent with large-scale services delivery rather than a fast shift to higher-margin software economics.
2026-08-30
The F-15’s $131B tailwind meets a titanium/forging bottleneck—where aerospace money actually gets minted
Boeing’s Aug. 2026 F-15 “Eagle Crest” contract ceiling ($131.23B) confirms long-duration defense demand, but the metal path from order to delivery still depends on titanium melting, billet/press forging, and specialty-alloy throughput. ATI’s March 2024 commissioning of a 12,500-ton billet forging press and Howmet’s titanium-integration strategy show how primes can’t “pull forward” metal chemistry—so the bottleneck shifts value to specialty-material and forging capacity owners.

US–Canada tariff walls are turning magnesium, gallium and germanium into a hidden factory-cost fight—autos, chips and aerospace are the transmission lanes
Canada’s retaliatory tariff schedule effective Sep 8, 2026 creates a direct cost wedge on U.S.-origin tariff lines tied to critical minerals—including magnesium content at the “99.8% by weight” threshold. The bigger market risk is not headline metals—it’s which U.S. industries consume those mineral inputs through alloys, optical/semiconductor processing and defense/aerospace components, and whether North American resourcing can replace China-linked supply quickly enough.
A “World Bank for defense” pitch could shift backlog risk into a loan book—if DSRB really can turn €5B of paid-in capital into a $116B lending pipeline
The Defence, Security and Resilience Bank (DSRB) is aiming to raise $116B of lending capacity backed by roughly €5B of upfront paid-in commitments, according to Reuters. If it launches on a low-cost, long-dated basis in 2027, the structure would change how prime contractors and their supplier base finance production ramp-ups—potentially easing working-capital pressure from defense backlogs while intensifying competition versus defense-focused private credit.
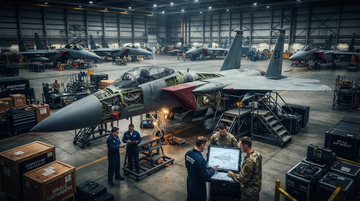
Boeing’s $131.23B F-15 Eagle Crest sole-source ceiling turns “sustainment first” into a margin-rights fight
The U.S. Air Force awarded Boeing a $131.23B ceiling, sole-source IDIQ for F-15 production, modernization, and sustainment—explicitly including a move toward “organic depot maintenance” for heavy overhauls. For Boeing, that bundle shifts the defense margin bet from new-aircraft cadence to long-duration, fixed-ish sustainment deliverables—while Right-to-Repair policy pressure threatens the lock-in economics that sustainment incumbents often assume.
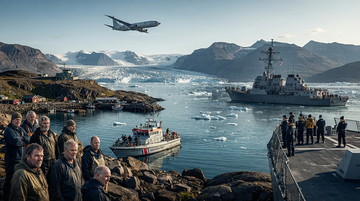
Iceland’s EU “no” breaks the only slow-moving anchor—Arctic policy now tilts toward power, patrol capacity, and extractive leverage
Iceland rejected restarting EU accession talks by 52.8% to 47.2% in a late-August referendum that opponents framed around sovereignty risks. With the US pressing Greenland through “national security” arguments and NATO simultaneously tightening Arctic posture, the Arctic is shifting from diplomacy-by-institutions toward competition by presence—raising the premium on surveillance, ice-capable lift, and defense supply chains.
2026-08-29
Amaero’s S-1 arrives in a moment when investors don’t just question defense backlog—they question whether “factory capacity” can actually scale
Amaero AMROF is positioning its hypersonics-linked manufacturing chain around domestic, powder-to-near-net-shape production—an angle that directly targets the same execution worry that showed up in the recently pressured defense-IPOs theme. But its fundamentals still look like a pre-scale industrial builder: losses persist and free cash flow remains deeply negative, so the market will likely pay for credible capacity ramp, not just contracts.
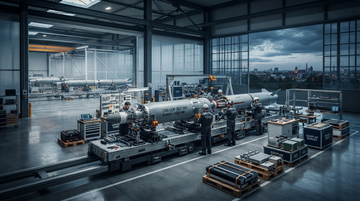
Covenant’s planned Leipzig missile plant turns Europe from “buy-local pain” into “localized build,” and it matters most for the primes that can scale production fast
Reuters reports Covenant plans to start producing intermediate-range missiles near Leipzig from 2027, with potential capacity up to 1,000 units a year and ranges over 1,500 km. That shifts part of Europe’s rearmament spend from importing into local procurement to local manufacturing—changing the margin and capacity story for U.S. and European missile primes, while tightening the supply-chain bottleneck around motors, seekers, and precision production.
CXMT’s 1260H lawsuit turns a policy label into a DRAM pricing question
CXMT’s suit challenges the Pentagon’s “Chinese military company” designation that can trigger U.S. procurement restrictions under Section 1260H. The key investor takeaway is whether courts keep narrowing designation power—making it harder to wall off capital from China’s DRAM buildout—and therefore shifting the balance of risk across Micron, SK hynix, and Samsung Electronics.
Ukraine’s EU loan ratification turns European rearmament into a debt-backed demand floor — and forces margin math for US primes’ Europe backlogs
Ukraine’s ratification process clears the way for the EU’s €90B Ukraine support loan framework for 2026–2027, with the package explicitly tied to urgent budgetary and defence industrial capacity needs. For defense suppliers, the shift from grant-like support to sovereign-debt-financed procurement increases the probability of sustained multi-year ordering even when national budgets tighten — but it also raises the odds of a tighter pricing spread and margin share for US prime contractors competing for the newly financed European work.
2026-08-28
Anthropic’s courtroom win against the Pentagon’s “supply chain risk” blacklist redraws the rules for AI procurement—then the next fight moves to contracts
On Aug. 27, U.S. District Judge [Rita Lin] ordered the Pentagon’s “supply chain risk” designation against [Anthropic] blocked, finding the measure likely violated the First Amendment and due process. The practical outcome is bigger than one vendor: it constrains how DoD can de facto exclude frontier AI providers from defense work using national-security framing—shifting procurement leverage toward evidence-backed contracting decisions and away from broad, pretextual blacklists.
Pasqal’s Nasdaq debut turns “quantum second wave” into a cash-and-capex test
Pasqal’s Nasdaq go-public deal with Bleichroeder values the neutral-atom pure-play at a roughly $2.0B pre-money with ~$500M gross proceeds to the company, giving the market a concrete pricing benchmark for deep-tech hardware beyond the AI complex. Using IonQ’s reported cash burn and revenue scale as a yardstick, the question for investors is less “who wins quantum,” and more whether Pasqal can turn a cash runway into commercialization that outgrows burn before the public-market IPO window tightens further.
Rocket Lab's COO sold into the space rally—and the bigger tell is why it likely wasn’t a “no” on Neutron
Rocket Lab’s COO, Frank Klein, sold 45,692 shares for about $3.18M on Aug. 26, 2026, according to his Form 4. While insider selling can be a red flag at valuation extremes, Rocket Lab’s own filings show Neutron’s targeted first launch remains in Q4 2026—suggesting the trade fits a tax/plan-driven pattern more than a fundamental vote of no confidence.
2026-08-26
New Nasdaq ETF TGRZ lets US investors bet on China LLMs—without fixing the core decoupling math
When TGRZ begins trading on Nasdaq, it packages exposure to China’s large-language-model ecosystem into a single listed wrapper. The opportunity is real, but investors should model two frictions at once: export-control gating that can cap addressable demand, and single-country, single-theme concentration that makes valuation and liquidity risks hit the whole basket together.
HEICO proves aerospace aftermarket is where profits accumulate (Q3 FY2026 net income +33%)
In HEICO’s third quarter of fiscal 2026, record sales and net income rose 33% to a record $235.4M, outperforming the OEM build-rate narrative. The quarter reinforces why aerospace aftermarket—replacement parts supply and repair/overhaul—can monetize fleet utilization even when OEM delivery timelines slip.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.