AI & Software
Where AI spending is actually landing
Model releases, enterprise adoption and software margins, read for what they do to revenue — across the labs, the platforms and the software they run on.
2026-09-04

Microsoft's Foundry channel turns OpenAI GPT-6 Astra into the enterprise monetization gate—before open access
OpenAI is rolling GPT-6 Astra out first through its Daybreak enterprise program (with ChatGPT tiering and API access following), while Microsoft promotes how OpenAI models are sold through Microsoft Foundry under Azure’s enterprise distribution mechanics. The tradeoff is clear: scarcity is being used to secure higher-trust buyers and tighter deployment controls—setting up Microsoft to capture more “resale-style” AI revenue economics per seat and per inference rather than waiting for universal open APIs.
Salesforce Just Invested in Its Own Disruption: Wonderful's $5B Round Prices Enterprise AI Agents as Distribution
Wonderful closed $550M at a $5B valuation on Sept 2, 2026 —2.5x its $2B mark from six months earlier — on roughly $70M of current ARR (~$100M by year-end). Salesforce, owner of the competing Agentforce platform, joined Insight Partners and Index in the round. The implied ~50x forward ARR multiple puts Wonderful between Sierra's ~79x and Glean's ~24x and shows that mid-tier enterprise agents are no longer being valued like software but like customer-service distribution: per-minute cost economics, forward-deployed engineering pods, and multilingual voice agents that slot in next to — and increasingly behind — incumbents like Salesforce, ServiceNow, Cognizant, and Accenture.
2026-09-03
Adobe’s real CEO question: can Experience-led AI marketing replace Creative Cloud as the monetization center?
Adobe has not confirmed a “Sept. 3 CEO hands-off to the Experience chief” transition. What is confirmed is CEO Shantanu Narayen’s earlier decision to transition after a successor is named, while Adobe simultaneously pushes monetization levers in agentic customer experience—signaling that the next CEO will be judged on turning AI orchestration into repeatable revenue beyond Creative Cloud.
Adobe buys “agentic marketing” know-how via Rilo—and tries to turn marketing data into a distribution advantage
Adobe’s acquisition of India-based marketing intelligence startup Rilo is being structured as an IP-and-team purchase, with Rilo’s product shutting down and its users moving to Adobe. The strategic read-through: Adobe is shifting marketing AI from “model access” toward owned intelligence inputs that can improve how its in-app agents plan, target, and execute go-to-market actions.
Anthropic’s September release blitz is IPO choreography—its October $2T pitch hinges on sustaining agent economics (not just model wins)
Anthropic’s Sept. 1–2 product cadence—Claude Fable 5.1’s 75% cache-read cost drop, Claude Mythos 5.1’s gated access programs, and Enterprise Frontier Safeguards’ “no Anthropic human review” enterprise privacy controls—reads like a playbook to keep unit economics improving while expanding enterprise conversion ahead of an October 2026 IPO pitch around a ~$2T valuation. The market test isn’t whether the launches are impressive; it’s whether the pricing and governance features can hold gross margin through scale, and whether gating plus privacy become a durable switching-cost wedge.
Apple’s outside AI chief signals a pivot away from “Siri-first” toward a partner-licensed AI playbook
Apple’s new external AI leadership—taking over after John Giannandrea’s retirement—arrives as Apple simultaneously prepares for the Sept. 1 CEO handoff and trims Siri/Vision Pro staffing. For investors, the bigger read-through isn’t organization churn: it’s that Apple is likely to lean harder on licensed and partner-managed AI capabilities, which changes the economics and leverage in the OpenAI-style standoff and reframes how Apple can grow “on-device” AI without bearing every model-cost itself.
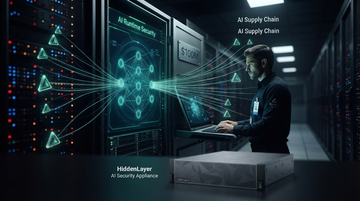
HiddenLayer’s $100M round signals “secure the AI model” is becoming a standalone enterprise budget line
HiddenLayer’s $100M Series B (Sept. 2, 2026) is less about another AI-security feature and more about funding a new spend category: protecting AI models and agentic runtimes with EDR-like expectations. The strategic risk for incumbents is that legacy endpoint identity security can’t absorb the AI-specific shift fast enough—while the opportunity is real but still unclear who will win the enterprise “agent runtime” layer.
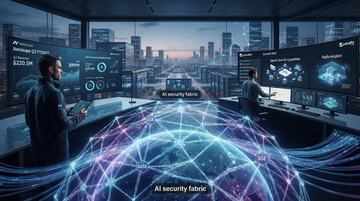
Netskope turns SASE/SSE into an “AI security fabric” narrative — but the signal is also a stress test for whether Palo Alto’s AI-cyber re-rating is truly category-wide
Netskope’s Sept. 2 after-hours update positioned cloud-delivered security (SASE/SSE) as an “essential, adaptive fabric” for safe AI adoption, alongside double-digit growth in Q2 FY2027 revenue and a lifted full-year outlook. The key investor question is whether this helps validate Palo Alto Networks’ AI-cyber platformization story (including the Console deal) as broad demand—or whether the trade remains dominated by a small set of platform vendors.
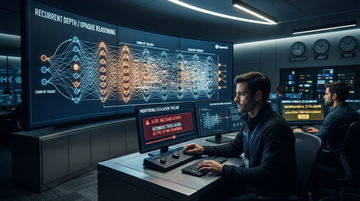
OpenAI’s “recurrent depth” raises a grim question: will its own Critical Cyber monitors have fewer things to watch?
OpenAI said its Astra model could not be ruled out as “Critical cybersecurity capability,” and it has responded with stricter controls plus boundary monitoring that can pause risky activity within about 30 minutes. On Sept. 2, reporting surfaced OpenAI’s “recurrent depth” reasoning technique—an approach that safety experts say can reduce monitorable chain-of-thought signals. The investor risk is timing: each new capability milestone that makes models harder to interpret can also make the lab’s gating regime slower and more expensive, shifting product release—and IPO/scale narratives—away from the lab’s technical roadmap.
Palo Alto Networks just paid ~$500M to “agentify” security—investors should benchmark the move against identity-agent deals like Okta’s Permiso
Palo Alto Networks announced it has acquired Console to deepen agentic capabilities in its Cortex platform, positioning the product as a “software-as-an-agent” layer over security operations. The strategic message is clear: the market is now pricing agentic security as an attachable platform module, and the $500M-scale entry ticket (as reported by multiple outlets) sets a high bar for revenue conversion versus smaller, identity-centered AI-agent deals.
Samsara’s Q2 FY2027 print is the “fleet AI” stress test—whether software monetizes at the asset layer, not the rack
Samsara scheduled its Q2 FY2027 financial release for Sept. 3, 2026 (quarter ended Aug. 1, 2026), positioning the company as a clean read-through of whether “physical AI” can convert into measurable, recurring revenue. The current evidence available in primary sources during this run confirms only the release timing—not the results—so the AI-monetization conclusion below is framed as what investors must verify in the forthcoming print.
Thinking Machines just got a $40B pricing signal—making “small, capital-light AI” compete with frontier-lab multiples
Accell reportedly is in talks to lead a roughly $1B round that would value Thinking Machines at about $40B (reported Sept 3, 2026). The repricing matters because it suggests investors are underwriting not just model size, but platform credibility—forcing the “small AI, high-ROI” thesis to clear a frontier-lab valuation ladder as the IPO window approaches.
Uber's 10% layoff reframes robotaxi as an opex battle—while challenging how much of the human-driver gig base survives
Uber is cutting about 3,300 roles (~10% of headcount) in its biggest layoffs since COVID, explicitly amid the robotaxi competitive shift. The parts of Uber that get trimmed matter more than the headline number: if the company flattens management while protecting operations, the human-driver cost base stays intact; if it reorganizes support around AV operations, the transition economics will pull future costs away from riders and toward “AV-operator” capacity.
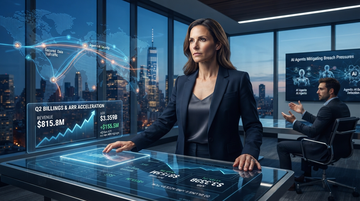
Zscaler’s beat-and-raise landed in billings—not “agentic hype”: the SSE-to-AI-security demand signal investors can measure
Zscaler’s Q2 results (reported for the quarter ended Jan. 31, 2026) show a strong ARR and deferred-revenue trend alongside an increase in reported revenue, which is the closest public proxy investors have for billings conversion. The company also formalized its “agentic AI security” push via leadership and partner signals—supporting the thesis that AI-driven breach pressure is translating into measurable, recurring security demand (rather than only demos).
2026-09-02
AfterQuery’s $3.2B in record time highlights a private-market “pricing acceleration” for the AI agent data layer
AfterQuery was reported to become Y Combinator’s fastest-ever unicorn at a $3.2B valuation after raising $30M at a $300M valuation just months earlier—an extreme speed-to-valuation move concentrated in the AI agent ecosystem. The implication for public markets: when private buyers pay for agent supply-chain readiness this fast, it can pull forward software multiples for companies that can monetize “agent-ready” data, evaluation, and workflow integration.
Anthropic’s Fable 5.1 pivot: cheaper pricing plus a wider “unrestricted” path—at the exact moment OpenAI gates Astra over “Critical” cyber capability
Anthropic rolled out Claude Fable 5.1 on Sept. 1, 2026 as an “unrestricted version,” pairing a lower effective cost with tighter false-positive controls and fewer enterprise friction points for everyday workloads. That move runs opposite OpenAI’s Aug. 7 update on Astra, where OpenAI said it “cannot rule out Critical cyber capabilities” and paused parts of Astra work while strengthening controls. For investors, the mismatch signals a profit pool shift toward higher utilization: when safety-friction is reduced without removing monitoring, pricing becomes the lever that changes enterprise adoption and inference economics faster than model benchmarking.
Broadcom beat-and-fell: the weak guide turned the custom-silicon backlog “test” negative for AI racks
Broadcom’s Q3 FY2026 results showed AI acceleration, but management’s next-quarter AI revenue guide did not provide the backlog-to-revenue “conversion proof” investors wanted. With AI semiconductor revenue guided to $21.7B for Q4 (+236% YoY), the market still sold Broadcom—signaling that the real debate is whether AI custom silicon is arriving on schedule for hyperscaler racks, not whether AI demand exists.
GitLab just sold “security-anchored AI seats” with its Aug. 28 model shifts—here’s the pricing test that matters
GitLab used its Sept. 1 after-hours Q2 FY2027 print to tie AI value to security, context, and governance—and paired it with a new packaging model (GitLab Flex) that’s designed to keep seats monetizable as AI capabilities roll out. The market question is whether that works as AI model-layer discounts and “codegen commoditization” intensify; the answer in this quarter is less about headline revenue growth and more about how fast bookings and retention are converting into durable subscription economics.
Microsoft starts making Azure quarterly revenue comparable—turning “cloud growth” into an auditable line investors can model
Microsoft’s latest reporting changes begin separating Azure’s cloud economics from the broader Intelligent Cloud bucket in a way that lets investors track quarterly Azure growth directly (instead of inferring it through a blended segment). The shift matters most for AI cloud economics: it clarifies how much incremental demand is converting into measurable Azure revenue, and it changes how the market will price Microsoft’s capex-heavy AI buildout.
MongoDB's Sept. 1 print is the first test of whether AI spend monetizes at the application-data layer (or stalls at the rack)
MongoDB will report Q2 FY2027 results for the three months ended July 31, 2026 after markets close on Sept. 1, with guidance baked into the event materials: total revenue of $771.8M (+30% YoY) and Atlas revenue up ~29% YoY. The investor question is whether the AI buildout pushes usage deeper into the database/data plane (vector + workload intensity), translating into durable Atlas expansion—or whether demand concentrates in accelerators and infrastructure.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.