AI & Software
Where AI spending is actually landing
Model releases, enterprise adoption and software margins, read for what they do to revenue — across the labs, the platforms and the software they run on.
2026-08-22

OpenAI’s GPT-5.6 Sol gets a flagship 20%+ developer discount—an IPO-timed move that shifts the AI profit pool into “frontier” usage
On Aug. 21, 2026, OpenAI cut GPT-5.6 Sol developer API and credit pricing by more than 20% for the next three months, dropping standard short-context rates from $5/$30 per 1M tokens to $4/$20. Because GPT-5.6 Terra and GPT-5.6 Luna saw cuts earlier, this is the first time OpenAI time-boxed the actual flagship—suggesting a deliberate push for developer mindshare ahead of Anthropic IPO pricing discussions.
Salesforce is trying to prove Agentforce spend becomes software revenue—its FY27 guide pins the answer to the subscription line
IBM’s latest filing frames a customer spending shift: AI pushes buyers toward servers, storage, and memory, and that timing mismatch drags software deal flow. Salesforce’s counter-test is more specific: it has reorganized revenue reporting around Agentforce Apps and Data 360/Headless and is guiding double‑digit FY27 subscription growth plus stable operating margin. The real question for investors is whether AI monetization lifts recurring billings through the software P&L—or whether it mainly funds infrastructure costs that don’t show up as seats.
2026-08-21
AI debt “fatigue” is becoming the demand-side brake on the capex supercycle
A wave of AI-linked corporate borrowing is colliding with buyer constraints in US credit, with larger investors demanding materially better terms to absorb record issuance. For hyperscalers, the near-term risk is not just higher coupons, but a narrower pool of repeat buyers—turning refinancing timing and leverage capacity into the next binding constraint on AI infrastructure funding.
AI-Authorship Is Reaching a Tipping Point: How the Web’s “Training Flywheel” Turns Into a Quality Problem (and a New Ad-Truth Play)
A Pew Research Center study finds AI-authorship signals in over one-third of newly published pages—evidence that the training-data supply is increasingly self-contaminating. The investment angle is not just “more AI text,” but how that content-mix pressures search/ad economics, raises the cost of higher-quality training data, and pulls value toward watermarking, provenance, and rights-clearing.
Anthropic’s $11.5B Q2 revenue puts the $74B ARR narrative on trial—so what will the IPO actually price: growth or “run-rate”?
Anthropic is now showing a hard quarterly revenue line of over $11.5B, but the valuation debate hinges on whether the much higher “annualized run-rate” claim is durable and how much is true recurring revenue versus timing effects. The answer matters for buyers of Anthropic shares and for the entire AI supply chain, because run-rate-heavy stories tend to monetize compute, not just software.
ChatGPT’s iMessage plug-in “dials-in” Apple’s distribution moat—while Apple’s injunction fight is still in the risk bind
OpenAI’s new Apple Messages plug-in lets ChatGPT read, search, draft, and—after user approval—send texts inside iMessage/SMS/RCS on Apple silicon Macs. That integration underlines why OpenAI cannot fully “bypass Apple” in distribution even as Apple’s trade-secrets injunction effort threatens parts of OpenAI’s hardware pipeline and is flagged as an IPO risk in OpenAI’s public-facing disclosures. The paradox for investors: Apple’s ecosystem becomes both the shortest path to users and the headline legal tail-risk for OpenAI’s licensing, partnerships, and device strategy.
Figma’s public debut isn’t just an IPO—it’s a live audit of whether AI can turn design software into a margin engine
Figma FIG begins public trading on Aug. 20 with investors focused on whether its AI features can monetize fast enough to offset rising compute and product investment. The near-term test is profitability trajectory: recent quarterly results show big swings around operating leverage, so the IPO narrative will rise or fall on AI-driven pricing power rather than user growth alone.
Google’s “Preferred Sources” button turns AI-overview traffic into a measurable publisher asset
Google is giving publishers an embedded, reader-click “Preferred Sources” control designed to restore visibility when AI Overviews skim attention from traditional links. For publishers and SEO intermediaries, the key shift is that the winning signal is closer to a consumer preference than to an opaque ranking contest—so content and distribution can be optimized around verifiable reader selections.
Micro1’s $500M gross run-rate shows the AI data middleman is capturing the margin—before the copyright bill hits
Micro1’s reported jump to a ~$500M gross annual run rate highlights how “human-in-the-loop” training-data services can scale to public-company scale. But the copyright-cost floor created by major AI settlements (including Anthropic’s $1.5B approval) implies the training-data supply chain may see margin compression first—starting with the services that sit between data owners and frontier labs.
NVIDIA's Linux/Chromebook GeForce NOW update turns cloud gaming into a recurring, software-like GPU monetization layer
NVIDIA is pushing GeForce NOW onto Linux and Chromebooks with an “out of beta” native Linux app plus a Chromebook “Fast Pass” that bundles a year of service and prioritizes access. The move matters for investors because it targets lower-utilization device segments and can turn existing GeForce-grade GPU capacity into stickier, subscription-style revenue—at the same time that platform walled gardens face higher pressure.
OpenAI’s “AI Futures” launch turns long-horizon safety into an investor-grade program
On Aug. 20, OpenAI introduced its “AI Futures” initiative, framed around reshaping society for transformative AI while centering governance and individual agency. Read alongside Aug. 18’s “pacing model development” cyber argument and the lab’s “Zero Data Retention” enterprise posture, the move signals a tighter, more institutional way of selling long-horizon risk and capex discipline to regulators and future public-market investors.
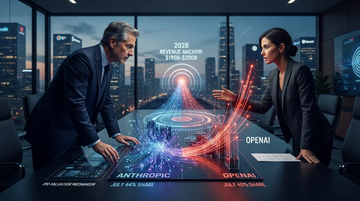
OpenAI’s enterprise bounce is squeezing Anthropic’s IPO math: if July share keeps drifting, $190–$200B 2028 revenue assumptions get harder
Fresh Ramp-based market-share reporting shows OpenAI clawing back enterprise business users from Anthropic in July 2026—without the lead fully flipping back. That matters because Reuters reports the street’s Anthropic IPO valuation is being anchored to a $190–$200B 2028 revenue forecast, making persistence of any share erosion (or re-acceleration) a pricing risk for Anthropic’s IPO.
Ramp’s router move suggests LLM routing is becoming a vertical feature—not a standalone infrastructure moat
Ramp’s new Router product ties model selection to enterprise spend visibility, claiming customer inference-cost reductions of 40% on average and 99.9% production reliability. When paired with Stripe’s plan to acquire OpenRouter for routing optimization across 400+ models, the signal is that “routing intelligence” is shifting from a toll-booth business into table-stakes plumbing that incumbents embed into finance and payments workflows.
Uber’s €825M Dutch fine turns “algorithmic suspensions” into a balance-sheet liability
The Netherlands’ data regulator (AP) fined Uber €825 million for suspending drivers through automated decisions without adequate driver information and safeguards. With Uber’s 2025 revenue at $52.0B, the fine sizes up to ~1.6% of annual revenue—an order of magnitude large enough to change how platform labor-risk is budgeted across Europe and beyond.
2026-08-20
Citi, HSBC and Standard Chartered plug Ant International’s FX-AI into liquidity risk—turning “forecasting” into market plumbing
Three global banks agreed to deploy Ant International’s upgraded FalconTST 2.0 model to manage foreign-exchange liquidity risk, signaling AI is moving from FX desk “assist” tools into the treasury systems that decide how much risk banks can safely carry. The investment implication is less about AI hype and more about who controls the forecasting layer—because that layer directly influences hedging and liquidity cost, and it raises real questions about model governance, data provenance, and regulatory comfort in Western bank workflows.
The CFTC’s Compute-Derivatives Opening Turns GPU Capacity Into a Hedgeable “Pricing Primitive”
The CFTC’s Aug. 19, 2026 request for comment is the first real regulatory nudge toward compute futures—contracts whose value tracks AI computing capacity costs. If compute pricing becomes tradable, it can let hyperscalers, data-center operators, and market makers shift utilization risk from long-dated capex into hedgeable cash flows—changing how investors price the AI buildout.
IonQ turns Q2’s $80.1M revenue into a cash-burn question: the market is paying for DoD cadence + SkyWater build-out, but the filing shows ~50% of RPO converts within 12 months
After IonQ’s Q2 results, valuation debate is shifting from “quantum capability” to whether the revenue base can carry the SkyWater build-out and cash burn. In the June 30, 2026 filing, IonQ reports ~$485M of remaining performance obligations and expects ~50% to be recognized within the next 12 months—making DoD/commercial conversion timing the key swing factor for multiples.
OpenAI’s “zero data retention” is less about compliance—and more about owning the enterprise trust choke-point
OpenAI’s Aug 19 pledge goes beyond “we don’t train on your data” by targeting the other enterprise objection: storage of prompts and outputs for abuse monitoring and human review. But the offer also comes with practical constraints—ZDR applies to eligible API endpoints and changes endpoint behavior—meaning the business win depends on how reliably customers can route real workloads into the ZDR-compatible surface.
2026-08-19
Etched’s $21B jump signals that inference silicon is moving from “experiment” to “economics”—and it pressures Nvidia’s GPU advantage on both cost and capacity
Etched’s Aug. 18 financing valued the company at $21B after a prior $10.3B valuation just weeks earlier—an investor re-rate that coincides with first customer delivery to Jane Street and more than $1B in customer contracts. The market takeaway is not “another chip startup,” but a shift toward dedicated inference hardware that competes with GPUs on two fronts: utilization/cost per token and rack-level capacity to meet urgent decoding demand.
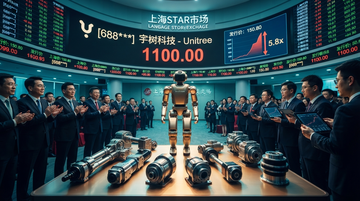
Unitree’s 5x Shanghai debut turns China’s humanoid supply chain into a capital magnet—here’s who captures the first funding windfall
Unitree Robotics (listed as Yushu Technology) debuted on Shanghai’s STAR Market after an IPO priced at 150.8 yuan—then opened at 1,100 yuan, implying a ~5–6x first-day jump versus the offer. The windfall is likely to flow first into the “mechanics layer” (actuators, harmonic reducers, precision sensing) because Unitree’s IPO disclosed near-term R&D and manufacturing-capex use of proceeds—while US-led procurement barriers can redirect Chinese demand into domestic component ecosystems that Tesla Optimus can’t easily bypass.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.