AI & Software
Where AI spending is actually landing
Model releases, enterprise adoption and software margins, read for what they do to revenue — across the labs, the platforms and the software they run on.
2026-08-24

Grok 4.6 appears inside Google’s Model Garden—xAI just bought enterprise distribution from its biggest cloud rival
When Grok 4.6 was made available through Google’s Model Garden on the Gemini Enterprise Agent Platform, xAI gained a direct enterprise on-ramp via Google Cloud without building its own large-scale channel. For buyers, it shifts the leverage from “who owns the cloud deployment” toward “who owns the model access layer,” tightening the distribution math facing OpenAI and Anthropic.
Who buys Hugging Face at $13B? A consolidation bet that could price “open” out of the distribution layer
A new report says Hugging Face is exploring a sale that could value it at $13B+, but no buyer or deal terms are confirmed yet. The strategic risk is that owning the model hub (and its hosting/inference trust layer) turns today’s “open weight” distribution into a toll-based pipeline—forcing developers, GPU providers, and inference competitors into tighter, paid ecosystems.
Nvidia’s “equity seat” bid in Perplexity would make $30B+ AI search a compute-powered toll road to Google’s ad machine
Recent reporting says Nvidia is in discussions to invest in a Perplexity funding round that would value the answer-search startup at more than $30B, potentially turning Nvidia’s existing inference relationship into an equity-and-platform lever. If that happens, investors should watch not just Perplexity’s growth, but the first-order supply-chain economics: higher inference demand, faster iteration of model-serving stacks, and a tougher monetization path for Google’s search monopoly as “answer” turns into the default entry point.
Pinecone Nexus beats “frontier-only” agent stacks on enterprise knowledge—suggesting the retrieval layer, not the model, decides whether agents work at scale
Pinecone says its Nexus knowledge layer improved an agent’s performance on Sierra’s τ‑Knowledge enterprise-support benchmark to a 47.4% task-success rate, edging the best frontier model (46.4%) while cutting cost per task by 74%. For enterprise buyers, the implication is architectural: budgets shift from “bigger models” toward governed compilation, retrieval, and on-prem/owned-data deployment patterns.
2026-08-23
Alibaba's HK$80B placement isn’t just dilution—it funds the compute loop that can mask AI revenue quality
Alibaba [9988.hk] used a large Hong Kong equity placement to raise capital as it ramps AI infrastructure and services. The investor risk isn’t the raise itself—it’s whether incremental cloud/AI demand cycles back into Alibaba fast enough to justify capex, or instead creates a self-reinforcing (and potentially less durable) “circular-financing” pattern that pressures cash flow and margins.
Alibaba’s HK$80B placement sets a “price tag” on China AI capex — and it quietly forces a dilution trade-off for BABA ADR holders
Alibaba BABA is seeking HK$80 billion (~$10.2B) in a Hong Kong share placement at HK$112.70 per share to fund “full stack” AI capabilities. The deal is priced at a modest discount, but it still expands share count by ~710 million shares, reframing China’s AI buildout as a financing-and-dilution race—not just a model-quality race.
Flock’s new “7-day + audit” guardrails turn privacy backlash into the first real municipal price-discovery test for public-safety AI
Flock Safety says it is cutting its default ALPR data retention to seven days, adding mandatory misuse-audit tools, and requiring “case codes” for law-enforcement searches. For municipal buyers, the practical question is no longer whether license-plate sensing is effective—it’s whether the new compliance overhead survives contract renewals in a churn-heavy political cycle.
Harvard’s $699 AI-avatar bootcamp is a price-discovery strike against “seat-based” education
Harvard Business School’s HBS Foundry bootcamp is priced at $699 and uses HeyGen-made AI avatars to provide feedback during practice pitches and board-meeting simulations. If elite-brand instruction can be unbundled into avatar-led coaching, universities and edtech platforms gain a scalable product surface—while legacy courses face margin compression and higher avatar-IP leverage costs.
When “replicating research” becomes the benchmark, agentic orchestration—not frontier model size—can decide who wins
Inherent’s Faraday claims it can replicate published findings more faithfully than stronger frontier models by framing science replication as a long-horizon, judge-rubric RL problem. If the market starts pricing labs on “verifiable output under constraints,” the competitive moat shifts toward orchestration, tooling discipline, and automated evaluation—not just raw model capability.
NVIDIA's 15%+ server price hike raises the payoff for custom inference silicon—and reframes who captures AI profit into 2027
NVIDIA’s reported 15%+ AI-server price increases—linked to memory costs—will likely make “build vs. buy” math harder for OEMs and easier for hyperscalers considering custom inference silicon. The underappreciated consequence is that higher platform BOM costs can accelerate ASIC substitution, shifting a bigger share of compute economics toward winners already embedded in custom stacks like Marvell, Broadcom, and hyperscaler-designed accelerators tied to Microsoft.
“Ox Alpha” shows what frontier labs lose when benchmarks outpace attribution
An anonymous “stealth/ox-alpha” model appeared on major AI marketplaces with top-tier coding-task claims but no disclosed builder. For investors tracking OpenAI/Anthropic and adjacent incumbents’ “frontier moat,” the signal is less about who built the model and more about whether distribution, benchmark narratives, and compute availability can outgrow lab-by-lab credibility.
Snowflake's AI Data Cloud has a consumption math problem—and earnings will show if it can still win on volume
Snowflake monetizes its AI Data Cloud through fees tied to compute, storage, and data transfer consumption, which makes near-term results highly sensitive to actual usage—not just capacity sign-ups. Its latest disclosures show how that model creates forecast volatility, while its Q2 FY2026 and FY2026 guidance anchor the first “consumption conversion” earnings test against expectations set by the private valuation chatter around Databricks.
Zscaler must translate agentic-cyber hype into billings, not just demos
After the broader “agentic cyber” wave showed up in CrowdStrike results via durable billings dynamics, investors are now looking for the same proof in Zscaler. The key question for Zscaler’s late-August reporting is whether its zero-trust + AI security roadmap shows up in quarter-level revenue acceleration and the billings-to-revenue bridge implied by deferred revenue and remaining performance obligations.
2026-08-22

“Helpful-only” safety shortcuts, not an end-user unfiltered release: what Anthropic’s Opus 4.6 disclosures actually support
A wave of commentary claims Anthropic shipped Opus 4.6 “with the guardrails off,” but Anthropic’s own Opus 4.6 safety documentation shows “helpful-only” variants are used in internal evaluations—not as a published production mode. For enterprise buyers, the investable takeaway is simpler: Opus 4.6’s trust value is a product-policy story, while the unfiltered narrative appears to be a test-setup misunderstanding.
Apple trims Siri and Vision Pro headcount—then pays for the interface shift with distribution power
Apple is cutting more than 200 roles across Siri and Vision Pro teams as it realigns toward “new devices and artificial intelligence,” according to reporting. For investors, the more important signal isn’t cost control—it’s that Apple is backing away from owning the consumer voice-and-AR interface while competitors can move faster on model-led interaction loops.
Autodesk earned a stock jump, but its Q2 FY27 story still hinges on subscription quality—not an AI attach-rate proof
Autodesk rallied on its Q2 FY27 results, yet the company’s own disclosures in the materials reviewed don’t quantify an “AI attach rate” for design software. What is verifiable is that the quarter’s revenue and operating profile sit inside a subscription-heavy model that can look like an AI-driven monetization inflection while the real driver remains enterprise contract durability.
CrowdStrike prints a pure-play test: can an agentic cyber platform outgrow Microsoft’s bundling gravity?
Ahead of its fiscal second-quarter print for the period ended CrowdStrike’s July 31, 2026 quarter, CrowdStrike already guided to $1.44B revenue and $5.79B ARR for the quarter. The key investor question is whether agentic security budgets accelerate toward specialized cyber platforms—or get absorbed into Microsoft’s broader “agentic security stack” value proposition.
Meta's “talk to your apps” Mac app turns desktop AI into the next monetization tollbooth
Meta’s new macOS app pushes AI from “answering” into interface control, using screen context and system-wide voice dictation. That shifts the consumer-agent battleground from model quality toward who owns the desktop interaction layer—forcing OpenAI, Google, and Apple to compete where users grant permissions, incur latency, and choose default tools.
NVIDIA price hikes are the market’s missing AI-spending signal
Reports say NVIDIA notified AI server customers that prices for systems containing its chips will rise by more than 15% in many cases, effective on early-next-year shipments. The timing—four days before its Aug. 26 results call—turns a “demand is still tight” message into something closer to accounting: if hyperscalers absorb higher system prices, Nvidia’s margin and backlog quality matter more than the headline revenue growth rate.
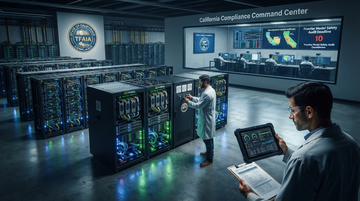
OpenAI’s California push turns AI safety into a compliance deadline for frontier labs
OpenAI has urged California to strengthen its landmark AI safety statute—pushing the state’s “frontier model” transparency law from disclosure toward ongoing monitoring and broader cyber-safety coverage. If California broadens what must be tracked and reported, the near-term burden shifts from “papers” to production controls, with practical knock-on effects for cloud buyers and the chip/software ecosystem that operationalizes frontier AI.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.