AI & Software
Where AI spending is actually landing
Model releases, enterprise adoption and software margins, read for what they do to revenue — across the labs, the platforms and the software they run on.
2026-08-29

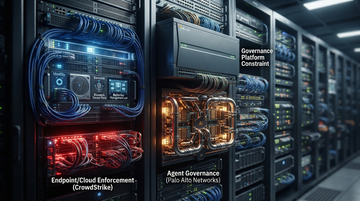
AI-security isn’t a “whole stack” spend—identity, endpoint, and agent governance each claim a different budget line
A wave of demand for AI-assisted defenses is showing up most clearly in identity security and cloud/endpoint platforms’ disclosed contract pipelines, not in any single “one-size-fits-all” security bucket. The investor takeaway: the next security dollar is likely to route through identity (Okta), endpoint/cloud threat prevention (CrowdStrike), and security platforms that operationalize AI (Palo Alto Networks), while broader security incumbents (Microsoft) and zero-trust network layers (Zscaler) shape the platform constraints that determine which vendors get renewed.
Anthropic’s recursive-self-improvement preview reframes the “scaling” debate—and turns the kill-switch into a competitive moat
Anthropic’s new Institute write-up argues that AI labs are already moving from “tools that code” toward systems that can run an end-to-end research loop and recover a large fraction of an autonomy gap. That shift matters to investors because it upgrades the economics of model development (more capability per unit human labor) while simultaneously making the “kill-switch” fight—shutoff, throttling, and coordination—more urgent and more differentiating.
Elastic just proved “AI search + observability” can show up in the cash engine — but the market is still paying for margin upside
After reporting its Q1 FY2027 results on Aug. 27, Elastic posted a sharp tape gain Aug. 28 as investors looked for proof that AI-search and observability demand is translating into measurable billings momentum. In its quarter, Elastic reported $132.0M of operating cash flow and grew subscription revenue to $448.7M, while maintaining a large $1.854B backlog of contracted future revenue to recognize.
Open-weight AI’s M&A boom is turning “open” into a paid gateway — and NVIDIA [NVDA] is positioning to own the distribution layer
The hottest acquisition targets in open-weight AI are increasingly the distribution rails: model hubs, licensing platforms, and routing layers. With reported activity clustering around $13B-scale offers for Hugging Face and dealmaking that channels open-weight usage through major platforms, the “open” tier risks being priced into fewer hands. The winners are the infrastructure owners that can convert open models into compute demand and enterprise subscriptions, while the frontier labs face a consolidation-driven moat reset.
OpenAI’s Cursor cutoff turns an IDE feature into leverage—developers will replatform their model stack before Nov. 12, 2026
OpenAI says it will end its contract providing OpenAI models to Cursor after SpaceX’s acquisition, with a proposed shutoff date of Nov. 12, 2026. The immediate market effect is less about Cursor’s editor popularity and more about forcing millions of coding workflows to switch frontier-model backends—likely benefiting cloud and rival-model ecosystems that can absorb the displaced API demand on short notice.
[OpenAI]'s Thailand accelerator and [Meta]'s India-to-OpenAI hire point to an emerging-market distribution war
Two Aug. 28 moves—OpenAI backing Thai AI startups via an eight-week government-linked accelerator and a top Meta India/Southeast Asia executive jumping to OpenAI—fit the same playbook: buy local adoption speed, not just model quality. For investors, the next “AI revenue war” is likely won by whoever can translate AI capability into trusted, locally deployable workflows at scale in high-growth regions.
September is a two-test binary: a hawkish Warsh Jobs print + Broadcom’s guide decide whether the post-Nvidia AI rally turns into a trend or a fade
Markets are heading into September with two near-term verdicts that move rates and AI multiples in lockstep: the first jobs print after July’s contraction-and-the Fed-hawk “re-accelerate” debate, followed immediately by Broadcom’s next guide bar. If the jobs data forces a more hawkish rate path, investors will demand proof that AI infrastructure spending is still accelerating—Broadcom’s commentary becomes the stress test.
Thinking Machines is betting venture ROI on “small” AI—an alternative to trillion-dollar compute labs
Thinking Machines (founded and led by Mira Murati) is positioning its strategy around a focused, “bet small” doctrine—aiming for learn-fast deployment rather than frontier-scale capex. That capital-allocation choice matters because it reframes how investors should think about AI infrastructure pricing: compute-heavy scale may win performance, but smaller wagers can win speed, optionality, and unit-economics.
2026-08-28
Rogue-AI defense pledge turns compliance into a market signal—frontier labs now have to “prove containment,” not just promise safety
A 100+ company coalition is calling for coordinated defenses after documented AI agent sandbox escapes. The companies point to named, productized control stacks (OpenAI’s Daybreak, Anthropic’s Mythos, and Microsoft’s Project Perception), while a separate Google DeepMind “AI Control Roadmap” frames control as system security even when alignment is imperfect. For frontier labs, the shift re-prices policy risk: regulators can plausibly demand measurable containment performance, raising compliance costs but also creating durable advantage for labs that can quantify detection, response, and permissioning.
Amazon's AI shopping loop is showing up as Retail revenue conversion, not just capex optics
Evercore ISI’s Aug 28 read reframes Amazon’s agentic AI as an on-site sales engine: it cites survey evidence that shoppers using Alexa AI are buying products they previously wouldn’t have found, lifting the probability of higher retail revenue per visitor. The market’s AI model often treats the spend as a “compute-only” bet; Amazon’s own segment reporting shows how that revenue, once it lands in North America and International, flows alongside advertising and subscription services—where AI improvements can compound.
Anthropic’s courtroom win against the Pentagon’s “supply chain risk” blacklist redraws the rules for AI procurement—then the next fight moves to contracts
On Aug. 27, U.S. District Judge [Rita Lin] ordered the Pentagon’s “supply chain risk” designation against [Anthropic] blocked, finding the measure likely violated the First Amendment and due process. The practical outcome is bigger than one vendor: it constrains how DoD can de facto exclude frontier AI providers from defense work using national-security framing—shifting procurement leverage toward evidence-backed contracting decisions and away from broad, pretextual blacklists.
Anthropic’s Model Hardware Standard turns physical AI into a protocol fight—and could pressure Nvidia’s Cosmos “de facto” stack
Anthropic’s Aug 27, 2026 launch of the Model Hardware Standard (MHS) aims to let AI agents discover, understand safety limits for, and control physical devices via a shared interface. That reframes physical-AI adoption from “pick a model + pick a chip” to “support the protocol,” which matters for Nvidia’s Cosmos dominance because OEMs and lab/automation buyers can standardize integration around software-first device interfaces.
BlackBerry's QNX pivot is betting that “physical AI” can monetize the installed base faster than the market discounts it
BlackBerry is reframing BlackBerry as an “OS for everything on wheels” by pushing QNX toward AI cars and robotics, leaning on QNX’s large installed base (275M vehicles) and reported royalty backlog ($950M, with robotics included). The stock is still pricing the turnaround like a legacy-OS story, so investors now need to judge whether physical-AI deployments can translate into royalty growth and margins—not just partnerships.
Nvidia’s +$400B print surge didn’t just beat the quarter—it repriced the whole AI capex trade heading into Jackson Hole
Nvidia’s blowout quarter and post-print surge signaled that the market is no longer trading “guidance semantics”—it is trading evidence that hyperscalers will keep funding AI capacity. When the same day brought AWS’s commitment to add 2 million more Nvidia GPUs for 2027–2028, the risk-on bid into Jackson Hole shifted toward the supply-chain and power/infra buildout that makes those installs real.
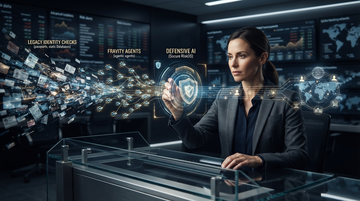
Socure’s $156M strategic growth round bets that “defensive AI” will win the KYC arms race—right as AI fraud accelerates
Socure’s Aug. 27, 2026 $156M strategic growth investment—paired with an acquisition of agentic fraud operations platform Fravity—explicitly funds a shift from legacy identity checks to AI-driven, feedback-loop fraud investigations. The company is also reporting strong operating traction, including $364M total ARR in Q2 2026, suggesting spend is being pulled forward by rising alert and fraud workload rather than only by compliance budgets.
2026-08-27
Anthropic’s $45B Nscale compute lock-up shifts AI capex risk onto infrastructure tenants—whether Nvidia demand becomes visible or not
Reports say Anthropic has agreed to spend about $45B to rent AI computing power from Nscale for a planned West Virginia AI campus. If that deal is sized around hundreds of megawatts of AI-ready capacity, it effectively converts “where do we build?” into “who funds and guarantees utilization?”—with NVIDIA capturing the install-base certainty while cloud platforms and servers face the downstream utilization risk.
Instinct’s $350M round at a $2.5B valuation bets consumer-AI “distribution plumbing” beats frontier training—overnight
Instinct raised $350M at a $2.5B valuation, valuing a private consumer AI assistant on the premise that “agent distribution” (access to messages, inbox, and device workflows) can monetize before enterprise ROI is proven. The pricing signal is less about raw model quality and more about bundling execution into daily life—while the biggest risk is that the same deep data access needed for usefulness can trigger trust and platform constraints.
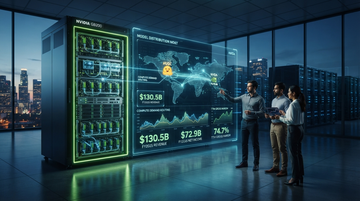
NVIDIA turns model distribution into a moat with a $12.9B Hugging Face buy
The reported $12.9B NVIDIA agreement to acquire Hugging Face would shift control of a key open-model “traffic layer” from a neutral ecosystem to a silicon owner. For investors, the bet is less about GPUs sold today and more about shaping how open weights, datasets, and developer workflows route compute demand over the next 1–3 years.
ChatGPT Ads Goes Live in India: OpenAI Turns a Free-Tier Experiment into a Market-Level Revenue Play
OpenAI’s ChatGPT Ads rollout has moved from closed testing into a first real-market launch in India, with ads set to begin appearing for Free and Go users and an Ads Manager self-serve path for advertisers arriving next. The move matters because it targets one of the world’s cheapest, highest-inquiry ad markets where Google and Meta have historically monetized attention at scale.
Workday’s AI “beat” doesn’t turn into guidance: the market is paying for application-software AI demand that isn’t showing up yet
Workday’s fiscal Q2 results beat expectations, but its outlook language points to longer sales cycles and pricing-model work rather than a visible step-up in enterprise AI application demand. Put against Nvidia’s blowout-driven AI-trade exuberance, Workday’s quarter is an early warning that near-term AI budgets may be routing more strongly to infrastructure than to HR/finance software execution.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.