AI & Software
Where AI spending is actually landing
Model releases, enterprise adoption and software margins, read for what they do to revenue — across the labs, the platforms and the software they run on.
2026-07-30

Mag-7 earnings are the first real “broadening” stress test—and the cap-weight is already doing the heavy lifting
The equal-weight S&P 500’s YTD lead suggests investors have been paying for “the average stock,” not just the largest tech complex. The first Mag-7 prints of the cycle (Meta and Microsoft) show why the divergence can flip: when leaders’ AI capex starts to pressure earnings quality, the cap-weight doesn’t just move with growth—it moves with expectations.
Meta’s capex jump buys AI time—but it risks starving FCF while Microsoft turns spend into service-margin growth
Meta and Microsoft printed a near-simultaneous capex signal, but the market’s read-through is likely less about AI demand and more about how each firm funds it. Meta’s latest reported cash flows show a large capex drain versus free cash flow, while Microsoft’s cash engine supports an even heavier buildout, implying power/cooling & connectivity vendors get paid sooner than advertising/consumer-internet margin holders.
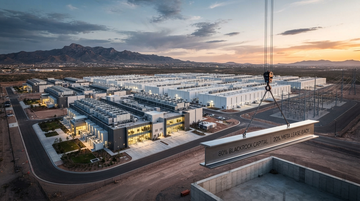
Meta's El Paso JV with BlackRock turns AI real-estate into pension-backed yield—without making Meta the bank
Meta will move the El Paso campus into a JV where BlackRock-managed funds hold 80% and Meta holds 20%, while Meta becomes the sole tenant via a long lease-back. The deal explicitly shifts AI infrastructure from a pure “capex deficit” debate to a “how cheaply can we finance long-lived boxes” debate—because part of BlackRock’s investment is funded with $12.5B of debt.
![Meta Platforms's Q2 FCF crater happens because capex rose faster than cash generation—and it flips the debate from 'earnings' to 'funding discipline'] insight cover](https://images-1379091077.cos.na-ashburn.myqcloud.com/insights/covers/20260730_meta_q2_2026_fcf_craters_ai_capex_double_down_2026_07_360px.png)
Meta Platforms's Q2 FCF crater happens because capex rose faster than cash generation—and it flips the debate from 'earnings' to 'funding discipline']
Meta’s Q2 cash flow shows free cash flow fell to about $1.7B while capex jumped to $30.1B, confirming the “AI capex first” regime with hard numbers. The immediate investor question shifts from whether AI monetizes soon to whether hyperscalers can sustain buybacks/credit ratings while front-loading capex.
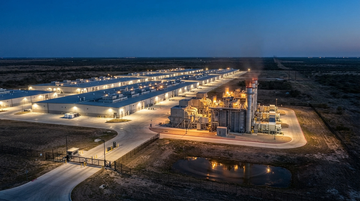
Google's $15B Nexus Loan Is Sovereign Finance in Disguise — and Alphabet's Capex Math Just Got Worse
Alphabet is guaranteeing the Morgan Stanley-led $14B bridge loan on Nexus Data Centers' 1.6 GW Texas gas-powered AI campus for Anthropic, taking ~20% equity in return — the third leg of a $35B+ backstop program that moves frontier compute off Google's balance sheet while keeping it on the hook. With Q2 capex already at $44.9B and free cash flow turning negative, the structure reveals the real constraint: not capital, but the gap between Google Cloud growth and depreciation absorption. Lenders win fees; Broadcom, AMD, and gas-turbine suppliers win volume; the question is what triggers Google's cash calls.
Nscale's $1.65B Anyscale Grab Hands Microsoft a Vertical-Stack Rival It Just Helped Build
London-based neocloud Nscale is buying Ray-creator Anyscale for a reported $1.65B, absorbing the open-source distributed-compute substrate that Microsoft co-engineered as a first-party Azure service just nine months ago. The deal converts a cloud-agnostic Ray ecosystem into Nscale's proprietary full-stack offering, tightening pressure on CoreWeave, Nebius and Lambda Labs while putting Microsoft's $23B Nscale compute commitment on a collision course with the same company's software roadmap.
The Aug 1 “voluntary” 30-day review makes OpenAI and Anthropic buy a government timeline—or lose it
A White House executive order (June 2, 2026) sets up a voluntary pre-release federal review framework for “covered frontier models,” with key agency deliverables feeding into an August 1 implementation milestone. If OpenAI MSFT and Anthropic (unlisted) are inside the first wave, they effectively turn a short window into a durable release-preemption advantage—while everyone else faces a longer, more political customer-acquisition and deployment lag.
Paramount–WBD’s news-archive consolidation could become a new “data bottleneck” — and cable/AI buyers pay the price
Archival producers warn that a Paramount–Warner Bros. Discovery deal could consolidate CNN/CBS news archives under one private owner, increasing gatekeeping over licensing and preservation. In parallel, AI training’s copyright-cost baseline has shifted—making archive access less like a media afterthought and more like a priced input for distribution and model training.
Reddit's AI Ad Engine Is Working—But Google May Be Training Its Own Traffic Threat
Reddit delivered $805 million of second-quarter revenue and $762 million of advertising revenue as AI-powered campaign automation improved advertiser performance. The tension is structural: the same AI ecosystem that helps Reddit sell more ads can also summarize Reddit discussions inside Google's search results, weakening the referral traffic and data leverage that support the platform. Investors should treat the ad product as the near-term earnings engine and search erosion as the long-term valuation risk.
Seagate didn’t “miss”—it proved the HAMR profit engine… and the market still priced in the harder margin math next
Seagate’s fiscal Q4 blowout (revenue and adjusted EPS both beating expectations) triggered a sell-the-news move that makes the next test less about “more TB shipped” and more about whether HAMR mass-capacity economics hold across the drive build-and-supply chain. For investors, the stock’s reaction matters because it shifts attention from die-count/technology headlines to tray/component margin durability—where suppliers and competing drive OEMs can win or lose first.
Zoox’s NHTSA “No Steering Wheel” Paid-Use Exemption Changes the AV Business Model Math
NHTSA granted Zoox a temporary, commercial-use exemption that caps deployment at 2,500 vehicles annually for two years—and it does so for purpose-built robotaxis that lack steering wheels and other human controls. This is not the same regulatory story as Waymo or Tesla: it explicitly uses the FMVSS-exemption pathway to remove “human fallback” assumptions from the safety and unit-economics equation.
2026-07-29
ChipAgents’ $60M funding bets AI agents can speed chip design—without breaking the EDA tollbooth
ChipAgents’ new $60M infusion extends an “agentic” approach to chip design and verification, aiming to compress the bug-finding and iteration loop that makes EDA such a sticky spend category. The key investor question isn’t whether AI reduces engineering time, but whether it routes more cycles into EDA workflows (verification runs grow) or starts to replace parts of the workload (tool seats and services get displaced). For incumbents like Cadence and Synopsys, near-term impact hinges on integration and workflow attachment rather than abstract AI throughput claims.
Cognizant’s weak quarterly guide implies clients are buying AI outcomes—but postponing the labor that makes outsourcing revenue easy
Cognizant’s Q2 outlook embeds a “more cautious near-term view” of discretionary spending while still holding full-year revenue steady, which points to timing risk rather than demand collapse. For AI budgets, the key question becomes whether spend is shifting from headcount-heavy IT services into AI infrastructure and automation—an outcome that would pressure traditional services economics even if long-term AI demand persists.
EssilorLuxottica’s Q2 smart-eyewear profit beat proves attach-rate—not novelty—can scale
In EssilorLuxottica’s Q2 print, AI-powered wearables and myopia management show up together with margin expansion, turning smart glasses from buzz into earnings validation. The second-order investor opportunity is the ecosystem that benefits once mainstream brands + optical retail install demand: lens/optics supply, AR display supply chains, and optical retailers with higher service-led attach.
Microsoft’s Cloud Beat Is Real—but AI Revenue Has to Clear a Utilization & Margin Wall
Microsoft’s latest results show cloud growth is strong enough to absorb AI buildout: Microsoft Cloud revenue rose 29% to $54.5B, while Azure and other cloud services grew 40%. The catch is that the same quarter also shows cloud margin pressure from ongoing AI infrastructure investment—so the market will judge the AI conversion not by demand, but by whether utilization and pricing eventually outpace depreciation and cost of revenue.
Qualcomm wins BMW’s next-decade cockpit + ADAS silicon—and turns the auto-semiconductor throne into a three-way fight with Mobileye and NVIDIA
BMW has selected Qualcomm as its lead compute silicon provider for the digital cockpit and next-generation ADAS/automated-driving systems through the next decade. The deal puts Qualcomm's Snapdragon Digital Chassis (including Snapdragon Cockpit and Snapdragon Ride) in direct competition with Mobileye's EyeQ-based approach and NVIDIA's Drive/Thor-style central compute, reshaping where investors should look for auto-semiconductor cash generation.
S&P Global [SPGI] just showed “AI cost-down” didn’t break its pricing power—yet the tollbooth is shifting from “data volume” to “trusted decision workflow”
In its latest quarter, [SPGI] grew total revenue to $4.146B (+10% y/y) while pushing adjusted operating margin to 54.3% (+200 bps y/y), including strong momentum in Ratings (+17% revenue) and Indices (+20%). The key durability test for an AI-led commoditization cycle is whether clients still pay for S&P Global’s workflow-trust layer—not whether AI can generate generic analysis cheaply.
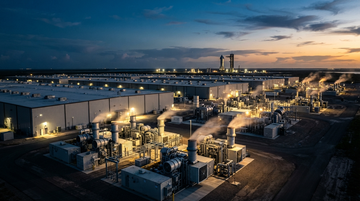
House Democrats Just Forced xAI/SpaceXAI to Answer a Clean-Air Permitting Loophole—Turning 27–60 “Unpermitted” Gas Turbines Into a Federal Risk
A House Energy & Commerce ranking-member letter to SpaceXAI demands documents and site-visit access about Colossus 1/2 turbines alleged to be operating “without air permits,” explicitly describing an attempted dodge via “mobile sources.” For hyperscalers planning behind-the-meter gas capacity, the message is simple: once on-site turbines reach scale, permitting becomes a federal oversight issue, pushing the market mix toward utility PPAs (and away from regulatory arbitrage).
2026-07-28
Amazon cutting most Nova models turns “build your own frontier stack” into a cash-flow problem
Amazon is deprecating/winding down most of its in-house flagship “Nova” AI models (Premier, Omni, Reel, Canvas), moving to a smaller set of frontier priorities. The implication for investors: the cost curve of maintaining a multi-model frontier portfolio is steep enough that AWS can’t outspend licensing and platform-scale routing through providers like Anthropic.
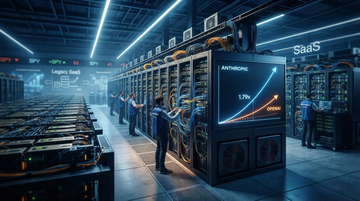
Anthropic’s ~$74.1B ARR run-rate turns “private mega-cap” into a measurable threat to public SaaS compounding in 2027
By July 2026, Anthropic is tracking at ~$74.1B in ARR/run-rate versus OpenAI’s ~$41.3B, about 1.79×, per ARR trackers. At that scale, even small shifts in developer mindshare and enterprise AI budgets can reallocate dollars away from public SaaS growth models—unless the incumbents’ distribution and platform economics keep outcompeting the model layer.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.