Latest
The day's market news, with the argument attached
New notes every trading day on earnings, policy and market structure. Each one opens with the conclusion, then the evidence, then the companies it hits.
2026-08-18

Braskem BAK ‘s Mexico Chapter 11 moves the ethane-cracker stress test to the front of the Americas petrochem trade
Braskem’s Mexico ethane-into-polyethylene footprint is entering a U.S.-court Chapter 11 restructuring, after consents designed to cut senior debt by more than $920MM. The event matters beyond Braskem BAK: it pressures the ethane-cracker operating model and turns the next move for U.S. ethane exporters and PE pricing from “tailwind” into “risk.”
Brookfield’s A$4.75 cash bid for Reliance Worldwide prices repair/remodel resilience into a plumbing-fittings roll-up
Brookfield Capital Partners has proposed buying Reliance Worldwide for A$4.75 per share, valuing the deal at about A$4.1 billion. The valuation hinges on a bet that Reliance Worldwide’s push-to-connect plumbing mix and US repair/remodel exposure can keep converting sales into cash even when new construction cools.
Cargill’s Fort Morgan restart just added ~20,000 head/week of US beef packing capacity—right when the “cattle squeeze” thesis needed it to stay tight
Cargill workers ratified a contract ending the Fort Morgan, Colorado lockout, with slaughter expected to restart the week of Sept. 7 and production ramping over the following weeks. Using the plant’s stated throughput (up to 4,700 head/day), the return of roughly 4 months of idled capacity is a direct supply release into a beef chain already sensitive to cattle availability—compressing the near-term probability that packers can keep tightening margins and that cattle/beef prices remain one-way.
If the SEC scrapped Rule 611, retail spreads could keep getting “paid” — just with a different balance sheet
The SEC’s June 11, 2026 proposal would rescind Regulation NMS’s intermarket trade-through protection (Rule 611) and the locked-and-crossed restriction (Rule 610(e). The key economic bet behind the debate is that weakening exchange-to-exchange price protection changes how retail brokers route orders, how wholesalers (including PFOF arrangements) monetize the spread, and which venues bear more of the execution-cost risk.
Xfinity Security Is Comcast’s Quiet Broadband Defense: The Attach Rate Will Matter More Than the Spin
Comcast is preparing to separate its media assets as part of the NBCUniversal spin plan, but its higher-frequency, cash-generating playbook remains in the access business. Xfinity Home Security pricing and monitoring terms show a retention-led bundling strategy whose success depends less on “launch hype” and more on whether security attach prevents broadband value erosion when fixed-wireless and fiber pressure forces price moves.
Disney-ABC’s FCC license fight turns broadcast “risk” into an injunction-or-discount binary
The FCC forced Walt Disney Company’s ABC stations into an early license-renewal proceeding focused on possible workplace discrimination-rule violations. Disney-ABC’s new federal lawsuit seeks an injunction against the FCC’s accelerated process—exactly the kind of ruling that can compress (or harden) the “viewpoint risk premium” investors apply to station-group renewal economics, reshaping how buyers underwrite local-market broadcast assets.
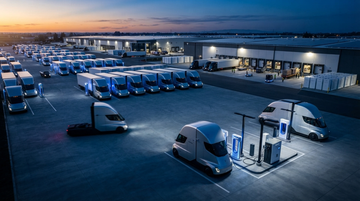
Tesla's non-auto truck bet gets a real fleet test: Einride's 500-Semi rollout targets September 2026 start
Einride says it will deploy 500 Tesla Semi trucks across North America on its Saga AI platform starting in September 2026. For investors, the order is less about near-term vehicle volume and more about whether electric trucking economics can clear a full fleet TCO hurdle—while also stress-testing Tesla's non-auto revenue mix and charging-related capex needs.
FDA’s generative-AI device rulemaking starts Aug. 18: compliance costs will concentrate in companies that already run “real-world” validation
On Aug. 18, 2026 the FDA opened the formal public-feedback phase for regulating generative-AI-enabled medical devices, centered on risk assessment, premarket “competency assessment,” and postmarket monitoring. The near-term market impact is less about who gets first approvals and more about who can afford the validation tax—making established medtech platforms with existing QA and clinical-feedback loops structurally advantaged versus AI-native startups.
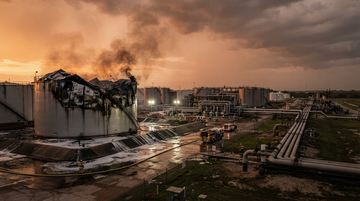
Lightning Tore Through a US Fuel “Bottleneck” — and Crack-Spread Trades Now Have a Physical Supply Shock Washington Didn’t Model
A lightning-triggered fire at the Explorer Pipeline Glenpool tank farm in Oklahoma forced operations to shut and is now tightening refined-product supply logistics on a key pipeline corridor. For crack-spread trades, the implication is simple: even if Washington caps “refinery output” expectations, physical downtime at storage/transport nodes can still move forward the timing (and size) of product shortages that widen differentials.
Fulcrum Therapeutics pays for the Slate Medicines merger with equity—and the $245M financing sets a clearer biotech funding window
Fulcrum Therapeutics and Slate Medicines have agreed to combine in an all-stock deal that comes with a $245M concurrent private placement for the Slate side, plus a $270M special dividend for Fulcrum holders at closing. The structure is a direct signal that, for small-cap genetic/next-gen drug developers, the cash-constrained consolidation path right now is equity-first—using capital markets timing and pipeline risk-sharing rather than pure cash buyouts.
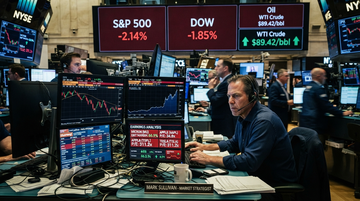
Long-end yields at multi-decade highs are now a direct equity valuation test: what to watch when the bond slump spills into earnings
On Aug 18, 2026, global bond prices slid sharply and long-term borrowing costs pushed to multi-decade highs, coinciding with oil strength and pressure on US stock-index futures. The equity transmission is not just “rates up”: higher long yields mechanically compress the value of distant cash flows and immediately tighten the financing and housing channels that can feed into margins and demand over the next few quarters.
Google's $10M Spirit data buy exposes the “crown-jewel” playbook for airline bankruptcies
Google agreed to pay $10 million to acquire deidentified Spirit Airlines business data in a bankruptcy auction—an unusually small price for an unusually large, decision-relevant dataset. The financial tell isn’t the amount; it’s the asset class: operational and enterprise workflow history is now monetized the way equipment was, with AI buyers effectively competing for “institutional memory.”
Loan-price slides are rewriting “earnings clarity” risk: Guggenheim’s 77% drop shows how fast private-credit marks can spill into earnings
A Guggenheim-affiliated financing entity clarified a steep second-quarter earnings decline after loan-price slides followed a disclosure. The episode highlights how rapidly loan-mark volatility can force “explanation” language—turning what looked like stable credit management into a new earnings-disclosure risk as rates stay elevated.
Klarna's revenue guide cut reframes BNPL: growth is easy, monetization under credit pressure is the hard part
Klarna KLAR reiterated an early-2026 run-rate in Q1, but its later-quarter guidance implies a slower revenue trajectory even as users keep expanding. The market is now pricing the BNPL trade-off: onboarding more consumers may not lift revenue per user fast enough when credit provisions and funding economics stay elevated.
Meta's 29-state trial is forcing a reprice of “liability” more than “break-up”
The 29-state youth-safety trial places Instagram and Facebook under direct scrutiny for how product design decisions affect children—an exposure that tends to price as recurring costs and mandated product changes. With Meta also running heavy AI capex, investors now have to reconcile legal-driven friction with cash-flow funding needs, not just a binary divestiture outcome.
Molson Coors’ Q2 test shows beer’s pricing power is still positive—but cost pressure is now dominating the earnings story
In Molson Coors, Q2 2026 net sales fell 3.3% as volumes slid 5.4%, partially offset by favorable pricing and mix of +1.8%. The key investor takeaway is that cost headwinds are the swing factor: underlying income before taxes dropped 27.8% (constant currency) as COGS pressures included an estimated ~$40M Midwest Premium drag in the quarter and a forecast of >$130M for full-year 2026.
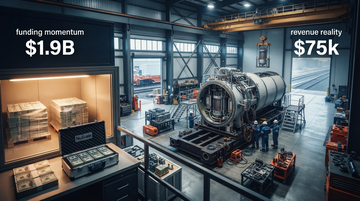
NuScale Power revenue barely exists—while liquidity swells, and the timing matters more than the narrative
In NuScale Power’s Q2 2026 results, revenue totaled just $75k for the quarter while cash, cash equivalents, and investments rose to $1.9B—an extreme mismatch that forces investors to separate “funding momentum” from “revenue reality.” The filing ties the year-over-year revenue plunge to completed Fluor FEED Phase 2 work in late 2025 and the absence of comparable 2026 activity, not a broken business model at every moment; but it still shows that the SMR economics are pacing far behind the AI power-demand storyline.
NVIDIA turns $1.5B into an equity seat on OpenAI’s Ohio data-center developer
NVIDIA will invest $1.5B into SB Energy to secure land, power, and shell capacity at the PORTS‑Pike AI data-center campus that OpenAI leases under a 20‑year structure. The move shifts NVIDIA from “compute-only” supplier into an ownership-and-credit participant in the project’s developer layer—tightening the demand loop between NVIDIA, SB Energy, and SoftBank/OpenAI while concentrating upside and tail-risk in the same chain.
OpenAI’s PORTS-Pike move reframes frontier AI as critical-infrastructure security work—where “workload reliability” can become a contractable capability
OpenAI’s Aug. 17, 2026 announcement ties frontier compute to the PORTS-Pike data-center campus in Pike County, Ohio, with a 20-year tenant deal and a capacity ramp starting in 2028. The strategic significance isn’t the data center itself—it’s how the announcement’s emphasis on resilient, qualification-driven infrastructure and longer “mean time between interruptions” mirrors how U.S. port operators are expected to document and plan cyber risk under Coast Guard guidance.
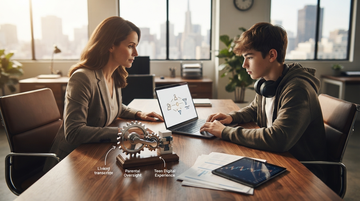
OpenAI’s “ChatGPT for Teens” shifts the legal center of gravity from feed algorithms to product controls
OpenAI’s new teens experience pairs age-prediction with default “reduced sensitive content,” crisis escalation rules, and parent/guardian “linking” that does not expose chat transcripts. For investors, the strategic punch is that it treats COPPA-style compliance as a product feature—reducing the kind of teen-exposure risk courts have been punishing in social-media ad and recommendation feeds.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.