Latest
The day's market news, with the argument attached
New notes every trading day on earnings, policy and market structure. Each one opens with the conclusion, then the evidence, then the companies it hits.
2026-08-15

Fiserv faces a credibility test: why Jana trimming ~17% right after the guide reset matters more than the spotlight on SMB payments
Jana Partners reduced its position in Fiserv by roughly 17% in Q2 2026, immediately after the company’s earnings reset and amid activist calls for a broader portfolio review. For investors focused on the “SMB payments floor” narrative, the stake cut reframes the debate: it shifts Fiserv’s path to multiple expansion away from a single volume floor and toward the hard mechanics of consolidation, asset-sale optionality, and near-term cash flow.
Jane Street’s alleged $15B July loss turns the “AI crowded trade” into a balance-sheet contagion risk
Reporting tied to a private AI hedge fund’s forced unwind has put a $15B monthly hit on Jane Street, reframing July’s AI volatility as more than a sentiment reset. The key issue for investors: when highly correlated AI positions unwind through leverage and prime-broker financing, the market-making layer can absorb correlated shocks and transmit stress upstream and downstream through liquidity and pricing.
JPMorgan’s quiet Polymarket debanking shows the real chokepoint is the banking rail, not the CFTC
Reuters reported JPMorgan terminated its banking relationship with Polymarket in October, citing regulatory concerns—an event that reframes the prediction-market boom as a compliance-and-rail access story. At the same time, World Liberty’s move toward a national trust charter underscores a widening split: crypto platforms want “banking comfort,” while banks want controllable risk under federal oversight.
Payward’s crypto-winter slump shows the toll-booth model breaks when retail volume stays dead — not when trading activity merely dips
Payward (the parent of Kraken) reported Q2 2026 adjusted revenue of $508M (+17% YoY) alongside a cost-and-liquidity pivot that kept adjusted EBITDA positive at $23M, even as total platform transaction volume fell 18% YoY. The key investor takeaway is that “stable assets on platform” and “more funded accounts” are not enough to protect fee-style P&L when the volume engine (especially retail-driven spot) doesn’t rebound.
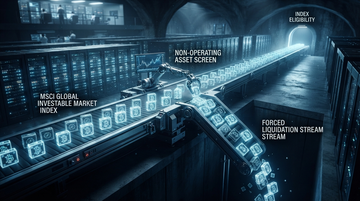
MSCI plants a “non-operating” eligibility trap that makes Strategy’s bitcoin treasury structure a forced-sale risk
MSCI has launched a consultation to screen “non-operating” companies out of its MSCI Global Investable Market Indexes, using operating-asset intensity and cash-flow style ratios. If rules are implemented for index changes effective at the close of Aug. 31, 2026, Strategy is exposed because its balance sheet is dominated by investment assets rather than operating assets, and the market impact can cascade through passive flows and forced crypto rebalancing by similarly structured issuers.
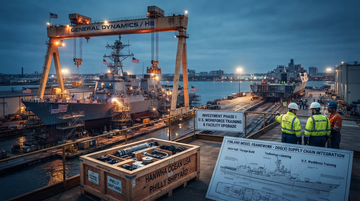
Trump’s “Finland Model” opens a limited route for foreign-built U.S. Navy hulls—Hanwha Ocean and Fincantieri gain optionality while GD/HII lose their “U.S.-only yard” pricing power
A White House memorandum signed Aug. 13, 2026 lets qualifying foreign shipbuilders build initial Navy hulls abroad while requiring major U.S. yard investment, U.S. workforce training, U.S. supply-chain sourcing, and technology licensing. The near-term demand signal is most supportive for Hanwha Ocean and Fincantieri, because they already have large U.S. shipyard footprints, while the traditional U.S. prime shipyard duopoly faces a structurally wider builder base and more competitive capacity.
Nvidia’s Ohio OpenAI guarantee just got smaller—what that says about who really funds the AI data-center build-out
Reports that Nvidia is pulling back its planned Ohio OpenAI financing guarantee are the first visible downgrade to the “Nvidia-as-lender” style of AI infrastructure dealmaking. The key shift for investors: less construction/funding risk stays on Nvidia’s balance-sheet narrative, and more of it reverts to hyperscalers, data-center developers/landlords, and the financing stack behind them.
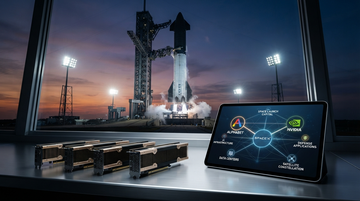
Nvidia’s $21B SpaceX stake turns mega-cap AI cash into launch/defense equity—and concentrates risk where demand can’t be rerouted fast
Nvidia NVDA disclosed a roughly $21B SpaceX position in its latest 13F-HR (as of June 30, 2026), making SpaceX one of its biggest strategic equity exposures. The same ownership map also shows Alphabet’s decade-old bet at about $94B and Tiger Global’s entry, underscoring a new, self-reinforcing loop: AI infrastructure economics can increasingly decide space launch capital, and that concentration can magnify governance and cash-use second-order risks.
SEC’s $74M “boiler room” case puts retail cash economics behind private-share liquidity—and shows why hidden fees are now the center of the fraud story
The SEC charged Andrew Spaventa and three related entities with defrauding more than 800 mostly retail investors—including many retirees—through unregistered pre-IPO private fund offerings tied to companies including SpaceX, Anduril, and Anthropic. In the SEC’s allegations, investors were paid “hidden fees” created by large markups—turning private-company liquidity into a fee-heavy distribution channel the SEC says reached Main Street on cold calls.
SK Hynix's $38B memory-fab plan won’t ease supply until after Dec 2028
SK Hynix approved about ₩54.3T (≈$38.30B) for two new fabs whose first cleanrooms open in Dec 2028 (NAND) and Jun 2029 (DRAM/Yongin Y2), with construction beginning in 2027. That 2.5-year capex-to-cleanroom gap is the cleanest timing proof that AI-driven tightness can persist even as the next capacity wave is already locked in—quietly shifting the market from a short squeeze to a longer-dated overhang risk.
SKYE–Redx’s $125M fibrosis deal is less about size and more about timing: the market is funding “Phase 2 readiness” before H2 2028 topline
Skye Bioscience will acquire UK fibrosis biotech Redx Pharma to form Fibrx Therapeutics, with concurrent financings totaling about $125M and a stated plan to keep the combined company funded into 2029. The thesis for investors is straightforward: small-cap fibrosis assets are consolidating now to preserve a runway to RXC008 Phase 2 results expected in H2 2028—before GLP-1-linked capital rotations decide what gets trial funding next.
SpaceX’s Closed Cursor Deal Turns an AI Coding “Oligopoly” Into a Distribution Fight
SpaceX SPCX made its $60.0B all-stock Cursor (Anysphere) acquisition effective on Aug. 14, 2026—converting Cursor shareholders into 389,289,254 shares of SpaceX Class A stock. The immediate market impact is less about model quality and more about which developer tools get privileged distribution inside a vertically integrated “Musk stack,” potentially pressuring pricing and partner leverage for GitHub Copilot and other coding-agent workflows.
The UK 10-year at ~5% is “breaking” the equity rally’s rates script
On Aug 14, 2026, the UK 10-year gilt yield traded around 5.04% while the US 10-year sat near 4.70% and the S&P 500 closed near 7,786. That Atlantic spread is the market’s way of pricing a UK-duration risk premium without demanding a US-style equity de-rating—yet it raises the odds that hedging flows and bank funding costs re-price first, before equities do.
UMich’s sentiment breaks lower while 1-year inflation expectations jump to 4.3%—the September rate-cut debate just gained a credibility test
The University of Michigan’s August preliminary print showed the Consumer Sentiment Index sliding to 51.0 from 55.2, while 1-year inflation expectations rose to 4.3% from 4.2%. That combination matters because it targets the Fed’s core risk: expectations unanchoring, not just headline CPI prints.
Walmart’s Q2 FY27 print hits Aug. 20—what the consumer “slow” story must prove (and what would break it)
On Aug. 20, Walmart reports Q2 FY27, right after July retail sales showed the first month-over-month dip in months. The market won’t just trade the headline—investors should pressure-test whether Walmart’s comps, margin drivers (including tariff-refund timing), and pharmacy/weight-management momentum indicate slowing, not breaking consumer demand.
World Liberty’s bank charter turns crypto lending into a deposit bet—and the conflict-of-interest “discount” is the real valuation driver
The U.S. Office of the Comptroller of the Currency (OCC) granted World Liberty Trust Company a conditional preliminary approval for a national trust bank charter that would let the group issue and redeem its USD1 stablecoin and custody/convert related assets. The approval also bakes in governance passivity commitments meant to curb investor control, while critics argue the structure still creates a political-economy “ethics discount” that could weigh on adoption and partnerships—especially where stablecoin issuance and custody sit at the center of the lending supply chain.
Writer’s “harness” makes inference cost a first-class product—challenging frontier labs to compete on economics, not just benchmarks
Writer’s new Palmyra X6 release pairs a purpose-built enterprise agent “harness” with token-cost governance, reporting large reductions in cost-per-task alongside maintained task quality. The underlying claim is blunt: orchestration choices can cut enterprise agent spend by ~41% without model swaps, shifting differentiation toward inference economics and control-layer performance.
2026-08-14
Apple's Mac mini Texas shift turns “Made in USA” into a COGS experiment — and it flows through EMS more than patriotism
Apple opened its Houston Advanced Manufacturing Center on Aug. 13, 2026 and tied it to starting Mac mini production “later this year” in Texas, marking the first time the Mac mini is made in the U.S. for sale. The investment matters to margins only if the higher-cost U.S. assembly footprint can be neutralized via supplier localization, logistics control, and tariff-avoidance—an outcome the first steady-state volume run will test.
Apple’s China AI pivot: training its own China model with Alibaba help reframes who captures the iPhone margin
Reuters reports Apple has trained a large language model specifically for China, using Alibaba support—rather than leaning solely on Alibaba’s Qwen. The shift doesn’t remove Qwen; it changes Apple’s leverage in China regulatory clearance, reduces “vendor dependency,” and forces investors to reassess how China AI dollars split between the device platform and the model provider.
Apple turning Siri news into a paid licensing product—shifting the AI news war toward “distribution economics”
A new report says Apple is in talks to pay publishers for current news used by an upgraded Siri, including a proposed variable, per-use style structure. If that becomes real, it validates “assistant licensing” as publisher revenue and reframes competition: premium outlets gain a new direct channel, while Alphabet and Microsoft face a harder content-cost baseline when answers route through Apple devices.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.