Latest
The day's market news, with the argument attached
New notes every trading day on earnings, policy and market structure. Each one opens with the conclusion, then the evidence, then the companies it hits.
2026-08-14

OpenAI’s GPT‑5.6 “Ultrafast” mode makes latency—not token price—rewrite who wins AI inference
OpenAI previewed GPT‑5.6 Sol “Ultrafast” with up to 14× faster output and up to 750 tokens/second, explicitly pitching ultra-low-latency inference (not cheaper tokens) as the differentiator. The underappreciated investor angle: when latency becomes the primary product metric, inference capacity economics shift toward architectures that can sustain interactive speeds—re-pricing demand for different compute stacks and agent workflows.
Pentagon’s SM-3 “restock” plan is now a factory-capacity bet (Boeing & RTX)
Framework agreements signed by the U.S. Pentagon with Boeing and RTX aim to scale the production of specific SM-3 interceptor components—not place a simple new missile order—shifting the restock story to a bottleneck question. The near-term market takeaway: component-output ramp capability at primes and propulsion/rocket-supply partners matters as much as the headline procurement numbers.
Reddit joining the S&P 500 looks like a forced-buy story—until the real tax shows up when the crowding reverses
S&P Dow Jones Indices said Reddit will replace AvalonBay in the S&P 500 effective Aug. 18, 2026, a change that typically pulls index-tracking capital into RDDT and pushes it out of AVB. The headline pop is easier to explain than the after—once forced flows fade, the stock’s move increasingly reflects what passive owners do when liquidity and ownership concentration are no longer the driver.
SEC’s “pay-to-play” easing would change who wins public pension mandates—and how alternative managers fund growth
The SEC’s proposal to loosen the Investment Advisers Act “pay-to-play” firewall (Rule 206(4)-5) would reduce a key fundraising cost for alternative managers chasing state and local money, but it also reopens conflict and governance risk that the 2010 rule was designed to price out. For allocators and investors, the core question is whether the SEC’s narrower restrictions still deter politically motivated adviser selection without shifting enforcement and compliance burden elsewhere.
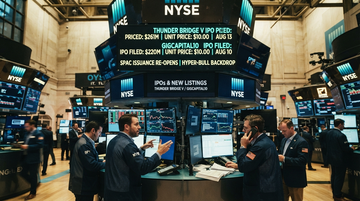
SPACs are pricing again: Thunder Bridge V raises $261M and GigCapital10 filed $220M—classic signs of a “frothy window” investors may be underpricing
Two new blank-check offerings hitting the tape in close succession—Thunder Bridge Capital Partners V, Ltd. pricing a $261M IPO on Aug. 13 and GigCapital10—re-opening a primary-IPO supply line that has been mostly quiet. The amounts are not just deal flow; they change the near-term math for underwriting desks and, more importantly, compress time-to-deal for targets—at exactly the kind of “hyper-bull” backdrop Bank of America has flagged as frothy.
Stellantis’ Canada exit would be the real overcapacity tell—because it targets Brampton capacity first
Unifor says Stellantis is considering selling its Toronto-area Brampton assembly plant, not just idling it—an investor-relevant signal that capacity rationalization is getting sharper. The decision matters beyond Canada: it changes where component volume flows, which suppliers keep allocated labor, and how OEMs compete to rebuild the next low-tariff production lane.
Tapestry's FY27 outlook makes the “affordable-luxury re-rating” a numbers test: Coach is accelerating, but tariffs and terminated Capri costs can still cap the multiple
In its fiscal-Q4 results released Aug. 13, 2026, Tapestry showed Coach delivering double-digit growth (Q4 net sales +15% reported) while explicitly acknowledging a negative tariff and duty impact that partially offset margin gains. The same print also tallies material Capri-related termination/divestiture impacts (notably $268.4M of pre-tax expenses in FY25 tied to the terminated Capri deal), setting up a clean investor question: does Coach momentum outweigh cost/tariff noise in the next few quarters?
Tencent’s revenue beat comes with a hard constraint: it “funds” AI with prepayments, not free cash—so compute buildout depends on timing, not optimism
Tencent beat on 2Q2026 revenue (RMB 204.8B, +11% YoY) while AI-related compute procurement drove capex to RMB 52.8B (+176% YoY) and flipped free cash flow to -RMB 13.8B. The takeaway for China’s AI “next check” moment is straightforward: Tencent’s cash engine can finance buildout, but the quarter-to-quarter check size is constrained by how much of that financing arrives as prepayments versus cash generated. Investors should track whether operating cash flow can keep pace with compute procurement—because that timing will decide which US-listed AI and semiconductor names benefit first.
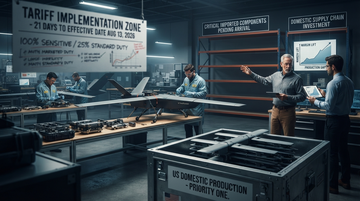
Drone tariffs can lift U.S. drone margins fast—but they cannot replace the Pentagon’s missing production capacity
Trump’s Aug. 13, 2026 drone-tariff package raises duties on imported drones (including 100% on “particularly sensitive” platforms, 25% on smaller drones, and 15% on covered allied countries) starting 21 days after signing. The immediate market read-through for UMAC, RCAT, ONDS, AVAV, and KTOS is a short-cycle pricing and sourcing repricing, not a volume solution. The Pentagon’s own assessment of a years-long U.S. industrial-output gap means tariffs are a margin catalyst, while capacity still depends on procurement programs and industrial base investment.
YETI’s Q2 shows premium demand still holds—while tariff and China-sourcing costs are the swing factor investors can’t ignore
In YETI’s Q2 reporting, premium hard goods performance and gross margin behavior point to a cleaner split between demand resilience and sourcing-cost pressure. That matters because the mass-affluent consumer signal only shows up when the margin headwind is isolated—otherwise retail tape noise can mask what’s actually moving.
2026-08-13
Thoma Bravo’s $4B all-cash take-private turns Accelerant into a private ‘software toll booth’—a verdict on where underwriting value is actually manufactured
Thoma Bravo agreed to buy Accelerant Holdings in an all-cash deal valued at more than $4B, with shareholders receiving $20.25 per share. The pricing matters for the “software-defined insurance” debate: it treats Accelerant’s MGA/distribution software and workflow layer as the value engine, not underwriting capital—while many public insurtechs are still priced like hardware.
Ackman’s Netflix re-entry is a value signal: the streaming winner now looks priced like a cash utility
Bill Ackman’s Pershing Square has disclosed a fresh Netflix stake alongside new positions in Visa and Mastercard, reframing the mega-cap growth crowd back toward cash-flow durability. With Netflix running at an annualized revenue base near $48.4B and free cash flow of ~$11.0B on the latest trailing window, this looks like a bet that “streaming wars” have ended and the market is over-discounting the remaining cash engine.
Amazon turns Twitch into default AI training data—and the legal risk shifts from “opt-in consent” to a copyright compliance cliff
Twitch has added a “Training for Generative AI” setting that’s on by default, letting Amazon use stream content to train generative AI unless creators actively opt out. The move doesn’t just expand training data—it raises a sharper copyright/consent question because livestream platforms are high-frequency, expressive, and often reused downstream, while opt-out rates are structurally low.
Anthropic’s Decart talks point to a new AI moat: buying inference-efficiency, not just more compute
Anthropic is reportedly in early talks to acquire Decart AI in a deal discussed at around $6 billion, with Decart focused on inference and training performance optimization across chips. If completed, the acquisition would shift Anthropic from “GPU procurement” toward “system-level utilization,” where small gains in latency and throughput can compound into materially more usable capacity for its Claude workloads.
Birkenstock’s raised FY2026 revenue outlook tests the premium-discretionary bear case—and it passed
Birkenstock lifted its FY2026 outlook after its latest quarterly update, signaling it can protect growth and pricing even while discretionary category debates keep swinging. The contrast with lululemon’s weaker trend underscores a live “split consumer” test: inventory discipline and brand heat can outperform when the market assumes all premium demand is rolling over.
Cerebras just proved inference-only isn’t enough: margins reset—then the market repriced the moat
Cerebras’s first earnings as a public company showed revenue growing quickly, but gross margin (and especially “core” margin) reset sharply from the company’s prior high levels. The market punished the economics the same day Nvidia’s system moat would normally keep competitors’ inference bets from turning into durable profitability.
Cognition’s reported ~$40B round reframes coding agents as an engineering-substitution bet—not an “AI tool” upgrade
A reported valuation jump toward ~$40B for Cognition’s autonomous coding agent strengthens the market’s willingness to price software labor displacement as a near-term product economics problem. The investor question is no longer “can agents write code?”—it’s whether agentic workflows keep converting into repeatable buyer spend faster than enterprise engineering teams can adapt.
A.P. Møller-Mærsk A/S captures reroute pricing power while Hapag-Lloyd AG absorbs the Middle East cost shock
Maersk’s Q2 2026 results helped it lift full-year guidance for 2026 for a second time, framing Middle East disruption as a pricing and demand tailwind. By contrast, Hapag-Lloyd disclosed a Middle East cost shock in its 2026 results messaging—without showing the same offsetting uplift—making container liners an “earnings divergence” trade tied to contract exposure, not a uniform sector story.
The de minimis loophole is formally dead—so Temu/Shein’s “$0 duties” math breaks, and parcel carriers face a new cost reality
On June 24, 2026, CBP published interim final rules that indefinitely suspend the $800 de minimis administrative exemption and replace the mail pathway with a new informal-entry workflow effective July 24, 2026. The policy change forces more low-value imports into duty/tax collection and data-and-bond handling—an immediate margin squeeze for cross-border discounters like PDD’s PDD, and a near-term process-and-volume repricing moment for UPS and FedEx.
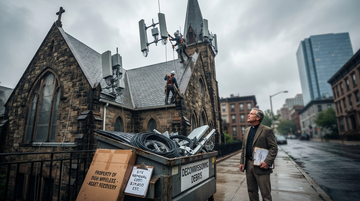
Dish’s bankruptcy is pushing $40,000 antenna-removal bills onto churches—while a $2.4B FCC fund tries to ring-fence who pays
Dish’s Chapter 11 unwind is creating a highly visible “stranded cost” problem: property owners that hosted Dish’s wireless antennas are facing removal bills even as Dish seeks to abandon network assets. The mechanism is an FCC-ordered $2.4B decommissioning trust tied to the AT&T spectrum transaction—intended to reimburse qualified 5G decommissioning claims, but not to fully prevent all local fallout.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.