Latest
The day's market news, with the argument attached
New notes every trading day on earnings, policy and market structure. Each one opens with the conclusion, then the evidence, then the companies it hits.
2026-08-07

Sweetgreen proves the “fresh-supply moat” can fracture when consumers fear the food category—not the brand
Sweetgreen cut full-year guidance after linking weaker demand since mid-July to a multistate cyclosporiasis (Cyclospora) outbreak. The key market read-through: in fast-casual, brand safety processes can be structurally irrelevant when the category’s perceived risk rises faster than companies can reassure customers.
Take-Two’s GTA VI launch date is a bookings test—FY2027 net bookings target rises to $8.0B–$8.2B if the blockbuster restarts the engine
Take-Two is tying its FY2027 Net Bookings outlook to the November 19, 2026 launch of Grand Theft Auto VI. The key question for investors is whether that headline release can lift a business where recurrent consumer spending already drives 78% of FY2026 net bookings—not just spike full-game sales. The real value-chain impact will show up first in bookings conversion and then in how durable recurrent spending remains after the initial launch wave.
Washington is moving from “AI guardrails” to “voluntary frontier access”—and the compliance burden is likely shifting onto model buyers, not model labs
In Executive Order 14409, the Trump administration explicitly rejects mandatory federal licensing or preclearance for new frontier AI models while creating a voluntary early-access process with up to a 30-day window. For investors, the second-order effect is straightforward: fewer gatekeepers inside model development, but more governance work for enterprises and downstream platforms deciding whether—and how—to deploy covered frontier capabilities.
Trump’s “Regulate AI Out of Business” Line Signals a Break From the Pre‑Regulation Coalition—and It Reprices AI Policy Risk Fast for Microsoft, Alphabet, NVIDIA, and AMD
The White House has already built an executive-branch “frontier model” review pathway with 30‑day timelines and no mandatory licensing. But Trump’s Aug 7 public framing of AI regulation as “out of business” would shift leverage from agencies’ voluntary access model toward Congress-driven, industry-constraining rules—changing the near-term probability distribution for AI monetization, cloud demand timing, and compute capex.
Under Armour UAA is forecasting a sharper 2026 sales drop because North America demand is breaking the “Nike turnaround” script—suggesting the discount-tier in US sportswear is now its own structural industry
Under Armour UAA just disclosed an outlook that implies a faster 2026 North America deterioration and lower full-year revenue expectations versus its earlier “slight decline” framing. The investment takeaway isn’t just weaker sales—it’s that the category is splitting: Nike NKE appears to be stabilizing at the premium end, while Under Armour’s wholesale-heavy, value/discount positioning faces persistent demand softness that compresses the whole margin stack.
2026-08-06
Asia’s AI pullback is the first real test of the rotation—because semis and memory are where “fly” turns into “fund the catch-up”
On Aug 5–6, 2026, Reuters documented an Asia tech pullback led by semiconductors and AI-linked names even as the Dow closed at a record in the prior U.S. session—evidence that the AI rotation is no longer strictly a U.S. large-cap phenomenon. The market’s next step is less about whether AI demand exists and more about whether the funding chain (cash generation and capex) can sustain it through valuation reset pockets in memory, foundry equipment, and compute accelerators.
Airbnb's Q2 Beat Looks Like Pricing + Take-Rate Discipline—Not a Sustainable Demand Step-Up
In Airbnb's Q2 print, the key investor question is whether growth came from more room nights or from better monetization (ADR and implied take rate). The company’s own framing around the FIFA World Cup 2026 “tailwind” makes this read a mix-shift test: revenue can beat even if room-night growth is only steady—as long as monetization holds through the event’s rollout curve.
Alphabet’s bond comeback proves hyperscalers can fund AI capex in investment grade—but without covenants, the credit model may stay fragile
Alphabet is funding a ~$180B–$190B 2026 capex push with a deliberate mix of operating cash flow and fresh debt/investment-grade capital-market access. The key market signal isn’t leverage—it’s that investors are underwriting flexibility (not protections), which can keep the IG-to-AI-capex channel open while making it more sensitive to any AI spending repricing.
Advanced Micro Devices guides Q3 to ~$13B yet the stock sells off because the market is buying a whisper-number trade, not the printed beat
AMD’s Q3 revenue guide lands above consensus, but the after-hours move signals investors were underwriting a higher “duration” AI expectation than management’s range implies. Layered together with AMD’s newly disclosed AI-infrastructure initiatives (notably Helios/Anthropic and inference workload partnerships), the tape reads like a repricing of how fast deployments convert into revenue—not a collapse of demand.
Why Carlyle’s “Exit Window Is Open” Call Matters: Q2 fee rebound suggests public markets—not PE deal-making—are regaining pricing power
Carlyle’s Aug 5 comments imply PE exits are thawing mainly for “good companies” where public-market buyers can credibly price risk again. The company’s latest financials support the timing: Carlyle shows a sharp uptick in fee-related profitability metrics in the lead-up to that message, making listed-market liquidity a first-order driver for secondary/IPO clearing.
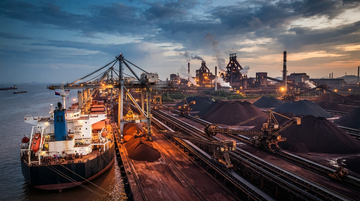
Yuan-Price Iron Ore Would Break the Dollar Benchmark Lock—And Reprice the Largest China Seaborne Deals Faster Than Prices Move
China’s steel and iron-and-steel leadership is pushing for a CNY-denominated iron ore price index to anchor contract pricing alongside (and increasingly in place of) dollar benchmarks. If implemented at scale, it would shift how Vale VALE and BHP BHP settle long-term and spot-linked formulas, changing FX-adjusted margins and hedging needs more than the headline iron ore price alone.
ConocoPhillips accelerates its exit plan with a Ryan Lance transition—so the Permian deal window may already be narrowing
ConocoPhillips is pairing a dated leadership succession with an accelerated asset monetization pace, including a $1.3B disposition to push disposition proceeds ahead of schedule. For Permian-focused independents, the investor implication is that the highest-quality “harvest” assets may be getting absorbed faster than marginal acreage can clear at peak multiples.
The Walt Disney Company's Q2 Print Turns Streaming vs. ESPN vs. Parks Into a Margin Fork, Not a Growth Narrative
Disney’s first Q2 2026 earnings print after the A+E exit announcement reframes the stock’s debate: the streaming engine is showing sharp operating-income expansion, while ESPN’s sports-rights cost burden is explicitly weighing on segment profitability and parks are decelerating at the margin. Investors now have to underwrite a three-part cash machine—streaming margins, ESPN rights inflation, and parks attendance/operating momentum—rather than treating streaming as the single growth lever.
eBay's focus-category guidance quietly rotates the buyer mix toward luxury and collectibles—right as Etsy cuts teams tied to growth execution
eBay’s latest outlook ties its momentum to “focus categories” and Depop, with third-quarter GMV guidance of 22.0–22.4 (FX-neutral +10% to +12%). Etsy, by contrast, is shrinking its marketplace workforce and absorbing charges while its active buyers drift lower—making the competitive shift in buyer mix the real battleground.
FCC repeals the 39% national TV-station cap—opening the door to true mega-merger economics for Nexstar, Sinclair, and Gray
The FCC moved to replace the bright-line 39% national multiple-ownership restriction in 47 CFR §73.3555(e) with transaction-specific, public-interest case review, slated for action at its August 6, 2026 open meeting. For investors, the real signal isn’t “a rule got softened”—it’s that consolidation math that was structurally blocked before now has a clearer regulatory path, changing both deal incentives and the likely competitive map across local TV cash flows.
Fed’s Cook Reopened the Hike Door—But Rate-Cut Bets Still Look Crowded
Fed Governor Lisa Cook put a hawkish floor under the next move: if disinflation doesn’t show up “in a timely manner,” she’s prepared to raise rates, even while she’s willing to “give a bit more time.” That asymmetry matters for markets that have priced a September cut narrative more than a hike tail, and it reshuffles near-term winners across banks, REITs, and rate-sensitive duration.
Fiserv FISV cuts 2026 EPS outlook to $7.20–$7.40 and signals organic revenue at (1%) to 0%—what a mid-cycle guide cut usually means for US SMB payments volumes
Fiserv’s 2026 outlook update moves the center of gravity from “execution” to “demand/volume risk,” with organic revenue now guided to (1%)–0% and adjusted EPS to $7.20–$7.40. For investors, the key question is whether this is a one-off transformation drag or the first marker of an SMB-tightening cycle that pressures Clover-style POS processing and shifts wallet share against challengers like Toast and Global Payments.
Alphabet moves Hassabis to “chief scientist”—and markets are pricing a faster productization bottleneck, not a routine rotation
Alphabet GOOG shifted Demis Hassabis out of the day-to-day [DeepMind] CEO role, re-centering him as Alphabet chief scientist while Koray Kavukcuoglu takes day-to-day leadership. The stock reaction (about -4% intraday) is consistent with investors fearing that Google’s AI frontier-to-product pipeline now depends more on execution bandwidth than research leadership continuity.
Insulet's US guidance cut shows Omnipod is priced like a reimbursement negotiation product, not a TAM story
Insulet beat Q2 expectations but cut full-year U.S. Omnipod revenue guidance (constant-currency growth) to 17%–19%, down from 20%–22%—a move the market treated like a structural “pricing trap.” The read-through is that diabetes hardware demand in the U.S. is increasingly gated by payer terms and coverage velocity, shifting outcomes for DexCom, Abbott, and Medtronic.
AI memory cash mountains are turning into a payout ultimatum for Samsung Electronics and SK hynix
Fresh Reuters reporting shows foreign shareholders are pushing Samsung Electronics and SK hynix to return more cash via dividends/buybacks while management stays tight-lipped on timing and amounts. The investor math is simple: with both companies generating very large cash flow during the AI memory cycle, the next debate in Korea won’t just be capex—it will be how much of that AI cash mountain becomes shareholder income versus capacity spend.
What to expect
Evidence-first notes with a visible point of view.
This section collects sharp takes on earnings, shareholder meetings, and market structure. Each new piece should make the thesis, the facts, and the implications obvious within the first few screens.
Expect direct analysis, not generic commentary.
Expect the data to be explicit and the argument to be easy to follow.